
AI in Clinical Trials Market to Reach USD 7.32 Billion by 2034 as AI Reshapes Patient Recruitment, Data Analysis and Drug Development, says Maximize Market Research
Source: PR Newswire
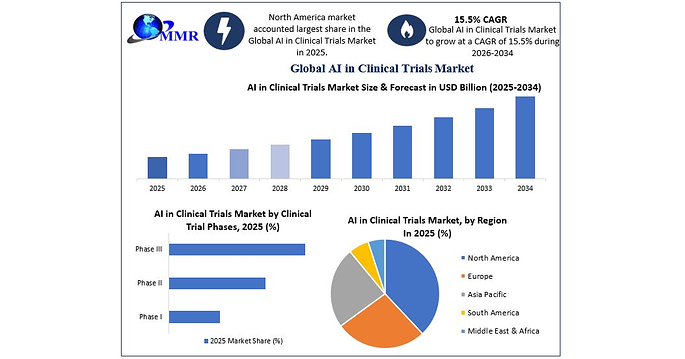
Maximize Market Research forecasts the global AI-in-clinical-trials market will grow from $2.0 billion in 2025 to $7.32 billion by 2034, a 15.5% CAGR. Growth is expected to be driven by AI-enabled patient recruitment, trial design, clinical-data analysis, safety monitoring and drug discovery, with North America leading adoption. Data privacy, regulatory compliance, data quality and shortages of specialized AI expertise remain key constraints to broader deployment.
Analysis
This is not an earnings-relevant demand signal for IQV: the addressable software layer remains too small relative to its services base, and a third-party market forecast should not change estimates. The investable mechanism is instead operating leverage: AI that reduces site activation, query resolution, and enrollment-cycle friction can lift CRO gross margin before it produces meaningful incremental revenue. IQV is better positioned than smaller point-solution vendors because it can distribute workflow tools through embedded sponsor relationships and proprietary trial-data infrastructure; VEEV and Dassault Systemes (DSY, owner of Medidata) are the closest scaled software beneficiaries.
Near term, AI adoption is more likely to redistribute spend within sponsor R&D budgets than expand them. Sponsors will demand measurable reductions in protocol amendments, enrollment duration, and monitoring cost, creating pricing pressure for standalone vendors such as unprofitable clinical-AI companies that lack validated regulatory workflows. IBM's opportunity is indirect and likely immaterial to consolidated earnings unless it secures large, governed data-platform deployments; generic-model capability is becoming commoditized while auditability, data rights, and integration become the economic moat.
The contrarian view is that consensus overstates the speed of margin capture. Clinical-development savings require prospective validation and acceptance by sponsors, sites, and regulators; opaque models can add documentation burden rather than remove it. Over the next 6-18 months, the key differentiator will be disclosed customer production deployments and measurable cycle-time savings, not partnership announcements or AI-feature launches. A material increase in FDA scrutiny of model validation, data provenance, or algorithmic bias would delay procurement and favor incumbents with validated electronic data-capture and quality-management systems.
For IQV, watch quarterly book-to-bill, backlog conversion, and adjusted EBITDA margin rather than AI revenue claims. The thesis is falsified if AI-enabled workflow investment fails to support margin expansion despite stable utilization, or if large pharma customers shift data layers toward VEEV/DSY and compress CRO pricing. This press-release-derived forecast alone has low informational value and does not justify a directional position before company-specific KPI disclosure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade on this report; treat it as a watch item because the market-size estimate is not independently verifiable and is unlikely to move FY earnings estimates for IQV or IBM.
- Build a 6-12 month relative-value watchlist: long IQV versus short a basket of smaller, cash-burning clinical-AI/private-market proxies only after IQV demonstrates two consecutive quarters of stable-to-rising adjusted EBITDA margin alongside improving bookings. The expected payoff is incumbent operating leverage; exit if backlog growth decelerates materially or margin contracts.
- Prefer VEEV or DSY exposure over IBM for regulated clinical-data software optionality, contingent on disclosed enterprise conversion metrics for AI-enabled trial workflows. Avoid assigning an AI multiple premium without evidence of higher subscription growth or net revenue retention.
- Set an event alert around FDA guidance, enforcement actions, or sponsor disclosures involving AI-supported trial decisions over the next 1-3 months. A formal validation or transparency requirement would be a near-term negative for point solutions but a relative positive for VEEV, DSY, and IQV due to compliance infrastructure.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Facebook found liable as TikTok settles for $100m over user safety
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- What would a US diesel export ban mean for global fuel prices?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?
- Earnings-Triggered Research Automations: A Control Guide