
North Carolina Railroad Company Invests $600,000 in Scotland County Rail Project
Source: PR Newswire
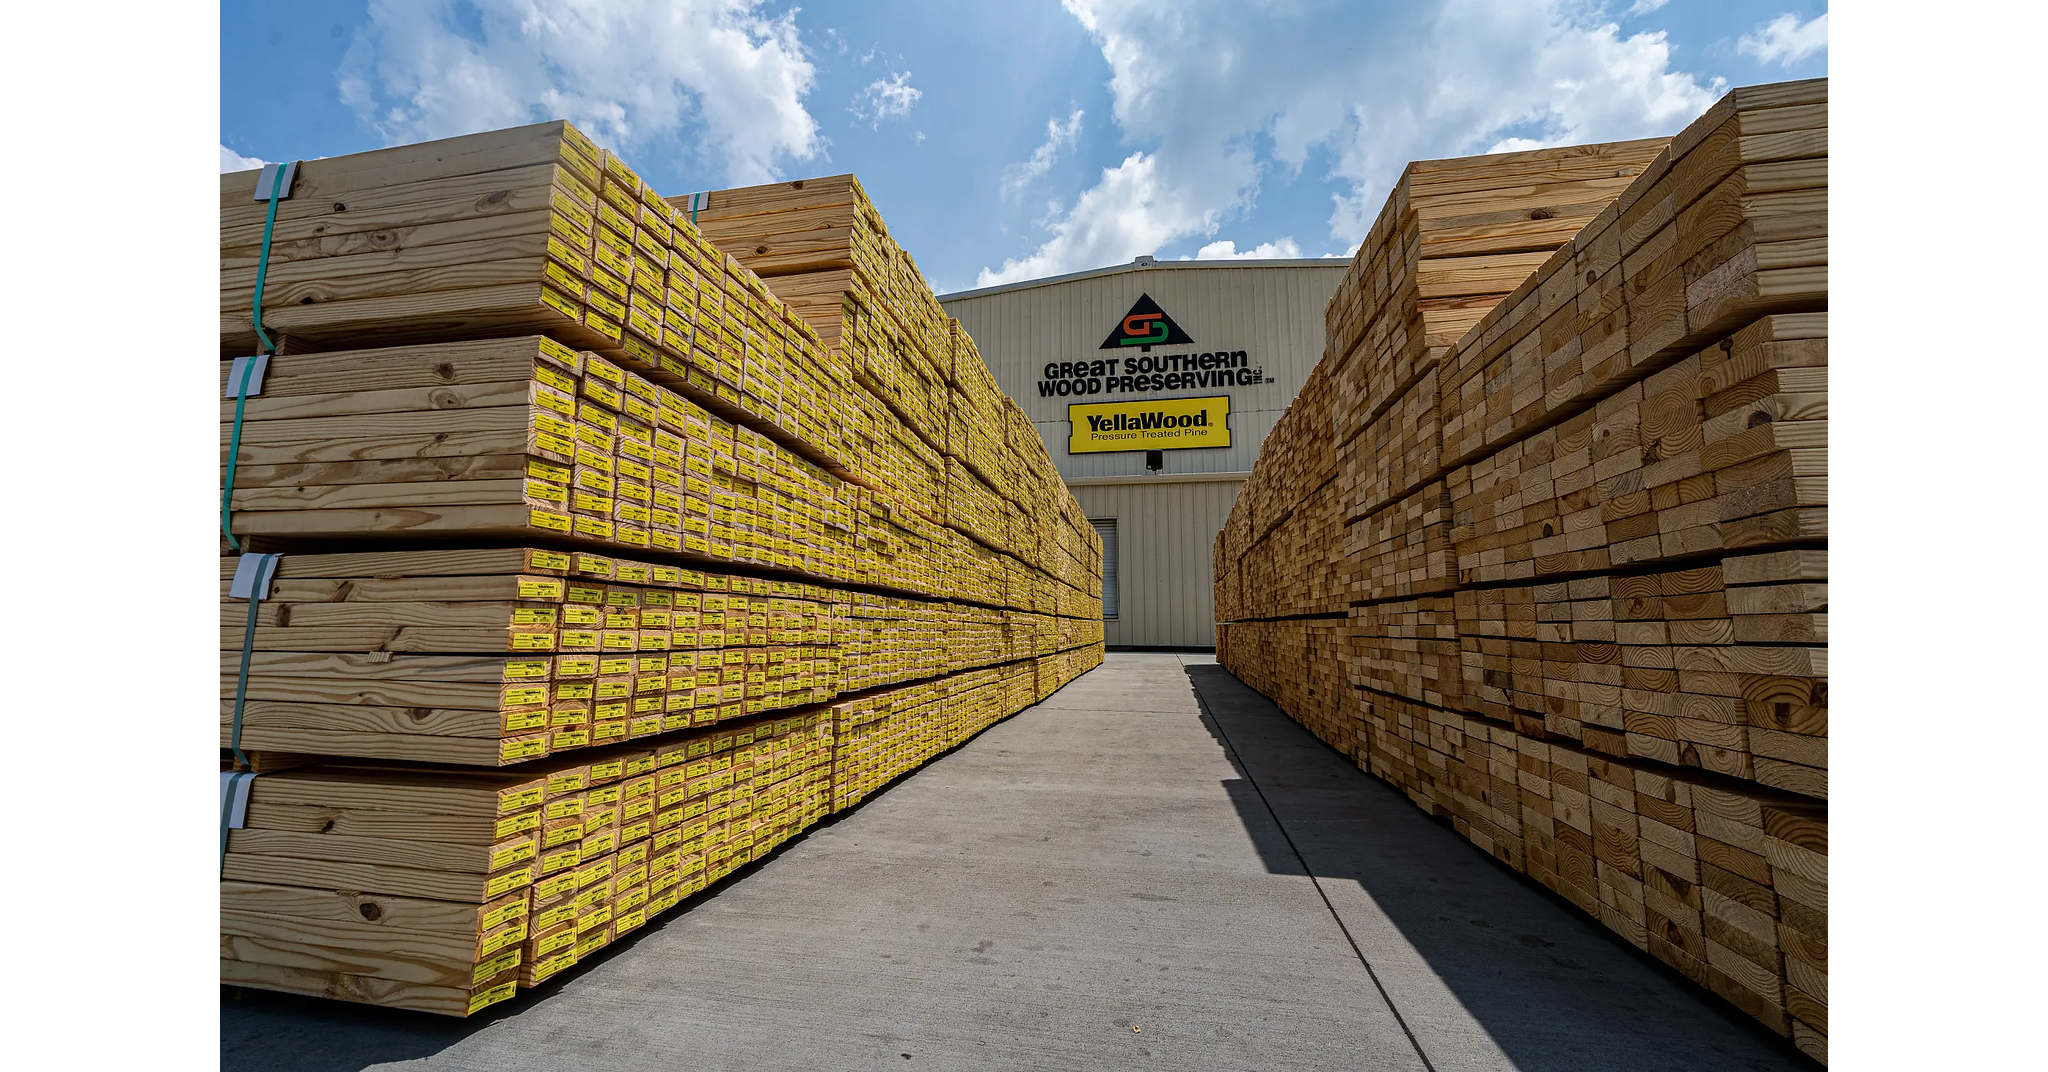
North Carolina Railroad Company will invest up to $600,000 via NCRR Invests to support Great Southern Wood-NC’s $40 million Scotland County manufacturing project, expected to create 40+ full-time jobs. The rail infrastructure is designed to enable at least 421 railcar shipments annually by 2030 for the company’s new lumber treatment facility near Laurinburg-Maxton Airport. The effort is framed as using private railroad revenue (not taxpayer funds) to improve supply-chain efficiency and competitiveness.
Analysis
This is a micro-scale industrial siting signal, not an earnings event. For DUK, the only real read-through is incremental Carolinas load growth and a slightly stronger case for future distribution capex, but the economics are too small to move the stock unless this is the first in a cluster of similar projects. The more important second-order effect is that rail-served manufacturing keeps the region competitive for additional low- to mid-intensity industrial users, which matters to utility load forecasts and local land economics over time.
The competitive benefit accrues to rail-accessible manufacturers versus truck-only peers: lower delivered cost, better inventory turns, and less exposure to diesel volatility. But the end market is still cyclical and tied to housing/repair demand, so utilization can disappoint if single-family starts or dealer orders soften over the next 1-3 quarters. For public comps, the better lens is not the project itself but whether Southeast industrial placement trends support future volumes for rail operators and utility demand in the Carolinas.
Contrarian takeaway: the market should not pay up for this headline. Consensus may over-interpret local development announcements as a broad industrial acceleration, when in reality the investable signal is only that public/private infrastructure is lowering friction for future projects. The thesis is falsified if DUK’s next load forecast or rate case commentary shows no upward revision, or if housing-related demand weakens enough that the facility ramps below the implied carload cadence.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- Do not initiate a standalone position in DUK on this announcement; use it only as a watch item for the next Carolinas load/rate-base update. Falsify the thesis if DUK’s next guidance or IRP commentary does not show improved industrial load growth.
- If you want exposure, prefer a small relative-value long DUK / short XLU only on weakness over the next 1-3 months. Risk/reward is modest: upside comes from better regional load visibility, while downside is that this remains too small to change the utility’s earnings trajectory.
- Do not touch PUCCF as a tradable expression unless liquidity and disclosure improve. Treat it as a non-actionable proxy; reassess only if additional rail-served projects or a broader volume pipeline are announced.
- Watch housing-sensitive building-products names such as WY, UFPI, and LPX for real operating read-through, but only after confirming volume data. The announcement alone is not enough to justify a long; the catalyst would be sustained dealer demand, not the facility opening itself.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Proxy Wars Threaten to Engulf Ethiopia
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand