
Sun Auto Tire & Service Celebrates 600th Store Milestone with Opening of New Plaza Tire Service in Bowling Green, Kentucky
Source: PR Newswire
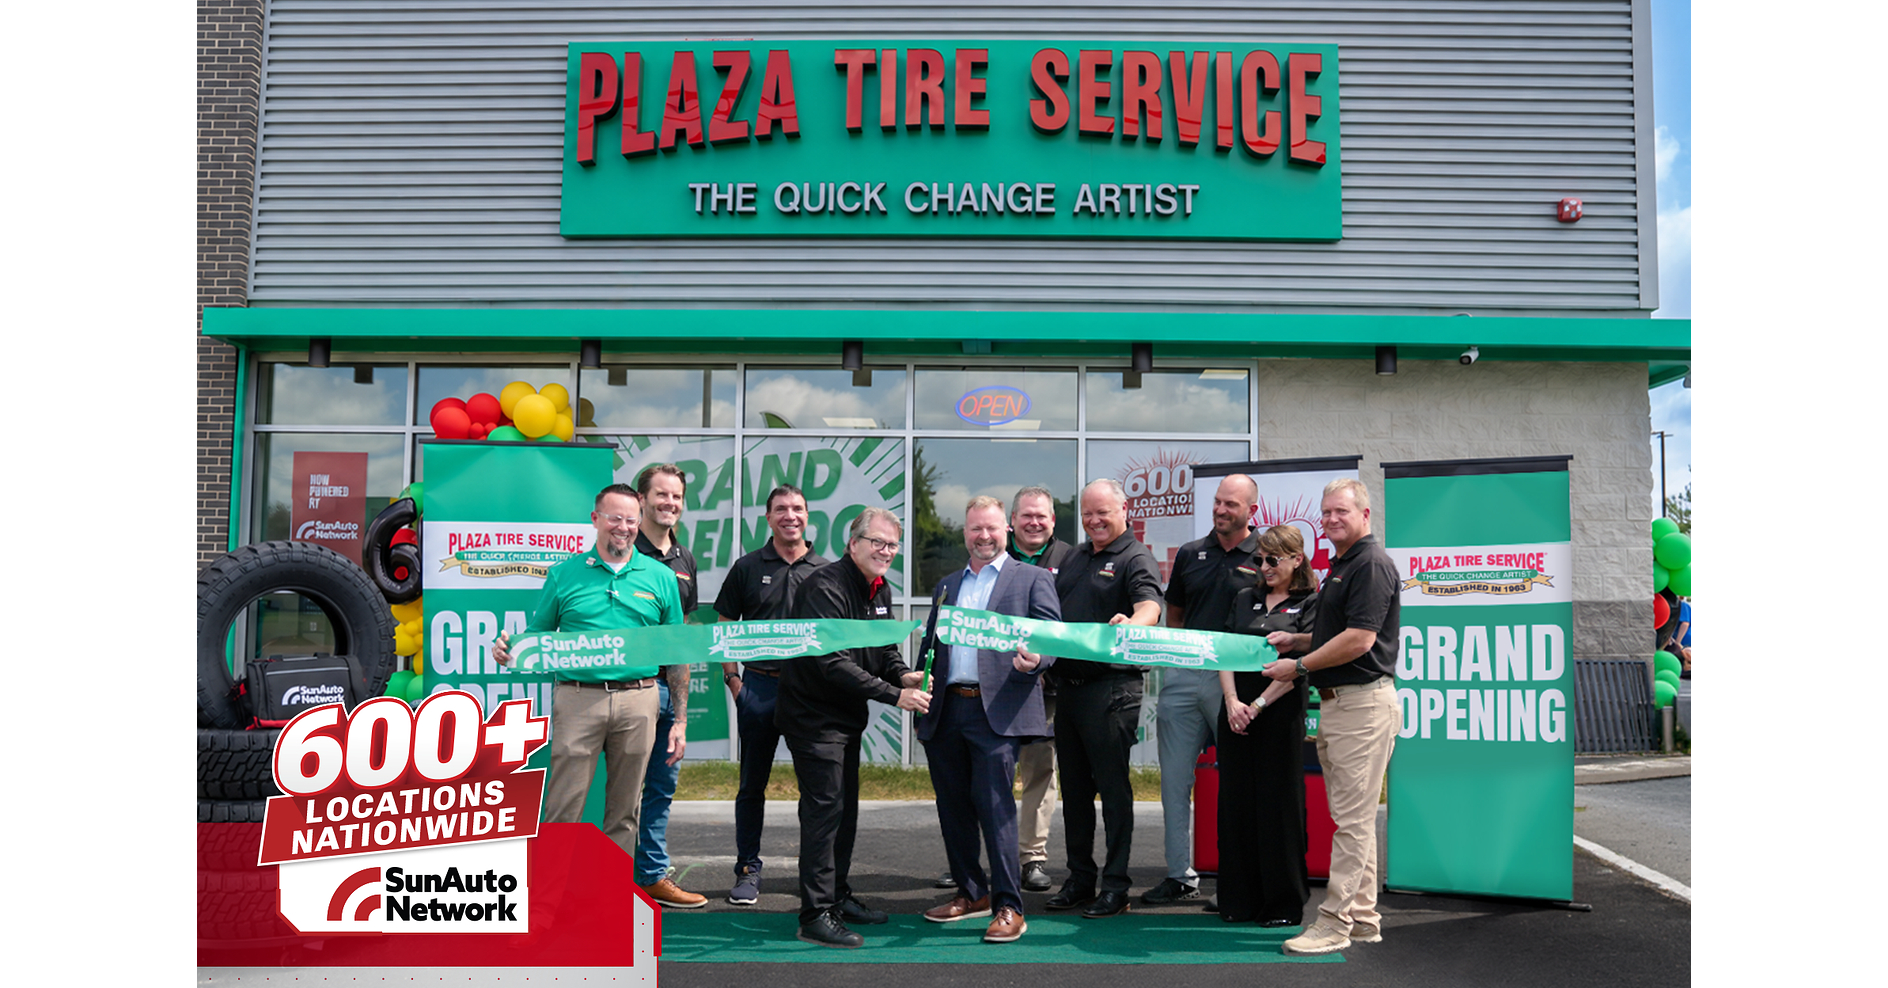
Sun Auto Tire & Service opened its 600th store—a Plaza Tire Service location in Bowling Green, KY—expanding from ~30 locations in 2017 to 600+ stores across 27 states. The company also achieved Better Business Bureau (BBB) Accreditation across its entire network and is rolling out digital customer tools (online appointments and digital vehicle inspections). The announcement is operational and brand-focused, with limited direct implications for broader market pricing.
Analysis
This is a scale signal, not a fundamental re-rate. In a fragmented repair market, the economic value of the 600-store footprint comes from procurement leverage, technician utilization, and lead conversion efficiency; the store count itself is only a proxy. The practical winner is the scaled public comp set with similar operating leverage, especially ORLY on the parts/distribution side and, more selectively, MNRO as a direct service proxy if it can show it is not losing share to larger, digitally-enabled chains.
The second-order read is competitive pressure on smaller independents, not a demand windfall. A national chain with more standardized booking and inspection workflows can squeeze local operators by offering faster turnaround and more consistent pricing, which matters most in dense suburban markets over the next 6-18 months. That said, the BBB angle is mostly marketing; it does not tell us anything about ticket growth, warranty cost, or margin durability, so I would not infer a near-term financial inflection from it.
Contrarian view: the market may be over-attributing strategic significance to a store milestone that could have been achieved with mediocre unit economics. The real question is whether new locations generate above-cost-of-capital returns after labor and rent inflation, and whether they improve same-store sales at mature stores via brand spillover. Falsifiers are simple: if ORLY/MNRO report decelerating comps, margin compression, or weakening repair demand as used-car prices normalize, then the consolidation thesis is just narrative. Otherwise, this reads as a slow-burn share shift rather than an immediate catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No direct trade in the private operator; treat this as a sector watch item until public comps confirm margin or share gains.
- Small tactical pair: long ORLY / short MNRO over the next 1-3 months into earnings, betting that scale and procurement leverage outperform a smaller service chain; exit if MNRO shows sustained gross-margin expansion or ORLY comp growth slows.
- Add ORLY on a pullback of 5% or more if broader auto-aftermarket data remain stable; the thesis is 6-18 month share gain from consolidation, not this press release.
- Watch MNRO same-store sales, labor expense, and SG&A leverage as the key falsifiers; if operating leverage does not improve, the stock remains vulnerable to multiple compression.
- If you want an even cleaner expression, use an ORLY/MNRO relative-value spread rather than outright directional exposure; the edge is in market-share dispersion, not the broader demand tape.
More News
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies