
YFORE, pionera en espejos digitales, presenta su gama completa de espejos inteligentes en Norteamérica
Source: PR Newswire
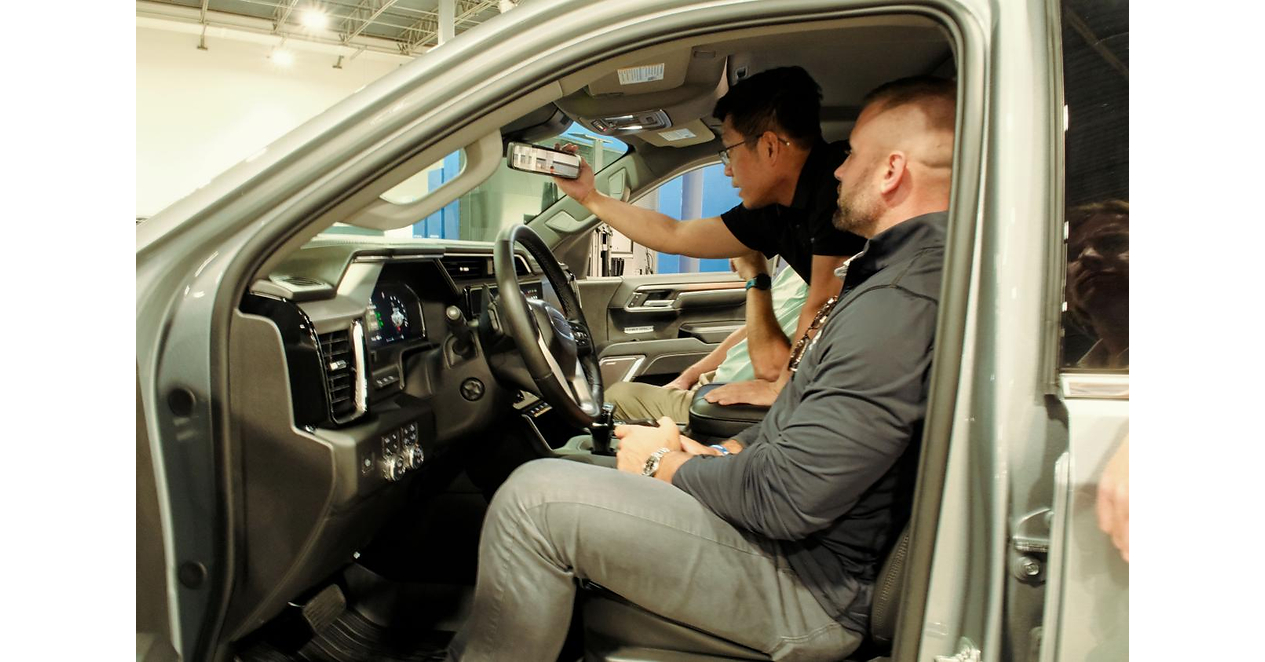
YFORE, proveedor Tier-1 de electrónica para automoción, inauguró oficialmente una nueva planta de fabricación en Estados Unidos cerca de Atlanta (Georgia) y lanzó en Norteamérica su gama completa de espejos digitales, con debut mundial de un espejo multifuncional interior. El producto integra DMS y OMS para cumplimiento Euro NCAP y añade funciones como Face ID, gestos y videoconferencias, con especificaciones de hasta 8MP, latencia ≤25 ms y brillo >2.250 cd/m². El anuncio es principalmente de expansión operativa y lanzamiento tecnológico, con impacto limitado para el mercado más amplio.
Analysis
This is less a demand shock than a sourcing and architecture signal. A local US footprint lowers friction for North American OEMs, but the economic value is in program wins, not in the plant opening itself; without a named OEM platform, the near-term P&L impact is likely negligible. The bigger mechanism is content consolidation: if mirror modules increasingly bundle driver/occupant monitoring, the bill of materials shifts away from standalone interior sensors and toward integrated vision platforms, while classic mirror suppliers face gradual mix pressure.
Public-market read-through is most relevant for GNTX, which owns the incumbent mirror economics, and secondarily for APTV/MBLY if OEMs prefer a single integrated cabin-vision stack. My base case is that incumbency and validation cycles make displacement slow: design-in timing is 12-24 months, and durability/cybersecurity requirements create a high switching cost. So the immediate move is probably overdone if investors extrapolate this release into rapid share loss for incumbents.
The tail risk is utilization: a local factory can become a fixed-cost drag if North American volume ramps slower than expected, especially if OEMs demand price concessions to offset domestic manufacturing. What would falsify the bullish supply-chain thesis is a lack of follow-on OEM program announcements, commentary on weak take-rate, or any evidence that digital-mirror content is being standardized into lower-margin commodity modules. Over 6-18 months, the key catalyst is not the launch, but whether YFORE announces production awards with GM/Ford/Stellantis or a large EV platform.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate event trade on YFORE; treat as a watch item until a named OEM design-win or SOP date is disclosed.
- If GNTX sells off 3-5% on this headline, buy the weakness for a 6-12 month hold; the risk/reward favors the incumbent unless share-loss data emerges.
- Use APTV/MBLY as a secondary alert basket: only fade any multiple compression if upcoming earnings do not show cabin-sensing displacement.
- Long GM/F vs short imported auto-parts suppliers on a 3-6 month horizon if this is the start of broader North American localization; thesis breaks if OEM sourcing commentary turns price-only.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- IIF CEO on Rising Global Debt