
Piramal Pharma Strengthens Future Ready Operations with 22.6% Emissions Reduction, 41% Renewable Energy and Zero USFDA OAI Observations
Source: PR Newswire
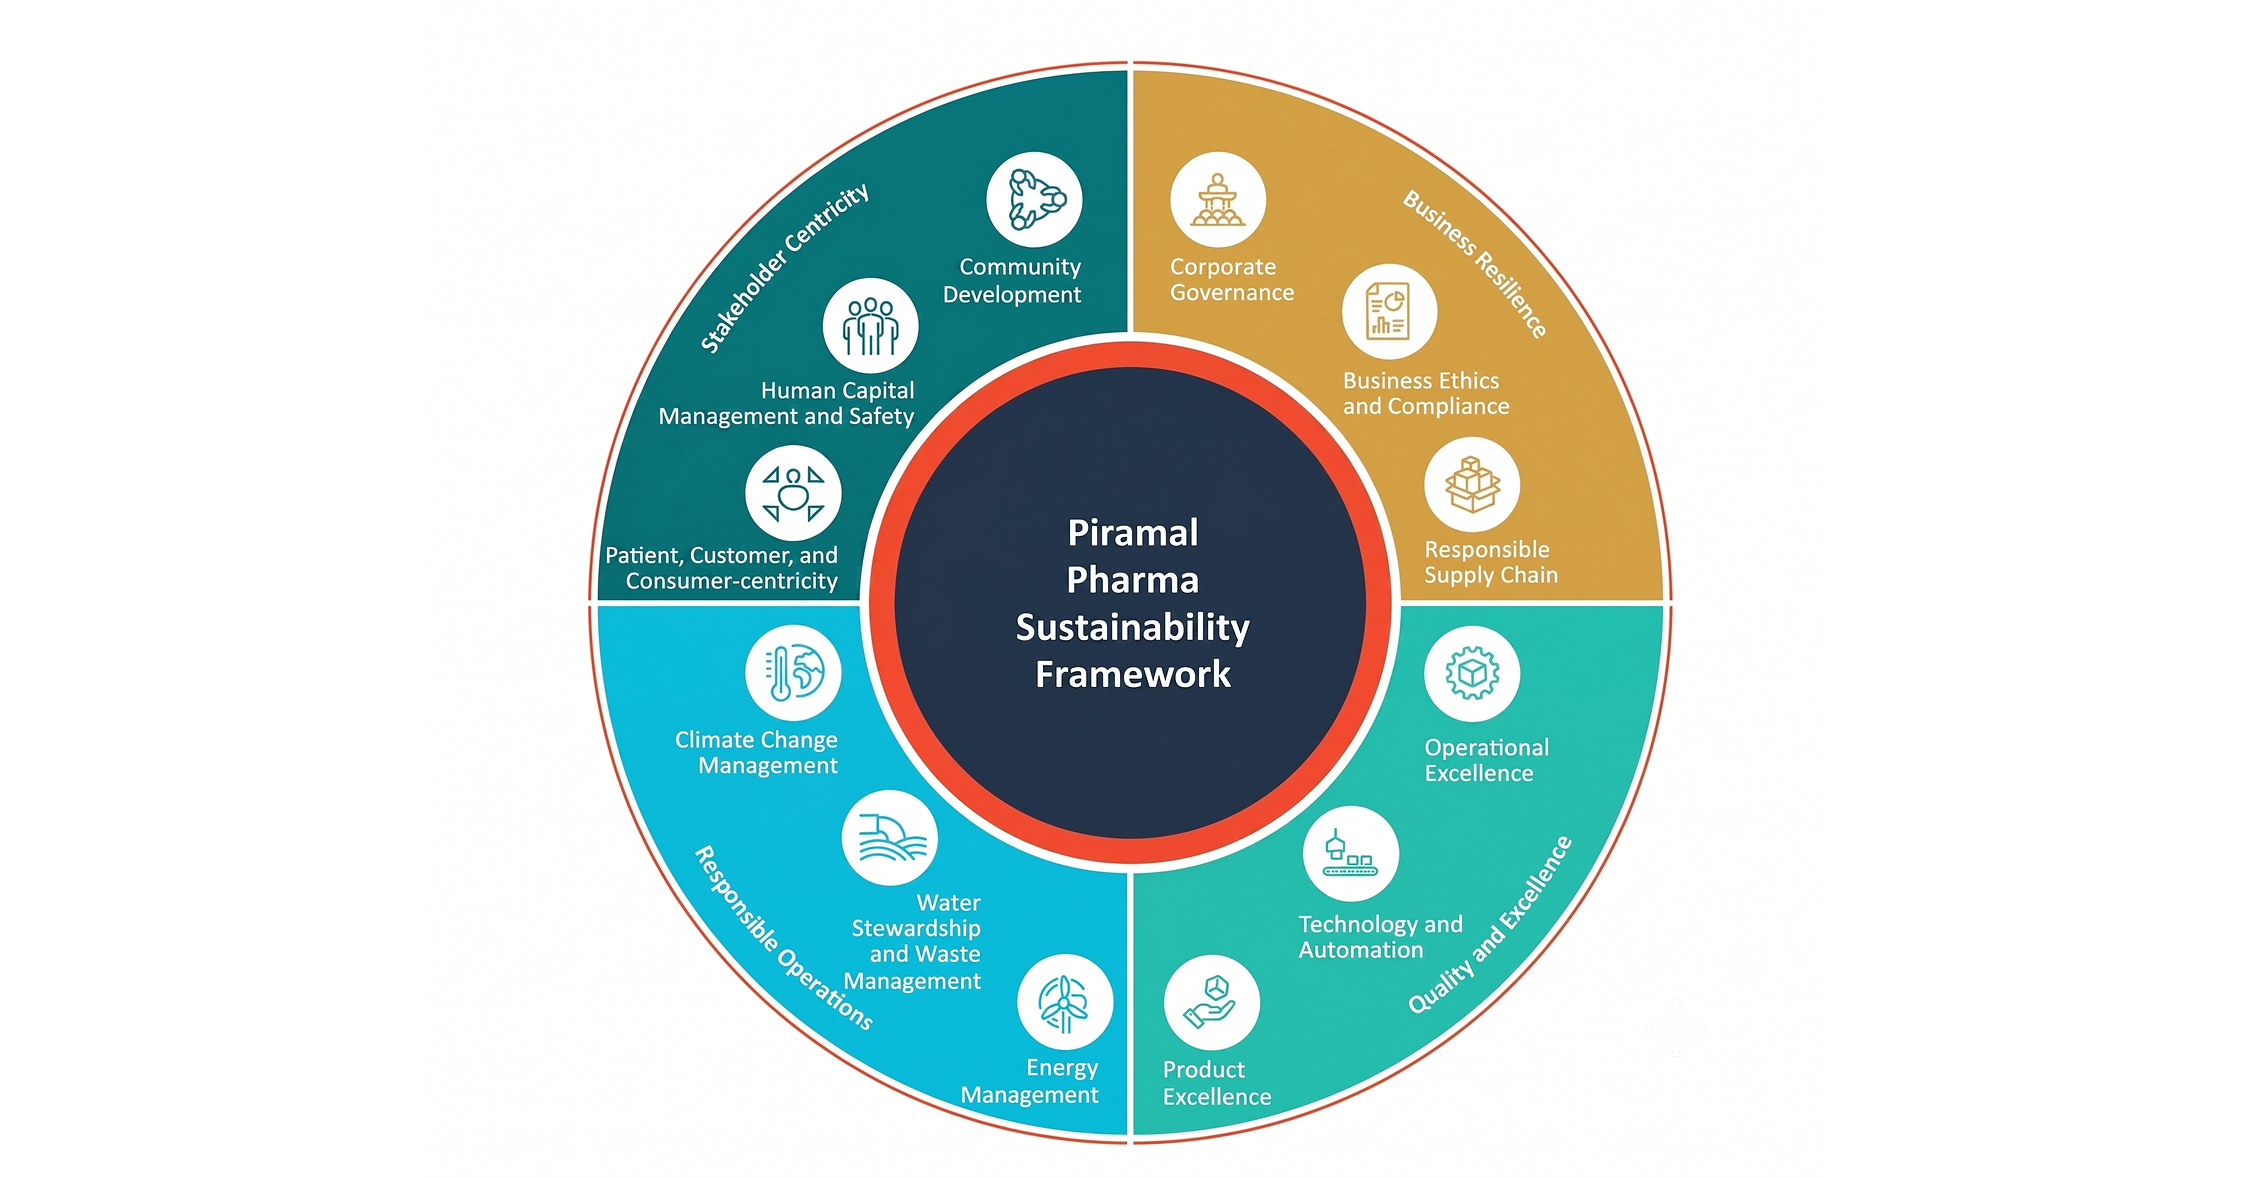
Piramal Pharma reported a 22.6% reduction in Scope 1 and 2 emissions vs the FY2022 baseline and raised renewable energy to 41% of total energy use. Operational quality metrics were strong with 38 regulatory inspections, including three USFDA inspections with zero OAI observations, alongside 209 customer audits. The company also announced a US$90 million investment to expand advanced therapeutics capabilities at its Lexington and Riverview facilities, framing progress as a “future ready” ESG and digital transformation milestone.
Analysis
The investable signal here is not the ESG score; it is the combination of clean regulatory execution and process digitization. In pharma services, a record of zero OAI outcomes matters more than emissions optics because it lowers the probability of a catastrophic compliance event that can freeze customer onboarding, delay tech transfers, and compress multiples overnight. That makes PHMMF a lower-tail-risk name relative to weaker CDMO peers, even if the sustainability report itself is not an earnings catalyst.
The $90m expansion is the real economic option, but it should be underwritten as a 12-24 month cash drag before it becomes a growth driver. Near term, depreciation, startup costs, and working-capital needs can pressure FCF unless utilization ramps quickly; the upside only shows up if the company converts compliance credibility into longer-duration, higher-complexity contracts. Second-order beneficiaries are upstream validation, lab services, and specialized packaging vendors; the losers are smaller Indian pharma/CDMO competitors with less audit resilience and less ability to pass customer quality screens.
Contrarian takeaway: consensus may overpay for the sustainability narrative while underestimating how binary regulatory cleanliness is in this segment. The market should value this less as 'green pharma' and more as a reduced-discount, higher-probability-of-fulfillment story. What would falsify it is any deterioration in the next inspection cycle, a failed customer audit, or capex that fails to translate into backlog and margin expansion by the next 2-4 quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- PHMMF: do not chase the print; only consider a tactical long on a 5-7% pullback if the stock is sold as an ESG story, with a 6-12 month target tied to evidence of backlog conversion rather than the report itself.
- PHMMF: set a hard risk trigger around the next USFDA/customer audit cycle; any Form 483/OAI or major audit issue would invalidate the lower-tail-risk thesis and should be treated as a de-risking event.
- PHMMF: monitor the $90m advanced therapeutics capex for utilization and margin payback; if EBITDA margin does not begin to inflect over the next 2-4 quarters, treat the spend as dilution to FCF rather than growth.
- Relative-value idea: long PHMMF versus a basket of lower-quality Indian CDMO/pharma services names if you can express the quality gap; the edge comes from regulatory credibility, not ESG labeling.
- No direct trade in ABBV or other unrelated pharma exposures from this release; the read-through is too indirect unless subsequent filings show material manufacturing dependence or JV expansion.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Bank of America is bullish on these top stocks ahead of earnings
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- AI's Supercharging a Scam Economy Bigger Than the Cocaine Trade
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate AI Report Writers for Financial Analysis
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements