
OrthoArizona Opens New $25 Million Orthopedic Center in Glendale
Source: PR Newswire
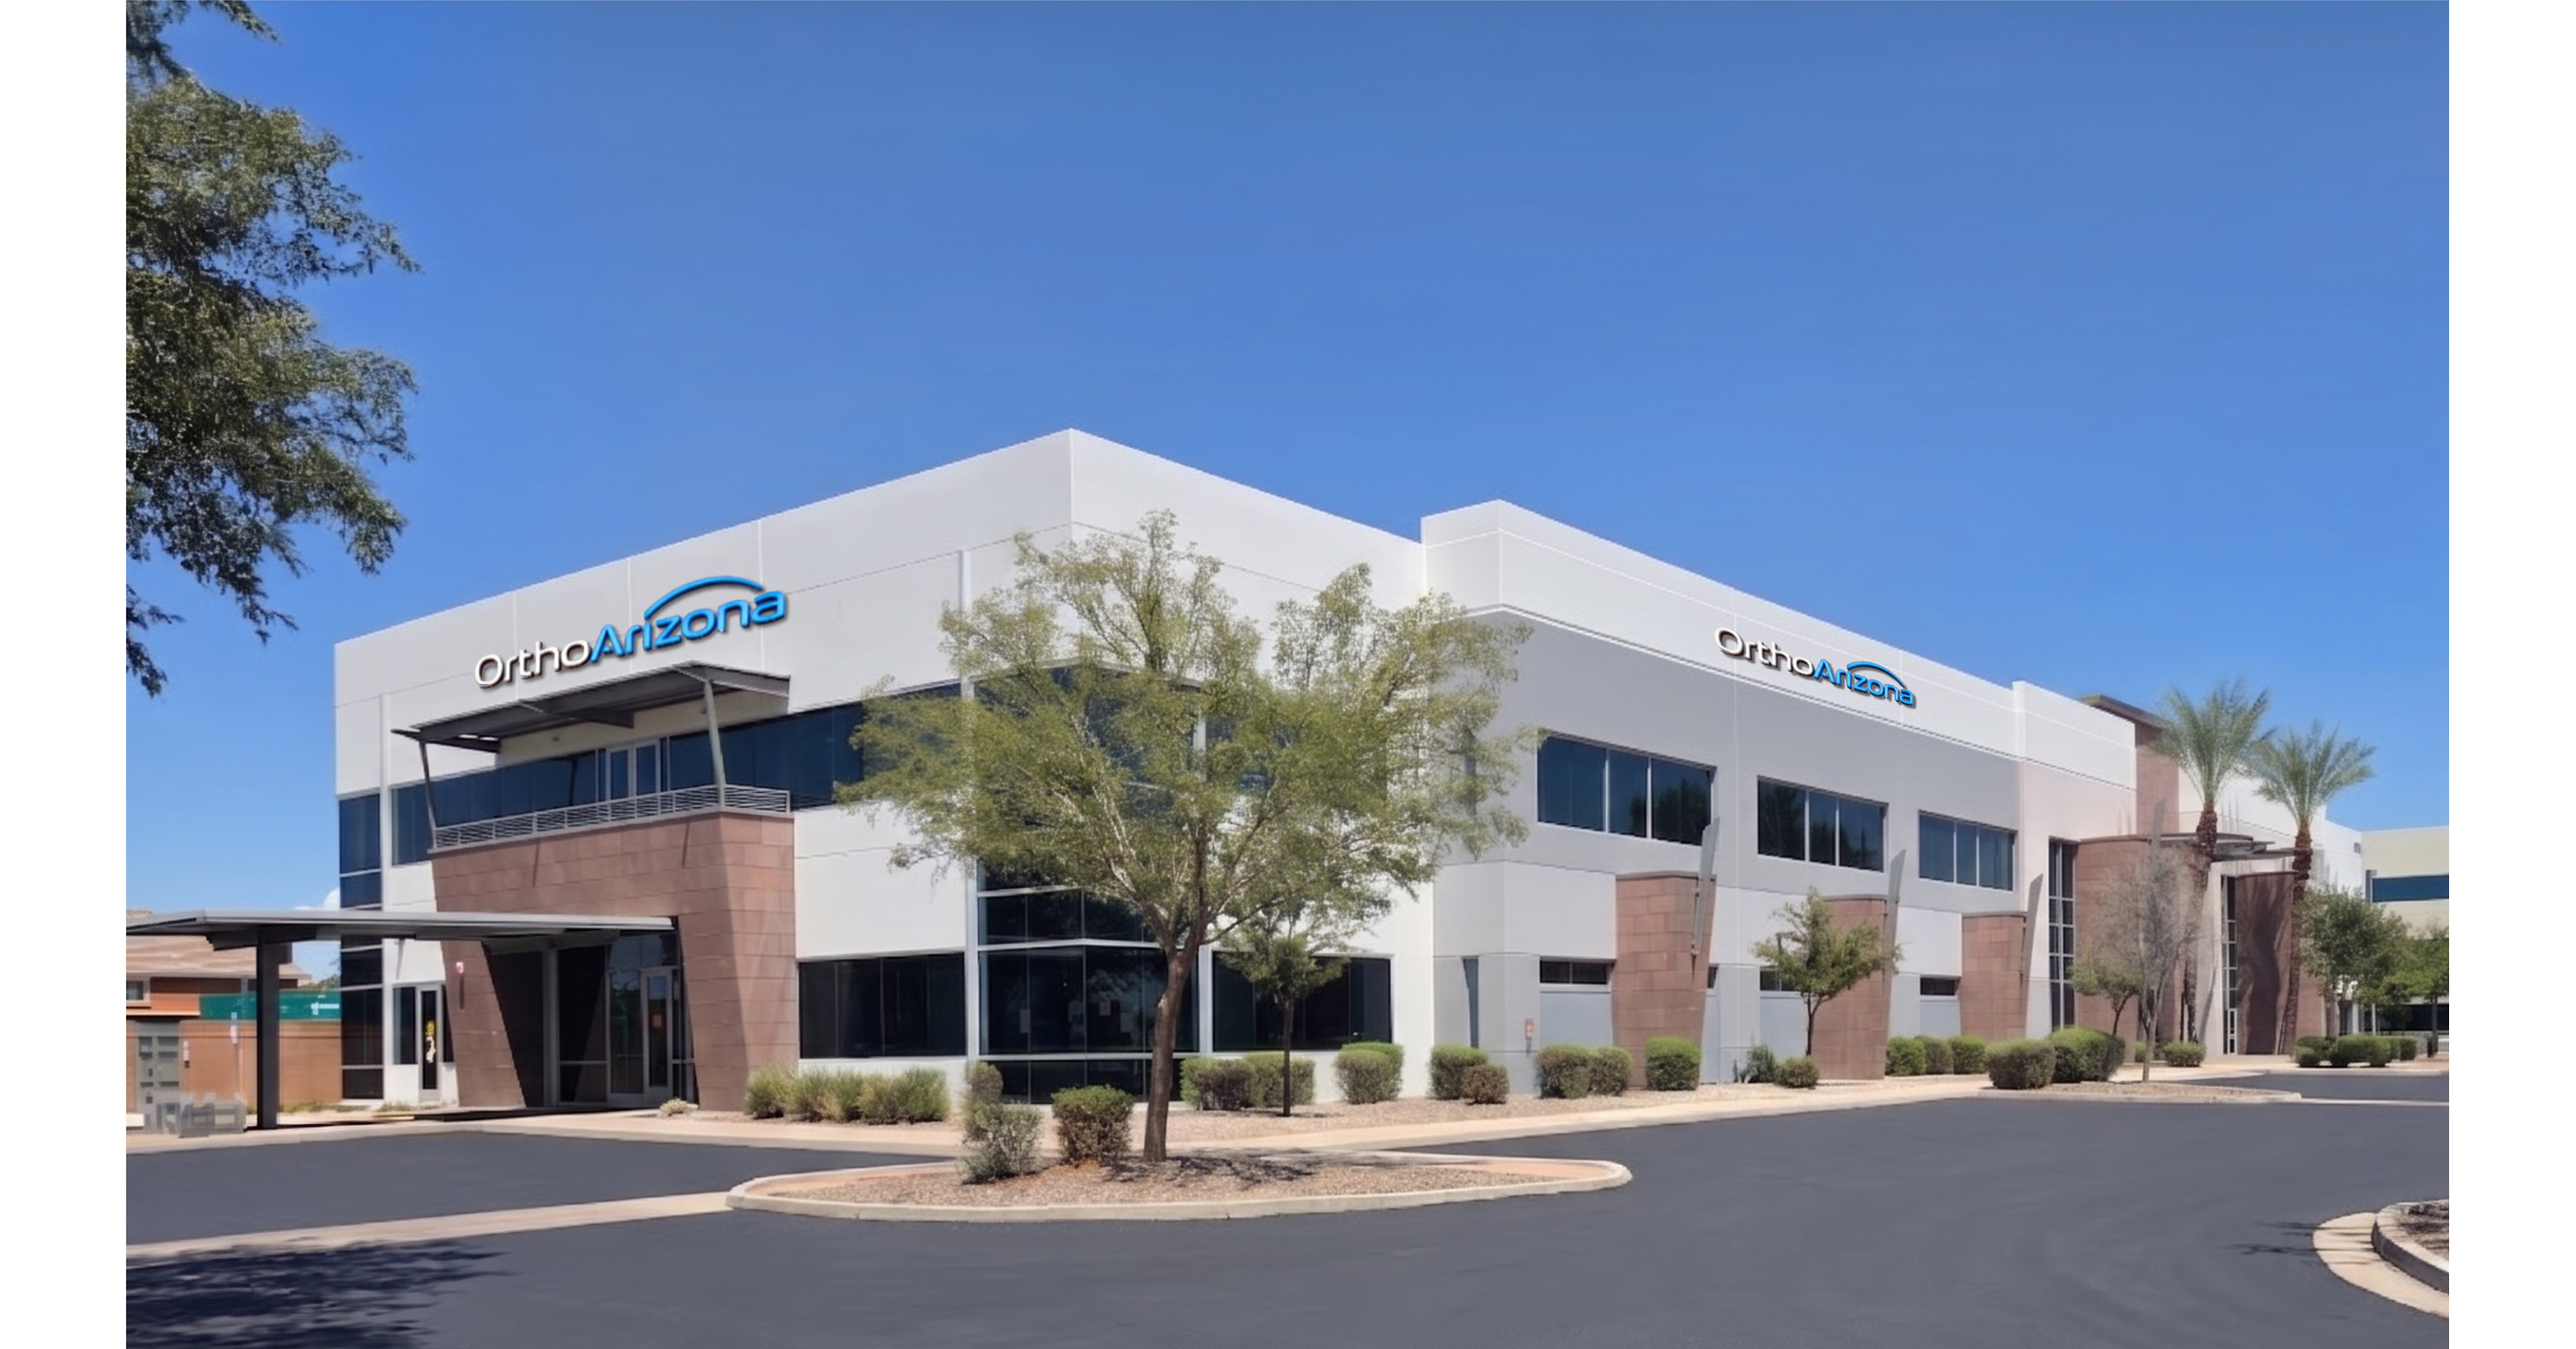
OrthoArizona opened a $25 million, 50,000-square-foot orthopedic flagship in Glendale, bundling ambulatory surgery, physical therapy, and advanced imaging (including MRI) in one location to shorten the care-to-recovery pathway. The rollout follows a broader multi-site expansion: $12.1 million committed to modernize/expand five centers and a near doubling of Deer Valley from ~12,000 to ~26,000 square feet, adding ~77,000 square feet of clinical space since CEO Rajan Bhatt took over in late 2024. With a 50,000-square-foot Chandler center slated for summer 2027, the expansion narrative is the primary positive development, though it is not likely to move public markets given the company is physician-led and not tied to major earnings numbers in the release.
Analysis
This is more a proof-of-execution signal than a market-moving event: a physician-led group is adding profitable capacity in a high-growth Sun Belt market, which usually means better throughput, higher same-day surgery mix, and less dependence on hospital outpatient departments. The economic winner is not the local real-estate story; it is any business exposed to lower-cost orthopedics, where site-of-service migration can widen margins and improve conversion from consult to procedure.
Second-order beneficiaries are orthopedic implant and procedure-enabling vendors with high share in outpatient joints and sports medicine. The cleaner public read-through is to SYK and ZBH on procedure volume durability, and to outpatient-capacity platforms such as THC/HCA only as a negative if they lose higher-margin MSK cases to physician-owned centers. The longer-term loser is the hospital system model that still relies on orthopedic procedures to subsidize broader fixed costs; one more integrated center chips away at that cross-subsidy.
The key risk is over-interpreting a single facility opening as secular demand creation. This mostly reallocates volume, so the true catalyst is payer contracting and utilization data over 1-3 quarters: if the center compresses wait times and wins commercial patients, it can shift referral patterns; if not, it is just capacity that takes time to fill. In 6-18 months, the tell will be whether local hospital MSK admissions or outpatient procedure mix decelerate.
Contrarian view: the consensus may be too focused on growth and not enough on reimbursement pressure. More outpatient orthopedics can help margins only if commercial rates hold; a CMS or payer push toward narrower facility-fee differentials would cap the upside. Until utilization data proves otherwise, this is a watch item, not an obvious buy-the-news setup.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Watchlist, not a trade: monitor SYK and ZBH for any follow-through in outpatient procedure commentary over the next 1-2 quarters; if management cites stronger ambulatory joint volumes, the thesis is that site-of-care migration is accelerating.
- Small tactical long on IHI or a basket of orthopedic enablers vs. a hospital-heavy basket for 3-6 months only if Arizona/MSK utilization data confirms share shift; upside is modest, but downside is limited because the article signals capacity discipline, not demand softness.
- Avoid using HCA or THC as an immediate short solely on this news; wait for evidence of case migration in local volume reports or utilization metrics, because a single regional center is too small to justify a high-conviction short.
- Set an alert for payer/reimbursement headlines and outpatient surgery mix: if commercial reimbursement weakens or CMS site-neutral policy tightens, the outpatient MSK expansion narrative loses traction and the trade should be exited quickly.
More News
- State Street Q3: Another Strong Quarter, But Macro Tailwinds May Be Fading
- Christine Lagarde: IMFC Statement
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'