
Kensington Returns to Cboe to Celebrate Launch of Kensington Premium Opportunities ETF (KPO) and Growing ETF Platform
Source: Newswire
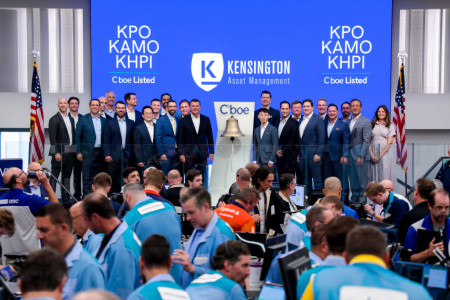
Kensington Asset Management launched the actively managed Kensington Premium Opportunities ETF (KPO), its third ETF strategy, using derivatives for equity exposure while investing collateral in U.S. Treasuries and ultra-short bond ETFs. The launch follows growth in Kensington's existing ETF platform: KHPI has reached approximately $420 million in AUM since its September 2024 debut, while KAMO surpassed $100 million within just over six months of its December 2025 launch. KPO targets capital-efficient equity participation and income generation but carries options, leverage, hedging, liquidity and potential principal-loss risks.
Analysis
This is not a material earnings catalyst for CBOE: a single small issuer listing contributes de minimis transaction, market-data, and issuer-fee revenue relative to CBOE's derivatives franchise. The more relevant read-through is incremental evidence that ETF sponsors are packaging options-based, capital-efficient equity exposure for advisors, which modestly expands the long-run addressable market for listed index and equity options. That demand is more favorable for CBOE than for exchange peers with less concentrated exposure to U.S. options activity, but the effect is measured in years rather than quarters.
KPO's economic proposition is highly regime-dependent. Treasury collateral can subsidize the cost of synthetic equity exposure while front-end yields remain elevated, but that advantage compresses as policy rates decline; meanwhile, systematic put-spread hedges typically create a visible performance drag in calm, rising markets and leave meaningful gap risk outside their protected range. The key commercial risk is not equity beta but whether advisor demand persists after comparing realized returns, distributions, fees, and drawdowns against simpler substitutes such as SPY plus SGOV, buffered ETFs, or defined-outcome products from Innovator and First Trust.
Contrarian view: rapid initial asset gathering in a sponsor's prior products is not sufficient evidence of durable franchise value. Small active ETFs can accumulate seed and platform allocations quickly but face sharp redemption risk after a hedge fails during a volatility shock or after distributions fall with short rates. Treat this as a structural monitor for options-market participation, not a signal to underwrite near-term CBOE revenue growth absent evidence of sustained fund flows and a corresponding pickup in listed-options open interest.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in CBOE on this announcement; the implied revenue contribution is immaterial. Maintain CBOE exposure only on broader options-volume, index-licensing, and capital-return thesis rather than ETF-listing news.
- Set a 1-3 month monitor for KPO net creations, assets under management, bid/ask spreads, and disclosed options notional. Upgrade the read-through for CBOE only if the fund reaches meaningful scale and options open interest/volume rises in the relevant underlying exposures; do not infer this from launch publicity.
- For portfolios seeking the stated exposure, compare KPO's realized total return and maximum drawdown against a transparent SPY/SGOV combination over at least one volatility event before allocating. A decline in front-end Treasury yields of roughly 100 bp would materially reduce the collateral-income tailwind and is a thesis-falsification trigger for the product's relative appeal.
- Watch VIX above 30 or a rapid equity selloff as the first real stress test. If KPO's hedging structure shows losses materially worse than its expected protection profile, expect advisor-flow risk across smaller active options ETFs; that would be negative for niche issuers but not, by itself, a short catalyst for CBOE.
More News
- Fed hikes again - an AI-Picked insurer is still cashing in
- Bizarre volatility bet in the options pits is a head scratcher ahead of Fed rate decision
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- Berkshire may boost holdings in Japan’s trading houses- Bloomberg
- Bond Traders Are Convinced the Fed Will Hike Interest Rates