
THE FUTURE OF CPG LAUNCHES ISN'T ANOTHER FLAVOR -- IT'S FANDOM: BELLIWELLI BRINGS ITS BRAND-BUILDING PLAYBOOK TO 3,120 WALMART STORES
Source: PR Newswire
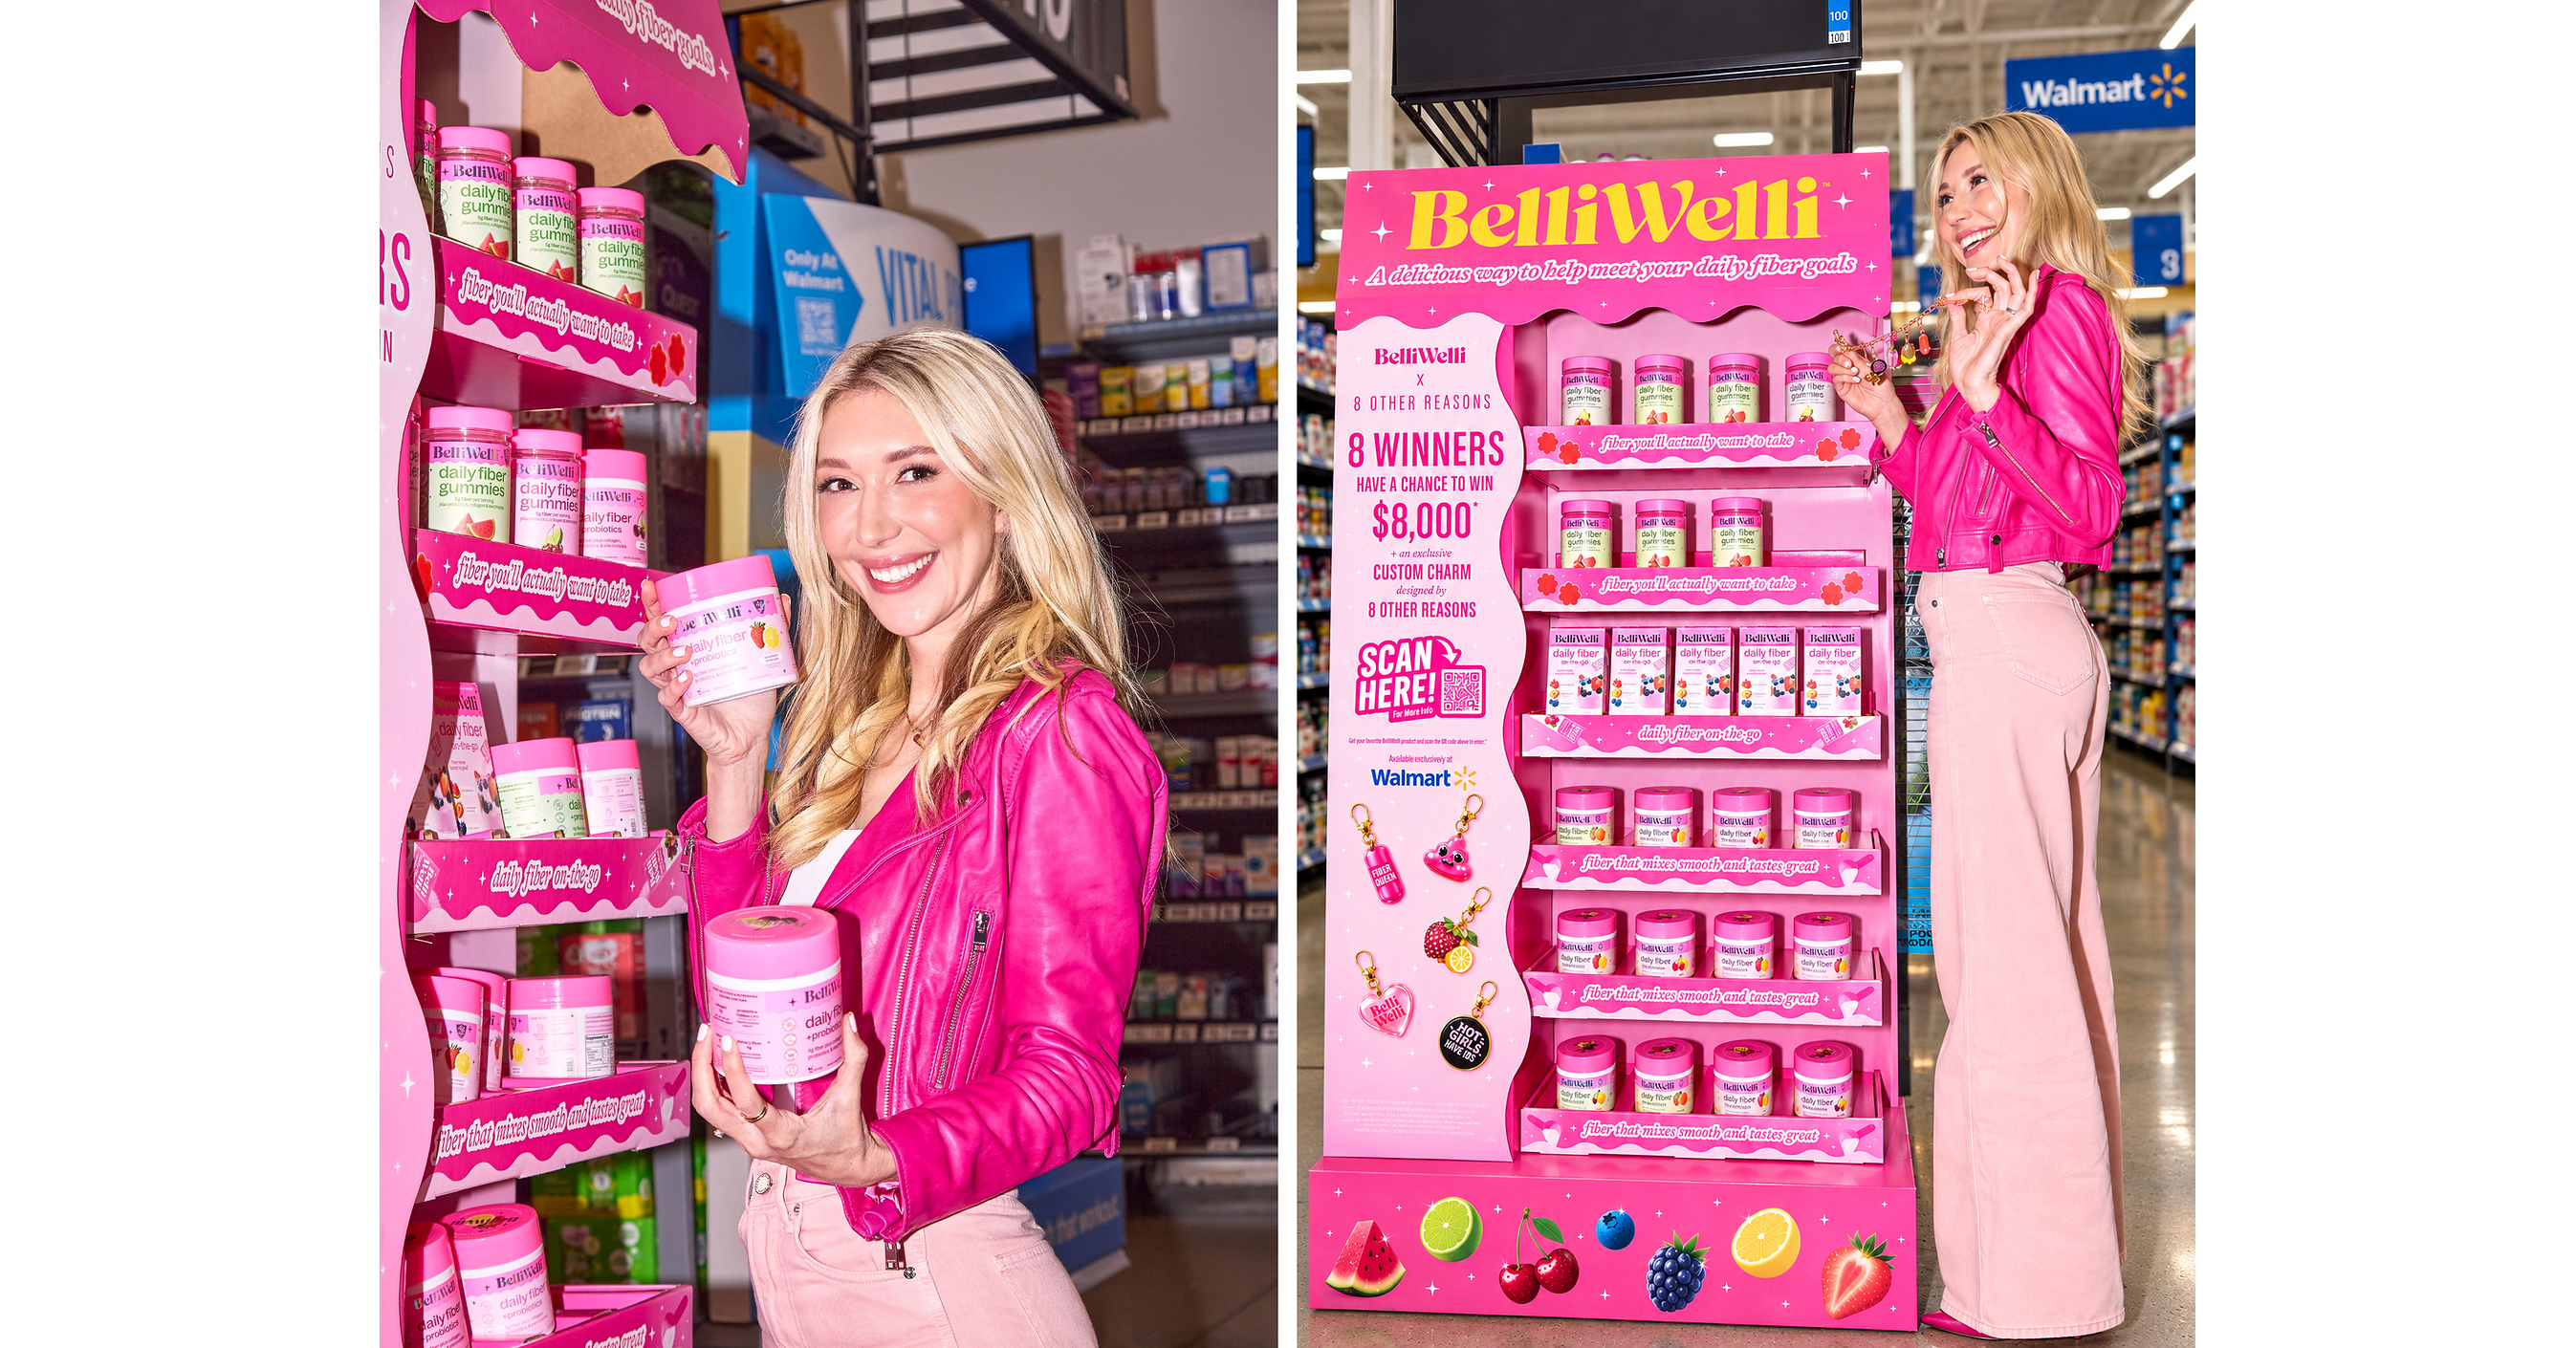
BelliWelli is expanding its largest Walmart endcap program to 3,120 stores by September 26, supplementing nationwide distribution with an $64,400 consumer sweepstakes and an 8 Other Reasons collaboration. The company says it is Walmart's fastest-growing fiber brand based on 13-week POS data through July 11, 2026, while 77.6% of its shoppers had not previously purchased fiber in the 12 months ended December 31, 2025. The initiative aims to convert heightened consumer interest in fiber into broader category penetration and brand engagement at mass-retail scale.
Analysis
This is immaterial to WMT earnings but modestly positive for its higher-velocity, trend-led wellness assortment strategy. The relevant read-through is whether incremental shelf visibility converts category entrants into repeat purchasers: new-to-fiber buyers can expand basket size and trip frequency, but only if replenishment holds after promotional displays are removed. For WMT, the upside is primarily mix and traffic perception rather than a measurable gross-profit catalyst; a single emerging-brand endcap program will not alter FY27 guidance.
The larger competitive implication is for legacy fiber brands whose demand has relied on need-state purchasing and shelf familiarity rather than social discovery. P&G's Metamucil franchise and Kenvue's digestive-health portfolio face a gradual risk that younger consumers enter the category through branded gummies/powders, shifting the category toward higher marketing spend and lower loyalty to traditional formats. That said, the campaign's claimed momentum is company-supplied and does not establish repeat rates, velocity per store, or retailer margin economics—the data that determine whether Walmart expands permanent facings after the display period.
Near term, the only investable signal is Walmart's category-management follow-through over the next 1-3 months: additional facings, online search placement, and broader functional-snacking resets would validate that mass retail sees digestive wellness as a scalable traffic category. The contrarian view is that social-led category trial can be highly promotional and cannibalize adjacent snack purchases rather than create durable fiber demand; a weak post-display velocity reset would favor incumbents with established repeat behavior. Over 6-18 months, the structural beneficiary is likely Walmart if it can use emerging brands to refresh wellness assortment without sacrificing private-label penetration or margin discipline.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No standalone WMT trade: the expected revenue and EBIT contribution is de minimis relative to Walmart's scale, and the announcement lacks independently verifiable sales, repeat-rate, or margin data.
- Maintain any existing WMT long only on broader traffic, grocery-share, and advertising-margin thesis; use the October-November post-promotion period as a channel-check window rather than a catalyst trade. A broader wellness-assortment thesis is weakened if endcap extensions and digital placement do not materialize after the campaign.
- Monitor P&G for evidence of rising promotional intensity or slowing U.S. digestive-wellness sell-through in the next two quarterly reports. Do not short on this item alone; a tradeable legacy-brand disruption thesis requires confirmed category share loss or incremental marketing-spend pressure.
- Set an alert for Walmart functional-wellness category resets in 1H 2027. A broader rollout of challenger fiber, hydration, and protein brands could support a modest WMT multiple premium through improved discretionary basket mix, while a retreat to temporary displays would indicate the trend is not converting into durable shelf economics.
More News
- Meta's 'powerful breakout' sets up a unique trading strategy, says Mike Khouw
- Costco receives $184M in tariff refunds, says most will go toward lower prices
- 3 Nuclear Stocks Powering the Grid Long Before AI Made Them Trendy
- Can you get a personal loan without a credit check?
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Facebook found liable as TikTok settles for $100m over user safety
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate AI Report Writers for Financial Analysis
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements