
China Arbitration Summit 2026 & China High-level Dialogue on Maritime and Commercial Arbitration Successfully Held in Beijing
Source: PR Newswire
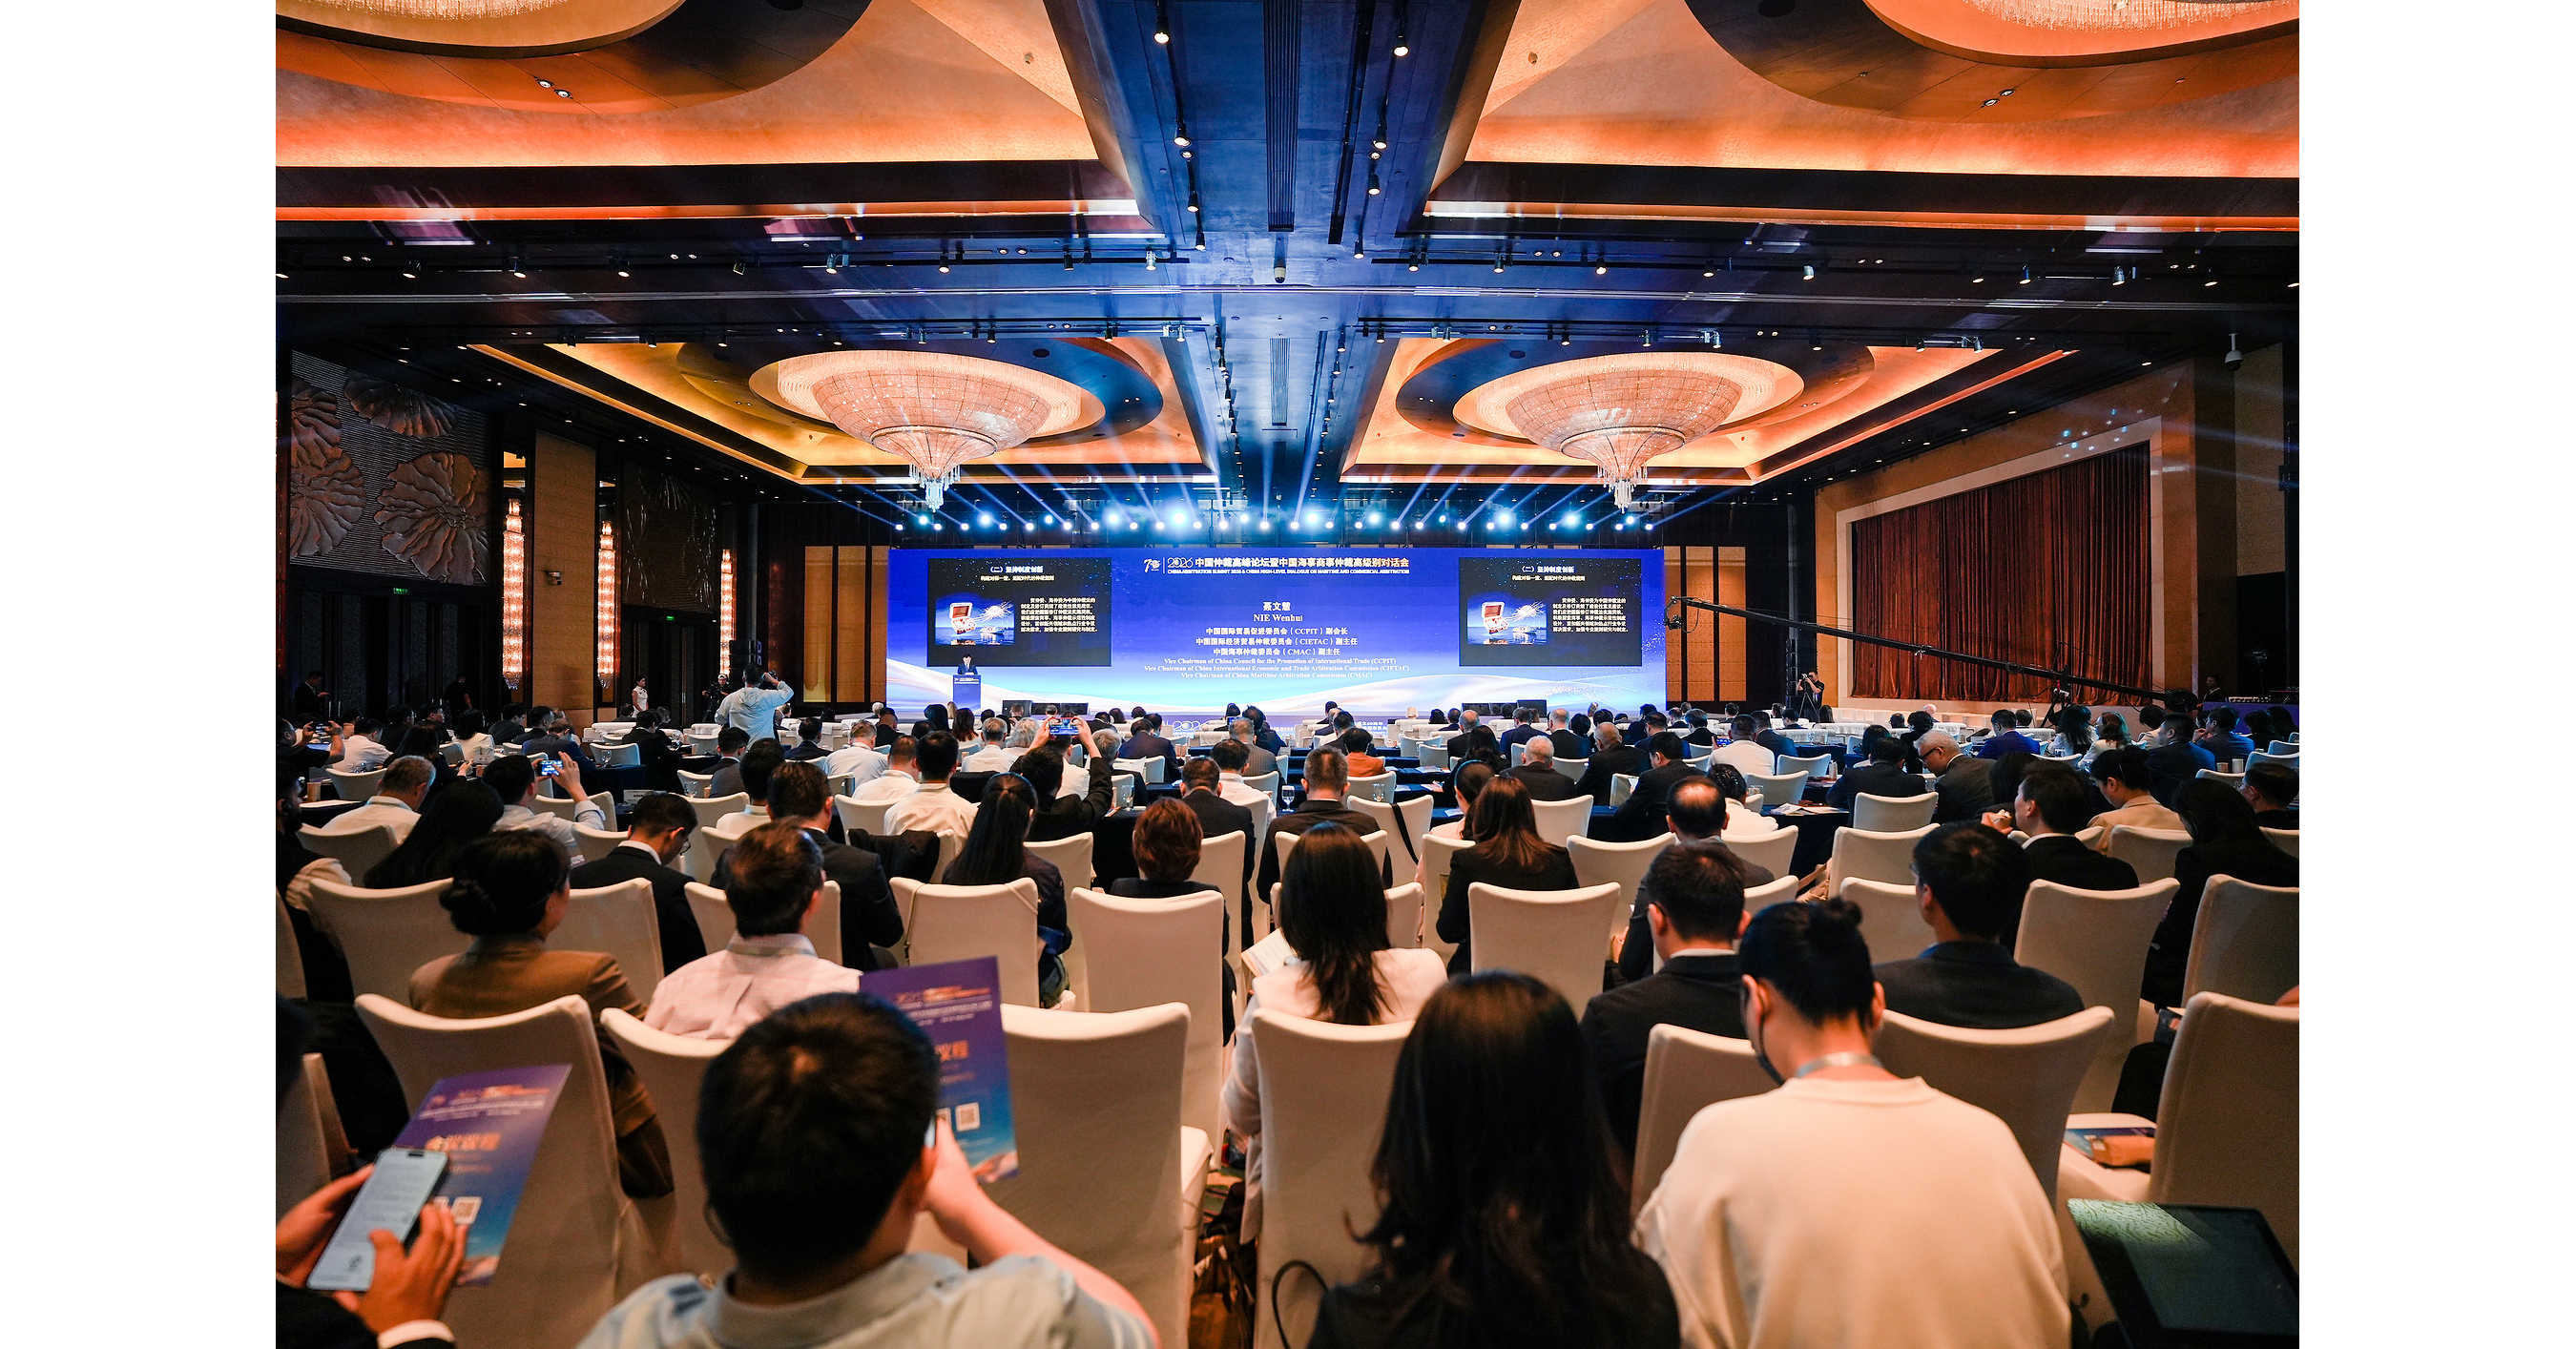
The China Arbitration Summit 2026 convened nearly 390 in-person representatives from 41 countries and regions, alongside online viewership exceeding 5.14 million across 55 countries and regions. CIETAC released 12 Belt and Road arbitration case studies spanning mining, rail transit, port trade, energy infrastructure and engineering, and signed cooperation agreements with institutions in Africa, Kyrgyzstan and Vietnam. The event highlighted Chinese judicial support for arbitration and discussion of technology issues including electronic awards and AI in arbitration, but carries no material near-term market implication.
Analysis
This is not a standalone earnings or valuation catalyst. The investable signal is a gradual reduction in cross-border contract-enforcement friction for China-linked infrastructure, shipping, and project-finance activity—if cooperation converts into faster award recognition and enforceability rather than remaining a conference-level initiative. Any benefit would accrue over 6-18 months through lower contingency reserves, reduced working-capital lockup, and potentially narrower risk premiums on overseas projects, not through near-term revenue acceleration.
The most exposed beneficiaries are Chinese EPC and infrastructure exporters with meaningful emerging-market receivables—China Railway Construction (1186 HK), China Railway Group (390 HK), Power Construction Corp. of China (601669 CH), and China Communications Construction (1800 HK)—alongside port/shipping operators such as COSCO Shipping Holdings (1919 HK). Improved dispute-resolution credibility could modestly improve bid economics and cash-conversion assumptions in Belt-and-Road corridors; conversely, it reduces an advantage held by firms that price projects with unusually high legal-risk buffers. The key second-order risk is that more standardized arbitration also makes it easier for counterparties and lenders to pursue claims against Chinese contractors, exposing historically opaque project-loss provisions.
Consensus should not capitalize this development into valuation multiples before evidence emerges. The relevant proof points over the next 1-3 months are published enforcement decisions, case-duration data, adoption of electronic-award protocols, and disclosed settlement/collection outcomes; absent these, the market impact is effectively zero. A deterioration in bilateral trade relations, sovereign-payment stress in frontier markets, or non-enforcement of a prominent award would overwhelm any institutional-progress narrative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Key Decisions for Investors
- No directional trade on this item alone; treat it as a 6-18 month watch catalyst rather than a near-term signal.
- Add 1186 HK, 390 HK, 601669 CH, 1800 HK, and 1919 HK to an event-monitoring basket; reassess only if upcoming results show declining contract-asset days, lower impairment provisions, or improved overseas-project cash collection.
- For existing long exposure to Chinese EPCs, monitor overseas receivable impairment and provisions versus guidance as the falsification metric; any material increase would negate the proposed enforcement benefit regardless of policy messaging.
- Do not buy AI/legal-technology proxies solely on references to electronic awards or AI arbitration: there is no disclosed procurement, monetization path, or identifiable listed beneficiary.
More News
- Chinese biopharma stocks jump as U.S. weighs keeping door open to drug deals
- Oil falls as crude flows remain 'surprisingly strong'
- Trump & Xi to Meet Amidst Friction on Wars, Tech, Trade
- Here are the 3 big things we're watching in the stock market this week
- Tech leads shares higher in Asia, oil eases
- Yuan hits fresh multi-year peak as PBOC eases curb ahead of Trump-Xi summit