
Micron: This Memory Cycle Could End Differently
Source: seekingalpha.com
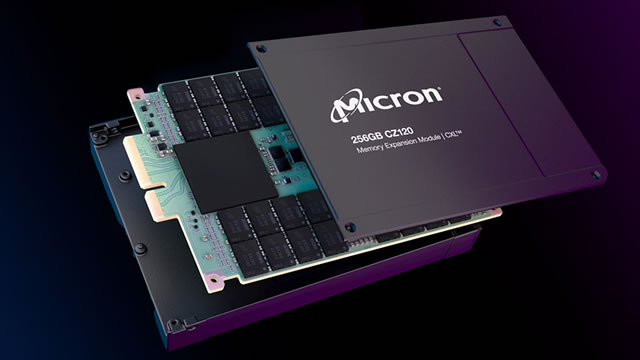
Micron is separating cleanroom construction from equipment deployment to expand capacity gradually as contracted demand becomes clearer. More than 75% of FY2027 output is already committed, improving visibility for long-term capacity allocation. At roughly $1,064 per share, MU trades near 6x FY2027 EPS, despite consensus already assuming a severe future earnings normalization.
Analysis
The investment case is less about headline capacity growth than the option value of delaying tool installation: Micron can preserve future capacity while limiting the risk of adding depreciating equipment before demand and pricing are sufficiently visible. If this discipline holds, it could reduce the severity of the next memory downturn and support a higher through-cycle valuation. It does not remove memory’s key risk: committed volumes may not lock in attractive prices, and customer demand can shift across product types.
Near term, staged tool deployment could defer or make equipment orders lumpier, a potential headwind for semiconductor-equipment suppliers; the benefit to Micron’s cleanroom contractors is less certain and may already be reflected in project timing. Over 1–3 months, watch Micron’s capex/tool-installation plans, contract duration and pricing terms, and updates to HBM and conventional DRAM demand. Over 6–18 months, disciplined industry supply would support memory pricing, but competitors’ capacity decisions remain the swing factor.
The contrarian risk is that a low forward earnings multiple can still be a value trap if the earnings denominator reflects unusually strong memory pricing. The bullish case is stronger if contracted demand is binding and economically attractive, not merely volume-indicated. Falsify it if Micron’s guidance or estimates fall alongside weakening memory prices, or if it resumes aggressive equipment deployment ahead of durable demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Favor a measured long MU over an unhedged, full-size cyclical bet: scale in around evidence that contracted demand supports pricing as well as volume. The upside is lower expected capex overshoot and better earnings durability; the downside is rapid estimate compression if memory prices roll over.
- Before adding, verify the commitment terms (duration, cancellation flexibility, price linkage, and product mix) and whether FY2027 EPS assumptions rely on peak-like pricing. Treat the stated forward multiple as conditional, not a valuation floor.
- Monitor Micron’s equipment-installation and capex updates over the next 1–3 months. A disciplined deployment path supports the thesis; accelerated tool orders without corresponding demand evidence weakens it and may also improve the relative outlook for equipment suppliers.
- Track Samsung and SK Hynix capacity plans alongside DRAM/HBM pricing. Competitor-led supply expansion could erase the benefit of Micron’s restraint; sustained pricing alongside controlled industry additions would validate the 6–18-month thesis.
More News
- Memory stocks have hit a malaise. Jay Woods believes it's a buying opportunity
- Nvidia and Micron shares bounce as investors get clarity on a key OpenAI matter
- Nasdaq, SPX Look to End Record-Filled Week With Gains
- Micron Has Evolved Into a Next Gen Player So I Keep Adding
- Micron: Bears Are Fighting Physics With Spreadsheets
- Jim Cramer Has a Warning for Anyone Betting Against Micron Stock. Michael Burry Isn't Listening.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework