
Avelo Airlines Extends Flight Schedule Through April 20, 2027
Source: PR Newswire
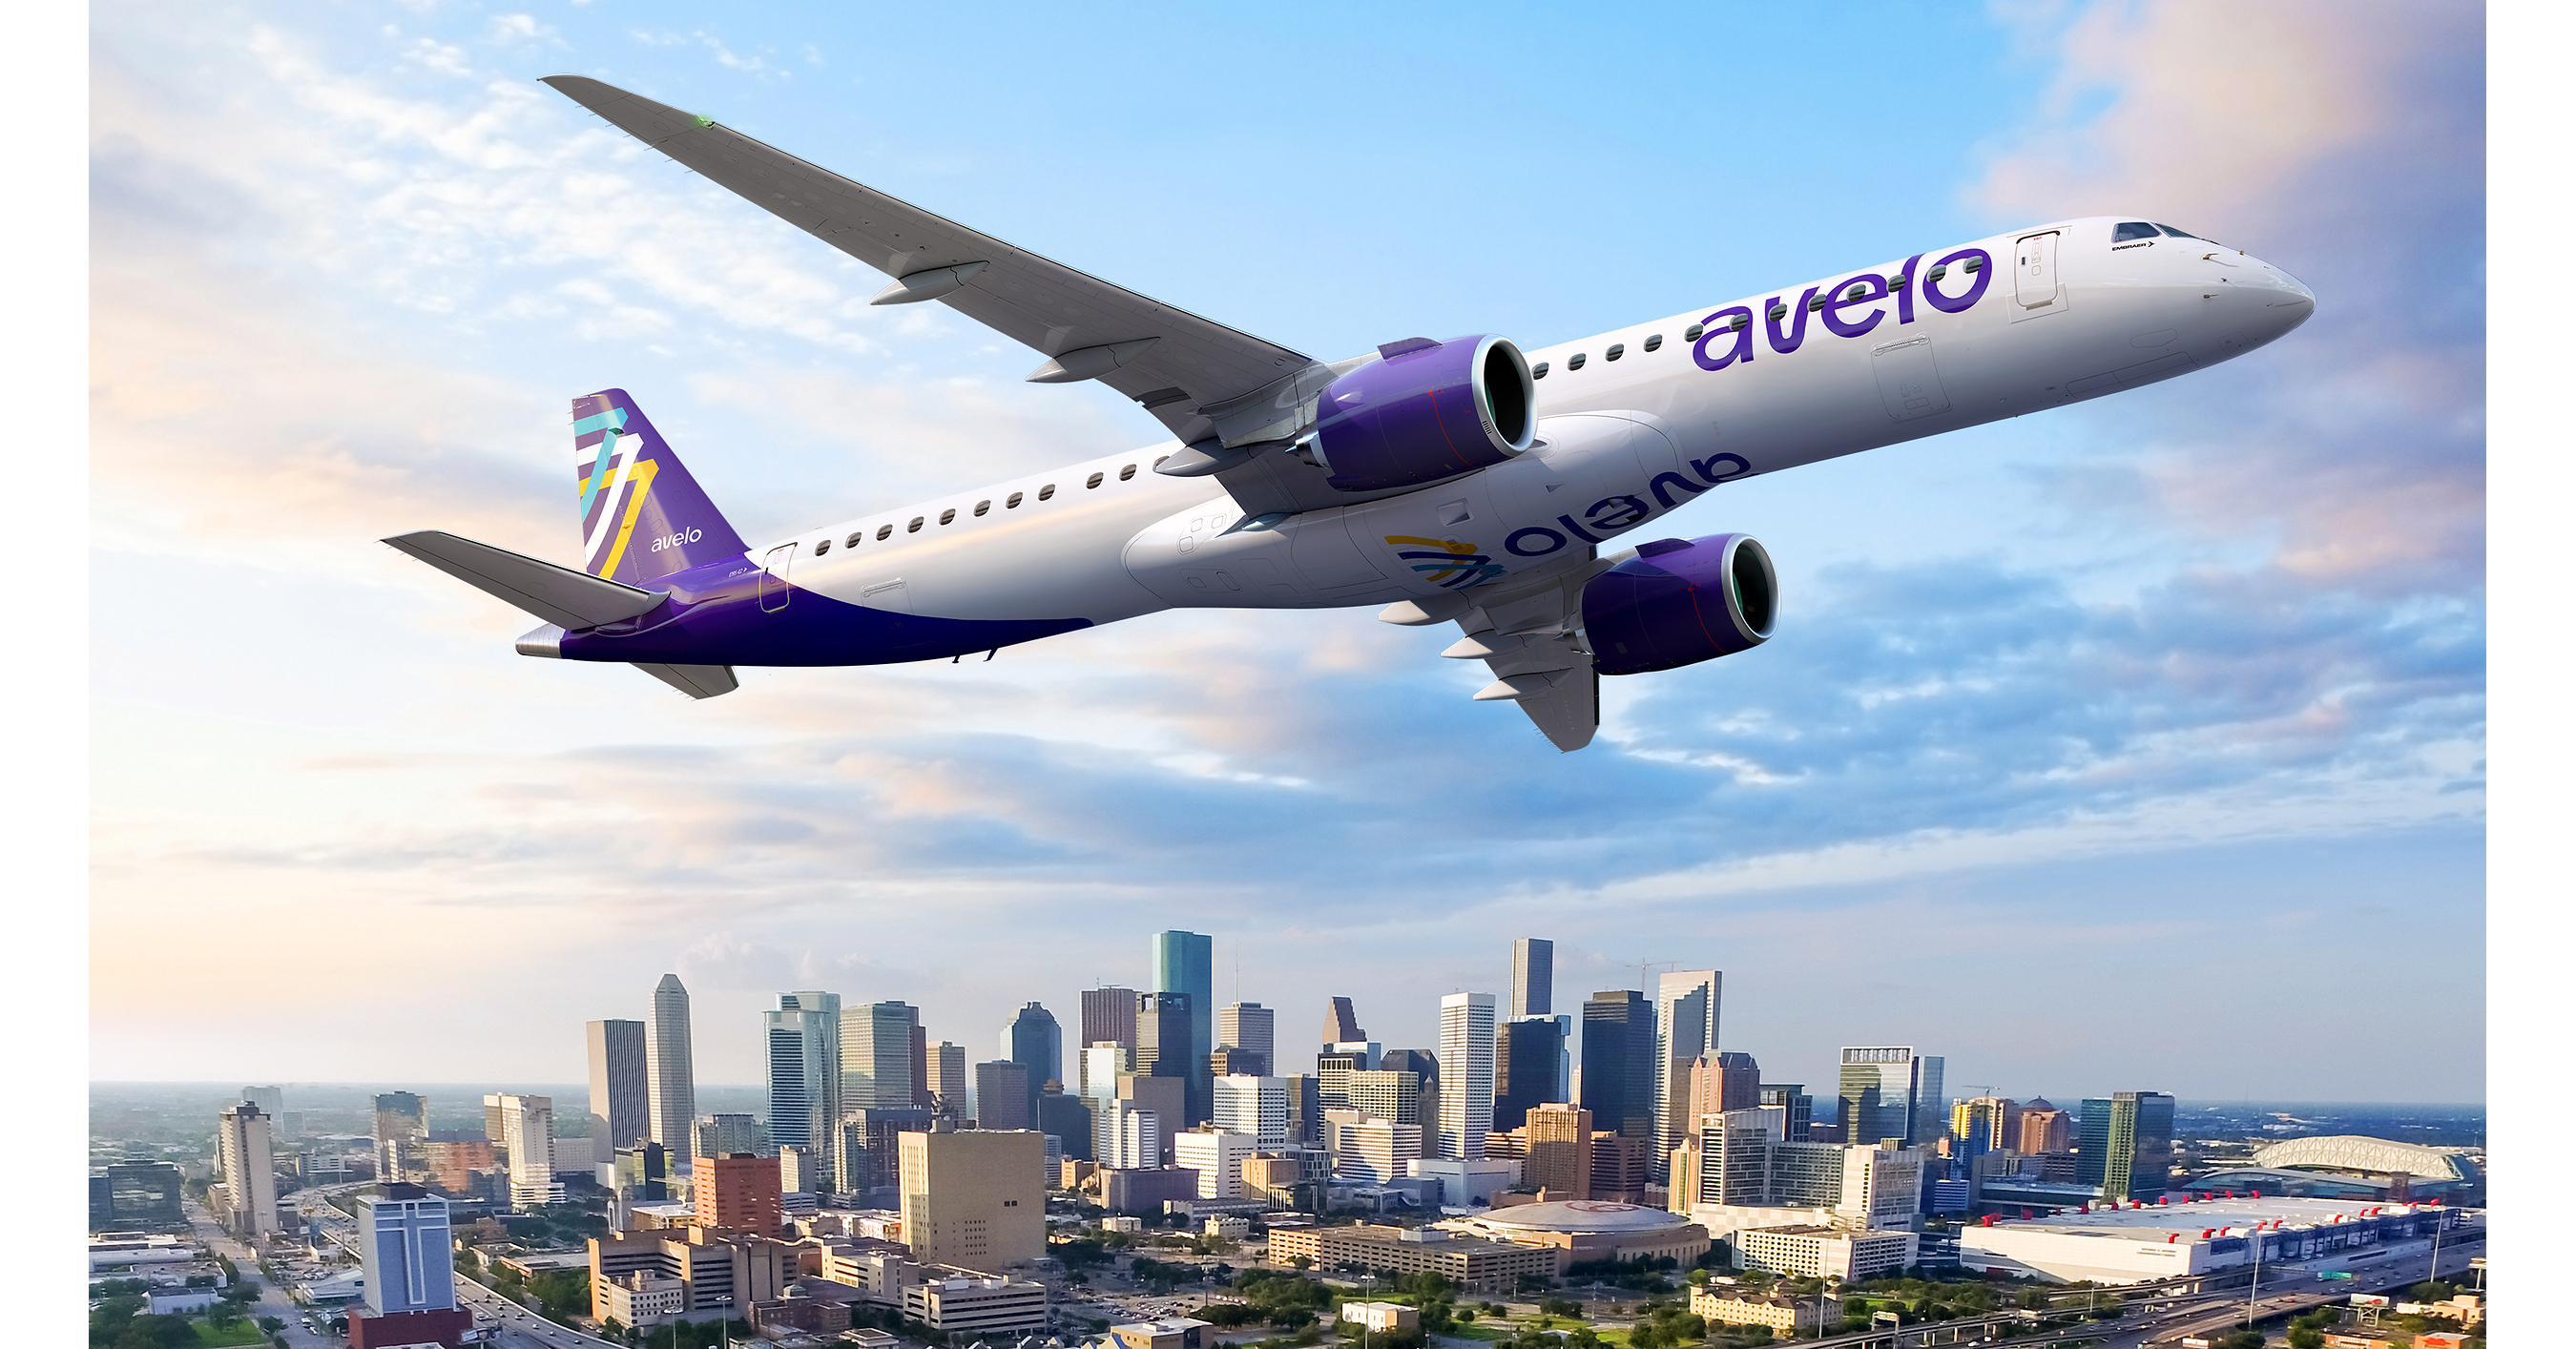
Avelo Airlines extended its flight schedule through April 20, 2027 and added/expanded booking across 35+ destinations. One-way fares start at $42 (taxes/fees included), with limited seats/days and booking due by Sept. 9, 2026. The update is mainly customer-marketing focused (new timetable and promotional pricing) with limited direct implications for broader markets.
Analysis
This reads more like a booking/working-capital signal than a true capacity shock. The economically relevant piece for BA is not this quarter’s schedule extension but the implied need for aircraft availability over time; until that converts into firm E195-E2 delivery milestones or additional narrowbody orders, the impact on Boeing’s model is immaterial. MA’s upside is also limited: a co-branded travel card can add high-margin payment volume, but most economics sit with the issuer and the airline, not the network.
The second-order loser set is the leisure fare complex around secondary airports. A carrier that keeps opening the booking window at very low advertised fares usually forces incumbents to defend load factors first, then yields, then ancillary pricing. That matters more for route-level competitors than for the airline itself: the real pressure shows up in discounting, not headline capacity. Over 1-3 months, watch whether spring bookings hold without deeper promo intensity; if not, this is inventory pre-selling, not durable demand gain.
Contrarian view: the market can over-interpret “affordable fares” as market-share expansion when it may simply reflect a need to lock cash in early. For small carriers, extending the schedule often improves liquidity and visibility, but it can also be a tell that management wants to monetize seats before demand weakens. The structural tell over 6-18 months will be whether the network moves into higher-yield traffic or remains a leisure-only, low-margin franchise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade in BA on this release; treat it as a watch item until Avelo converts the long-dated schedule into firm aircraft deliveries, deposits, or higher-order commentary in Boeing’s next update.
- If spring booking data shows deeper discounting or load-factor deterioration, consider a tactical short in JETS versus a market neutral basket of travel cyclicals; the risk/reward only improves if pricing pressure becomes visible in peers, not from this PR alone.
- Watch MA only as a conditional beneficiary of co-brand spend growth; go long only if there is evidence of meaningful card activation or spend-per-account, since the current signal is too small to move earnings.
- Use this as an alert for leisure-route incumbents rather than Avelo itself: if route-level fare compression appears in coming weeks, short the most exposed airline names or the airline ETF on a 1-3 month horizon.
- Contrarian setup: if the stock market starts pricing this as a growth-positive story, fade the move unless subsequent data confirm higher-yield mix and sustained bookings; absent that, the more likely outcome is margin pressure rather than durable expansion.
More News
- Move Over, Archer and Joby: This Embraer-Backed eVTOL Stock Deserves Your Attention
- Berkshire Hathaway and Mastercard Don't Need AI to Keep Growing. Both Look Worth Owning Through 2030.
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Bank of America is bullish on these top stocks ahead of earnings
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Advanced Search Filters, Redesigned Ticker Dashboard, and Improved Search Experience
- How to Build an Automated Research Process for a Fund