
CHIPOTLE ARRIVES IN ASIA WITH FIRST RESTAURANT IN SEOUL
Source: PR Newswire
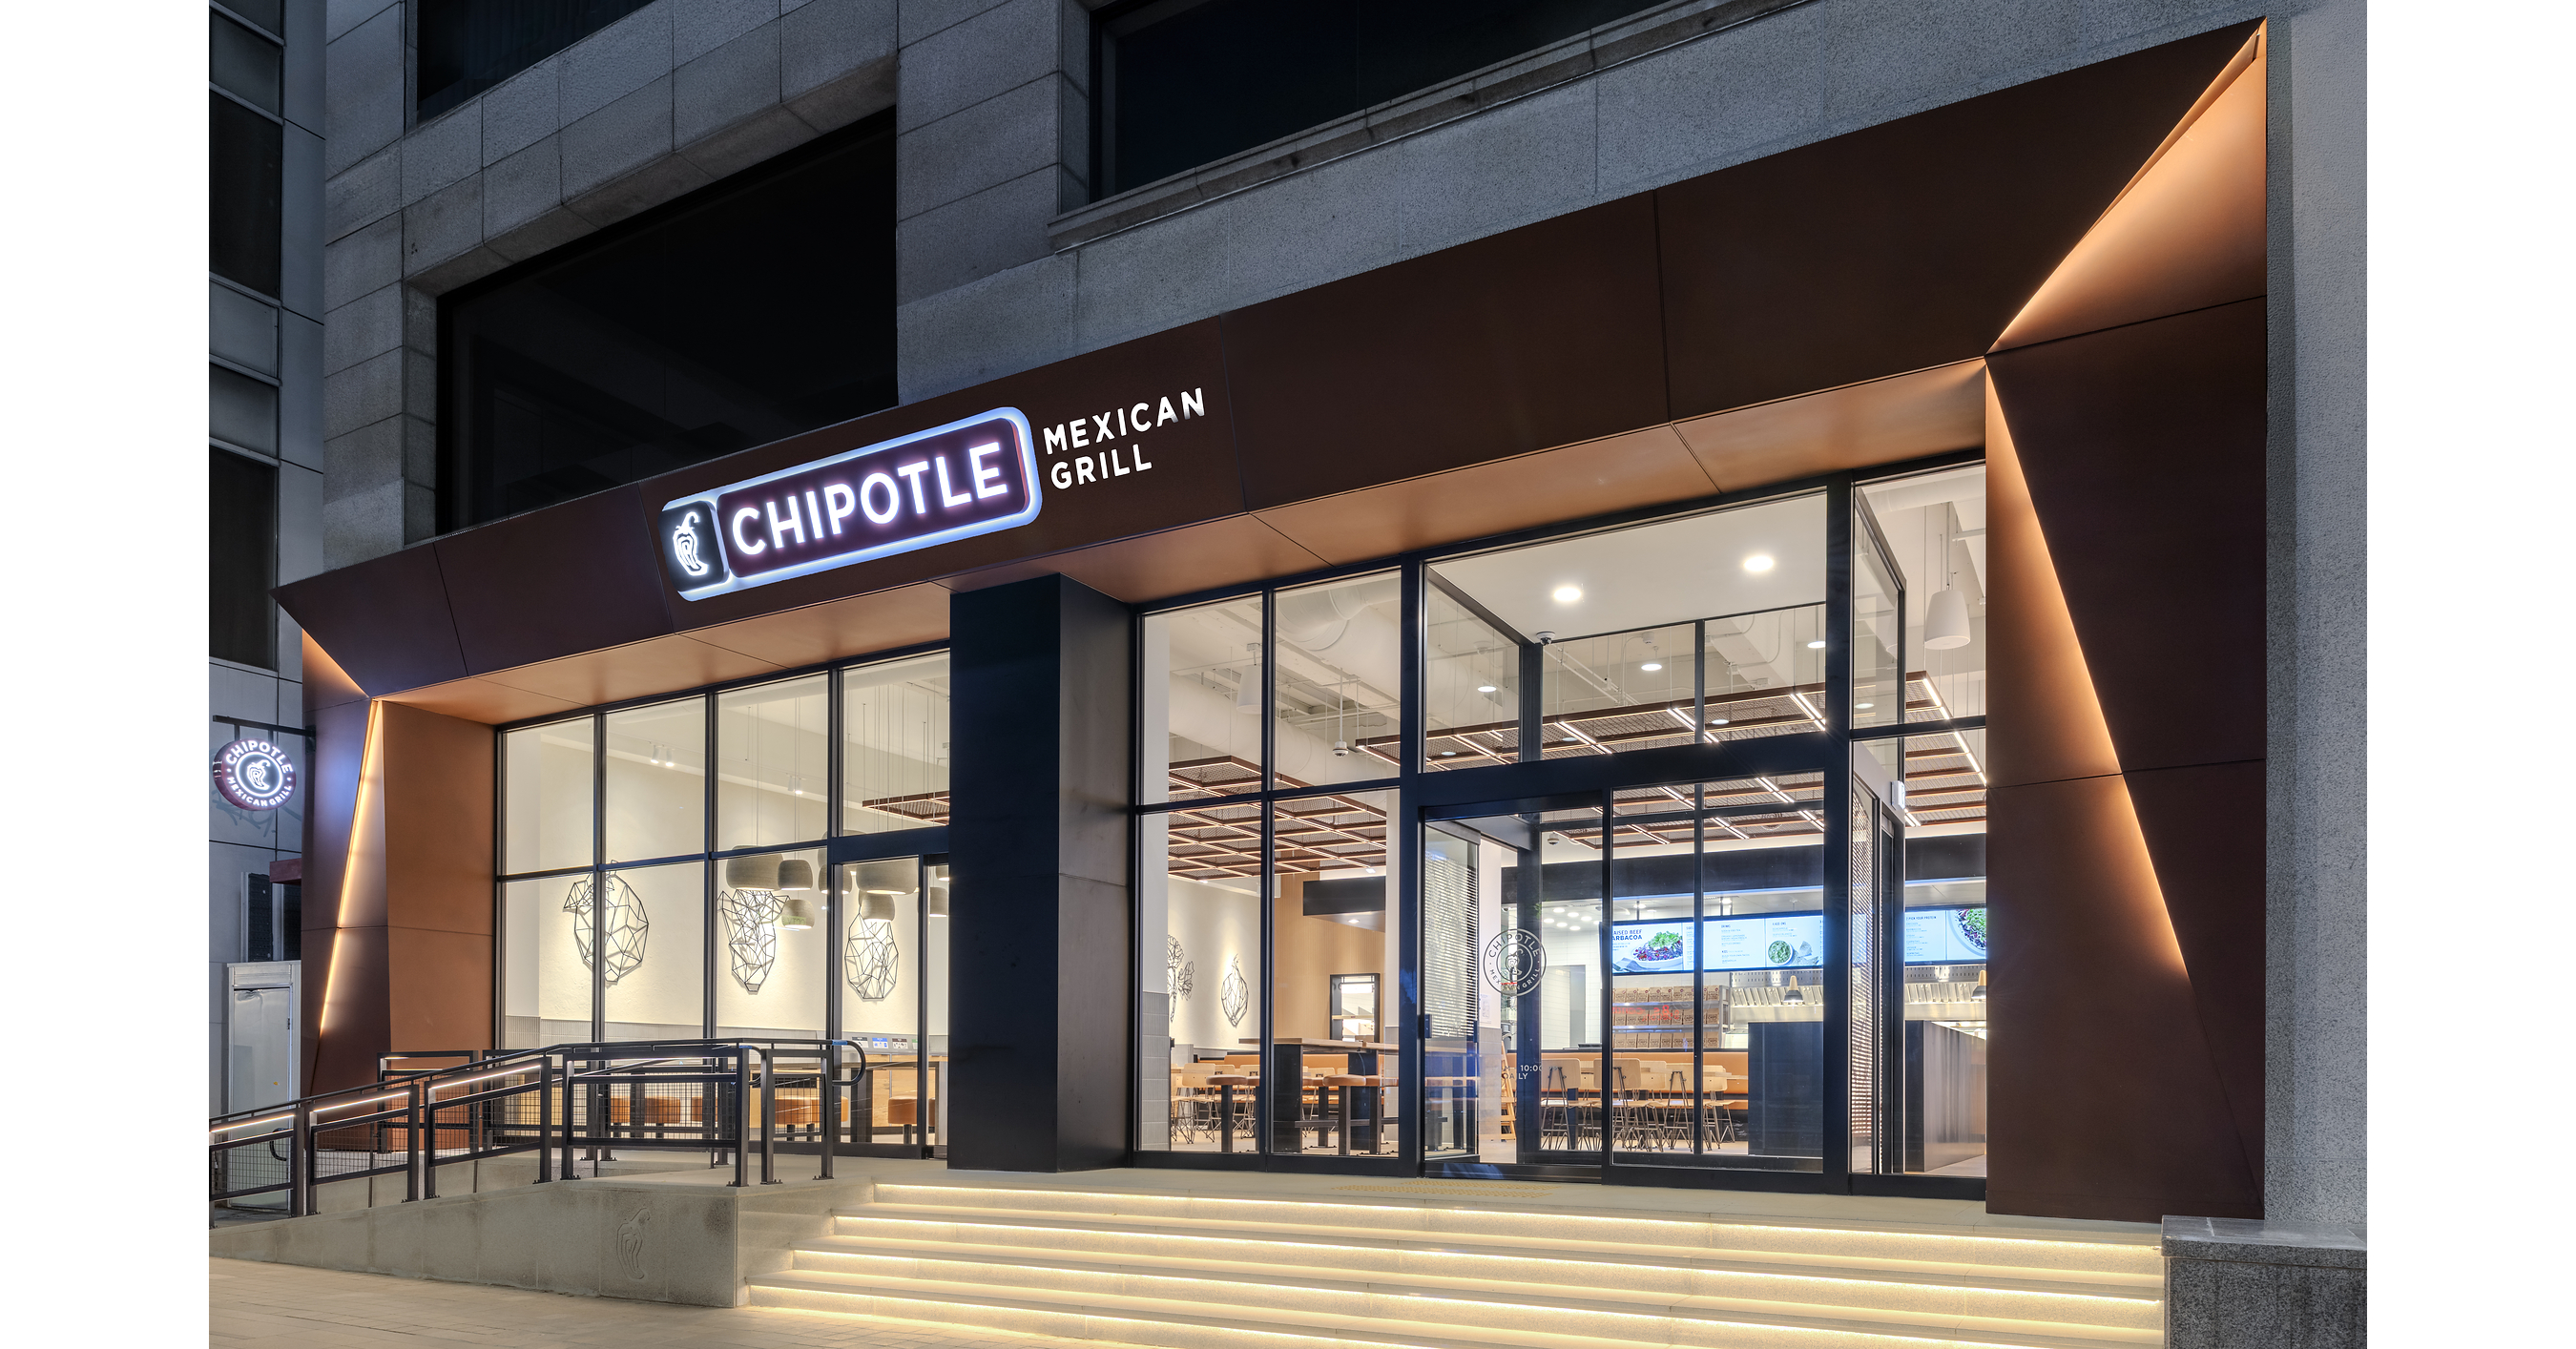
Chipotle opened its first Asian restaurant in Seoul, South Korea, via a joint venture with Sangmidang Holdings, aiming to use South Korea as a reference market for broader Asia expansion. The company plans two additional Chipotle locations in South Korea by end-2026, followed by its first Singapore restaurant in 2027, reflecting confidence in demand for “real food prepared fresh and served fast.” The news is strategically positive for CMG’s international growth outlook, but it is not accompanied by near-term financial figures.
Analysis
This is not an earnings driver in the near term; the real signal is capital-efficiency and brand portability. A JV structure lowers balance-sheet risk and makes Asia a low-capex option on future growth, but only if unit economics are strong enough to justify repeatable rollout. If that proof point lands, the stock can earn a higher terminal multiple because investors will start capitalizing a multi-country expansion path rather than just domestic store count.
Second-order, Korea matters because it is a higher-bar test market than many of the easier Asian entry points. A credible launch there would pressure premium fast-casual peers like SHAK and, more indirectly, global growth narratives at QSR/YUMC by showing that a U.S. premium brand can travel without aggressive discounting or heavy localization. The loser is any competitor whose international story relies more on novelty or subsidies than true repeat traffic.
Near term, the market should not pay up for the opening itself; the next 1-3 months are about evidence on throughput, average unit volumes, and whether the partner model preserves margins. The thesis is fragile if future openings slip, if menu adaptation erodes the brand, or if reported economics look royalty-like rather than store-like. Falsifiers are simple: weak repeat traffic in Korea, no visible path to multiple sites per market, or a deceleration in core U.S. comps that makes Asia look like a distraction rather than an option.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in CMG; treat this as a 6-18 month option-value story and wait for disclosed Korea traffic/AUV data before adding exposure.
- Relative value: long CMG / short SHAK on any 5%+ post-news divergence if the market starts pricing Asian expansion optionality; fade if SHAK shows superior traffic or CMG signals weak unit economics.
- Set a catalyst alert for CMG's next quarterly update: if management implies payback under ~3 years and confirms additional Asia sites by year-end, consider a long CMG vs QSR/YUMC basket for multiple expansion.
- If the stock sells off on the news, use weakness selectively to build a small long CMG position only if U.S. same-store sales and margins remain intact; stop out if management guidance implies Asia is absorbing attention without measurable growth leverage.
More News
- Christine Lagarde: IMFC Statement
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Solar power booms in Philippines as war on Iran spikes energy costs
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'