
Waters Sets Benchmark for Standardized Spectral Flow Cytometry with Commercial Launch of BD FACSDiscover A7 Cell Analyzer
Source: PR Newswire
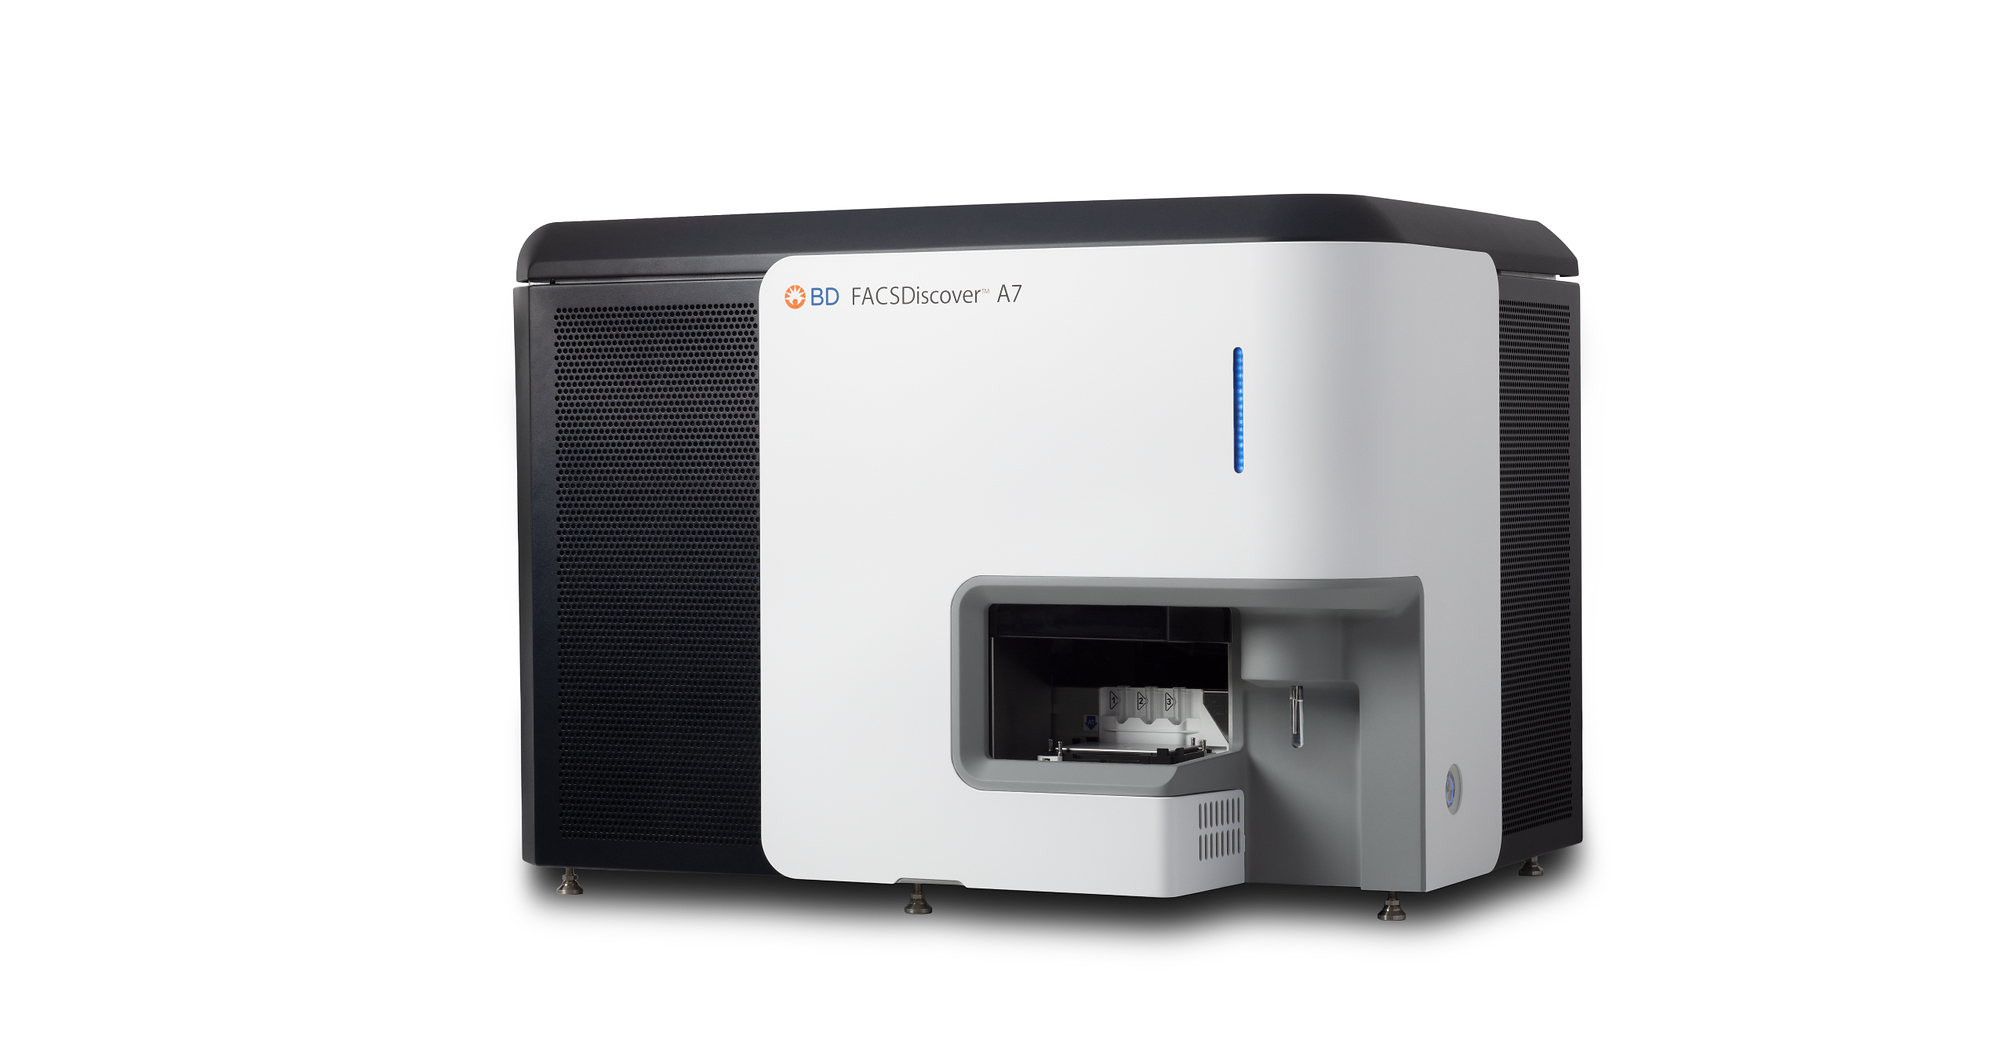
Waters launched the BD FACSDiscover A7 Cell Analyzer globally, expanding its spectral flow-cytometry platform for academic, pharmaceutical and CRO laboratories. The system supports routine experiments measuring 50+ single-cell parameters and targets reproducibility of less than 10% coefficient of variation across more than 50 dyes, supported by automated calibration, quality control and integrated workflow software. The launch strengthens Waters' life-sciences instrumentation portfolio, though the release provided no revenue, pricing or sales guidance.
Analysis
The investable issue is not a single instrument shipment but whether Waters can convert the acquired BD biosciences installed base into a recurring ecosystem of reagents, service and informatics. Standardized multi-site workflows reduce validation friction for pharma and CRO customers, which should raise switching costs and improve service-contract attachment; however, initial placement economics may be margin-dilutive if management uses aggressive pricing to seed accounts. The relevant proof point over the next two earnings cycles is biosciences organic growth, recurring-revenue mix and segment gross margin rather than launch commentary.
CYTK is the clearest competitive read-through: broader access to high-parameter, standardized analysis could pressure its premium spectral-flow growth narrative, particularly in academic core facilities and decentralized translational-research labs. The second-order benefit to Waters is strongest in CROs, where reproducibility can become a procurement criterion and create fleet-level replacement opportunities; the counterpoint is that capital budgets remain constrained and customers may defer purchases while the former BD business navigates commercial and regulatory-transition complexity.
Near-term equity impact should be limited absent disclosed order activity, pricing or backlog. Over 1-3 months, channel checks on A7 placements, consumable pull-through, and cross-selling into Waters' existing pharma accounts can support a re-rating if the acquired business shows credible acceleration. Over 6-18 months, the thesis fails if biosciences growth remains below peer instrument growth, gross margin deteriorates from discounting, or regulatory-transfer delays impede tender eligibility and service continuity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- Maintain WAT as a watch-to-buy rather than chase the launch: add only after management quantifies biosciences order growth and recurring-revenue attachment at the next results; target a 6-12 month position if segment growth exceeds company growth without gross-margin dilution.
- Establish a small 3-6 month relative-value watchlist of long WAT / short CYTK, but do not execute until distributor or customer checks confirm competitive displacement. The pair is attractive only if A7 placements are incremental to Waters while CYTK's academic/core-facility demand or guidance softens.
- For BDX, treat the announcement as strategically neutral-to-modestly positive rather than a catalyst; the key monitor is whether transition-service, indemnity or retained regulatory obligations create unexpected costs. Avoid using this as a standalone reason to alter BDX exposure.
- Set a downside trigger on any WAT long: reduce if biosciences organic growth fails to improve by the second post-launch earnings report, if segment margin declines materially, or if regulatory-transfer timing disrupts customer ordering. Missing data required before underwriting revenue impact are instrument ASP, backlog, consumable attach rate and acquisition-segment margin.
More News
- Waters’ new AI tool targets one of the pharmaceutical industry’s most tedious tasks
- Ferrovial 9M 2026 presentation: profitability jumps 24% on pricing power
- Labcorp Reports Strong 2026 Third Quarter Results; Raises Full Year 2026 Guidance
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Fortinet’s stock is taking a dive after earnings. Here’s why.