
/C O R R E C T I O N -- Bridge to Life, Ltd./
Source: PR Newswire
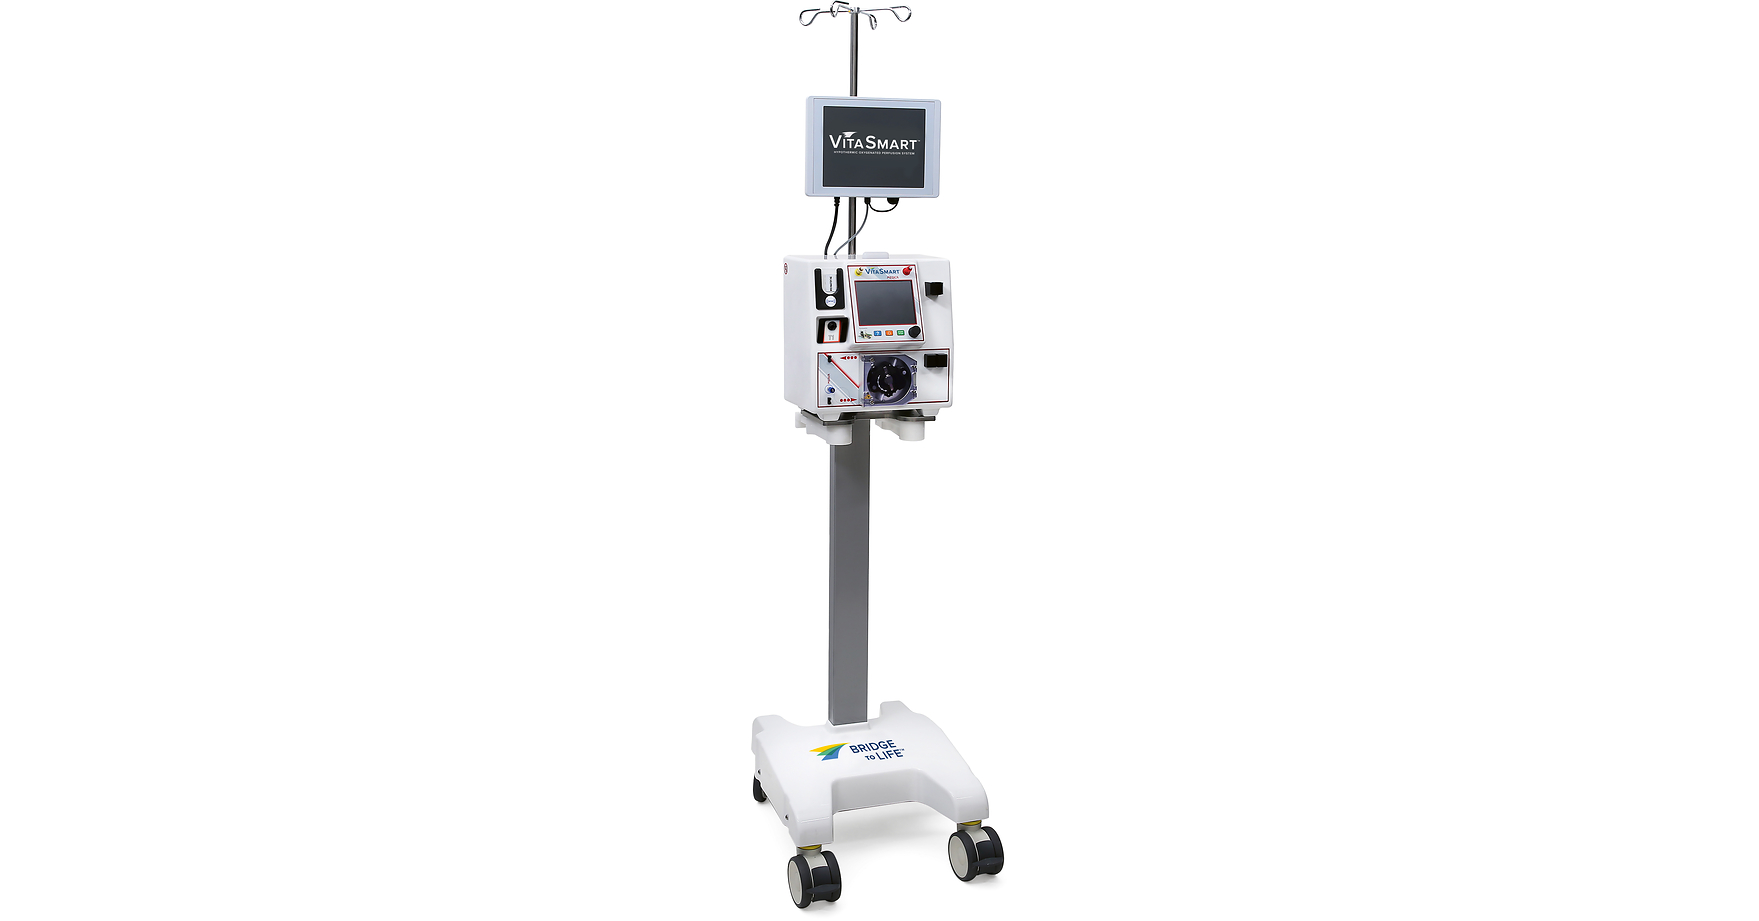
NICE recommended routine NHS funding for ex-situ machine perfusion devices HTG780, endorsing Bridge to Life’s VitaSmart™ HOPE system for deceased donor liver preservation. The guidance cites clear clinical and financial benefits versus static cold storage, including improved graft survival and fewer biliary complications, supporting HOPE as a potential standard of care. The announcement is likely a positive catalyst for Bridge to Life’s adoption and commercialization momentum, especially in the UK, following its FDA De Novo clearance and expanding international availability.
Analysis
The direct economic winner is the private vendor, but the investable readthrough is broader reimbursement legitimacy for machine perfusion. NICE effectively removes the last big excuse hospitals use to delay adoption: not whether the therapy works, but whether the workflow and budget can support it. That matters most for centers with constrained OR time and lower transplant volumes, because a lower-capex system can clear procurement hurdles faster than premium platforms.
The more interesting public-market angle is competitive compression, not pure category expansion. A simple, cost-efficient HOPE workflow can erode the value proposition of higher-priced liver perfusion systems if hospital buyers decide they only need enough technology to unlock marginal organs, not the most feature-rich platform. That puts pressure on premium liver-exposed names like TMDX if the market starts assuming every perfusion validation event is automatically accretive to all players.
Timing is key: the headline itself is sentiment-positive, but actual revenue impact is a 1-3 quarter procurement story in the UK and a 6-18 month diffusion story in the US. The contrarian point is that NICE is endorsing a class, not guaranteeing fast volume conversion for any single vendor. The thesis fails if transplant centers show faster-than-expected adoption of machine perfusion broadly, with measurable uplift in liver procedure counts and disposables attach rates; it also fails if TMDX proves HOPE and normothermic systems are complementary rather than substitutive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not chase the headline in public equities; the direct beneficiary is private and the near-term earnings impact for listed medtech names is likely negligible.
- If TMDX gaps up 2-4% on sympathy, fade it with a small 1-3 month put spread or tactical short; risk/reward is favorable if the market is overextending the "perfusion validation" readthrough into premium liver-device demand.
- Use TMDX upcoming disclosures as the falsifier: cover the short if liver revenue growth, procedure volumes, or consumables attach rate re-accelerate sequentially by >10%.
- Set a watch item on UK procurement announcements over the next 1-2 quarters; any evidence of rapid NHS tenders or center-level conversion would suggest the reimbursement unlock is real and could support a broader machine-perfusion basket.
- Avoid a broad healthcare-long expression here unless follow-on data show category expansion rather than vendor substitution; otherwise the signal is company-specific, not sector-wide.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.