
Xinhua Silk Road: Vom Tempelbesuch bis zum Inselurlaub: Die Insel Meizhou in Fujian steigert ihre Attraktivität für Touristen
Source: PR Newswire
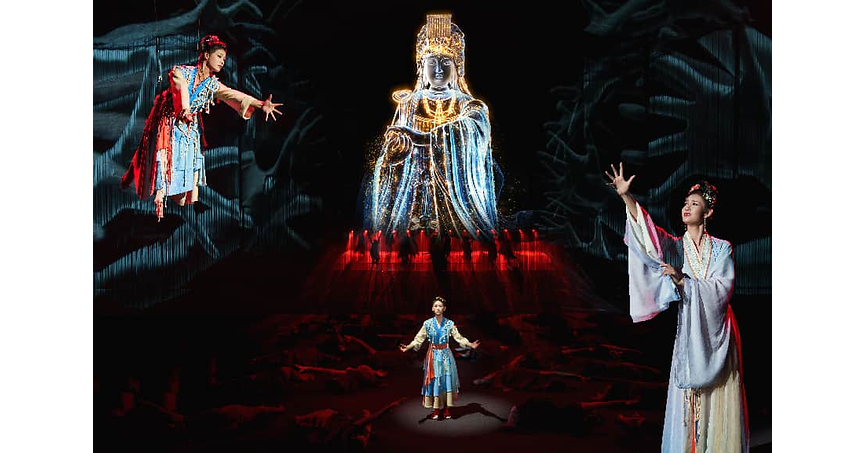
Meizhou Island in Fujian attracted approximately 3.23 million tourists in 2025, surpassing the 3 million mark for the first time as it broadened its appeal beyond Mazu temple visits. The island is targeting longer stays and higher tourism spending through Mazu-cultural attractions, live performances, nightlife and beach-oriented leisure offerings, with growing demand from families, self-driving travelers and younger visitors.
Analysis
This is not an investable single-asset catalyst; it is promotional destination-marketing content without disclosed spend, hotel inventory, transport capacity, visitor monetization, or independently verified occupancy data. The potentially relevant mechanism is a shift from low-spend day trips toward overnight leisure demand, which would lift lodging, food and beverage, ferry/ground transport, and local retail revenue per visitor more than headline arrivals. Until regional booking and RevPAR data confirm that conversion, the effect is immaterial for listed China travel equities.
For the next 1-3 months, the only plausible read-through is sentiment toward domestic, experience-led travel during holiday periods, with Ctrip (TCOM), Tongcheng Travel (0780.HK), H World (HTHT), and China Tourism Group Duty Free (601888.SS) as imperfect proxies. The more relevant 6-18 month issue is whether Chinese consumers continue substituting short-haul domestic trips for higher-ticket outbound travel; that would favor online travel agencies and economy/upscale regional hotels, but offers little support to duty-free operators unless visitor spend broadens beyond lodging and attractions.
The contrarian view is that destination upgrades can dilute returns if local authorities add entertainment and accommodation capacity ahead of sustained demand. Religious and cultural tourism is also unusually vulnerable to weather, safety incidents, transport bottlenecks, and changes in domestic discretionary spending; visitor counts alone can mask declining spend per guest. Require evidence of longer average stays, rising ADR/RevPAR, and transaction value per traveler before treating this as a durable consumer-demand signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone trade: impact is too small and no directly exposed listed issuer is identified; monitor Fujian holiday hotel occupancy, average daily rates, and online booking trends through the next Golden Week before acting.
- If domestic leisure booking data accelerate while outbound airfare remains elevated, consider a 1-3 month tactical long TCOM versus short 601888.SS: OTAs capture booking volumes with limited fixed-asset intensity, while duty-free depends more on discretionary basket size and outbound traffic. Exit if domestic hotel booking growth fails to exceed prior-year trends or outbound passenger volumes reaccelerate.
- Watch HTHT regional RevPAR and management commentary over the next two earnings cycles. A sustained occupancy/ADR uplift in lower-tier coastal destinations would support a domestic-travel recovery thesis; absent that verification, avoid extrapolating promotional visitor figures into hotel earnings.
More News
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
- Argentina’s poverty rises to 32 percent under Milei with more pain forecast
- New York sues Polymarket over allegations of illegal gambling operations
- New York sues Polymarket U.S., two months after filing lawsuit against Kalshi
- Meta nears first new high in a year as Muse success showcases winning AI strategy