
HawkEye 360 Establishes First European Subsidiary in Luxembourg
Source: PR Newswire
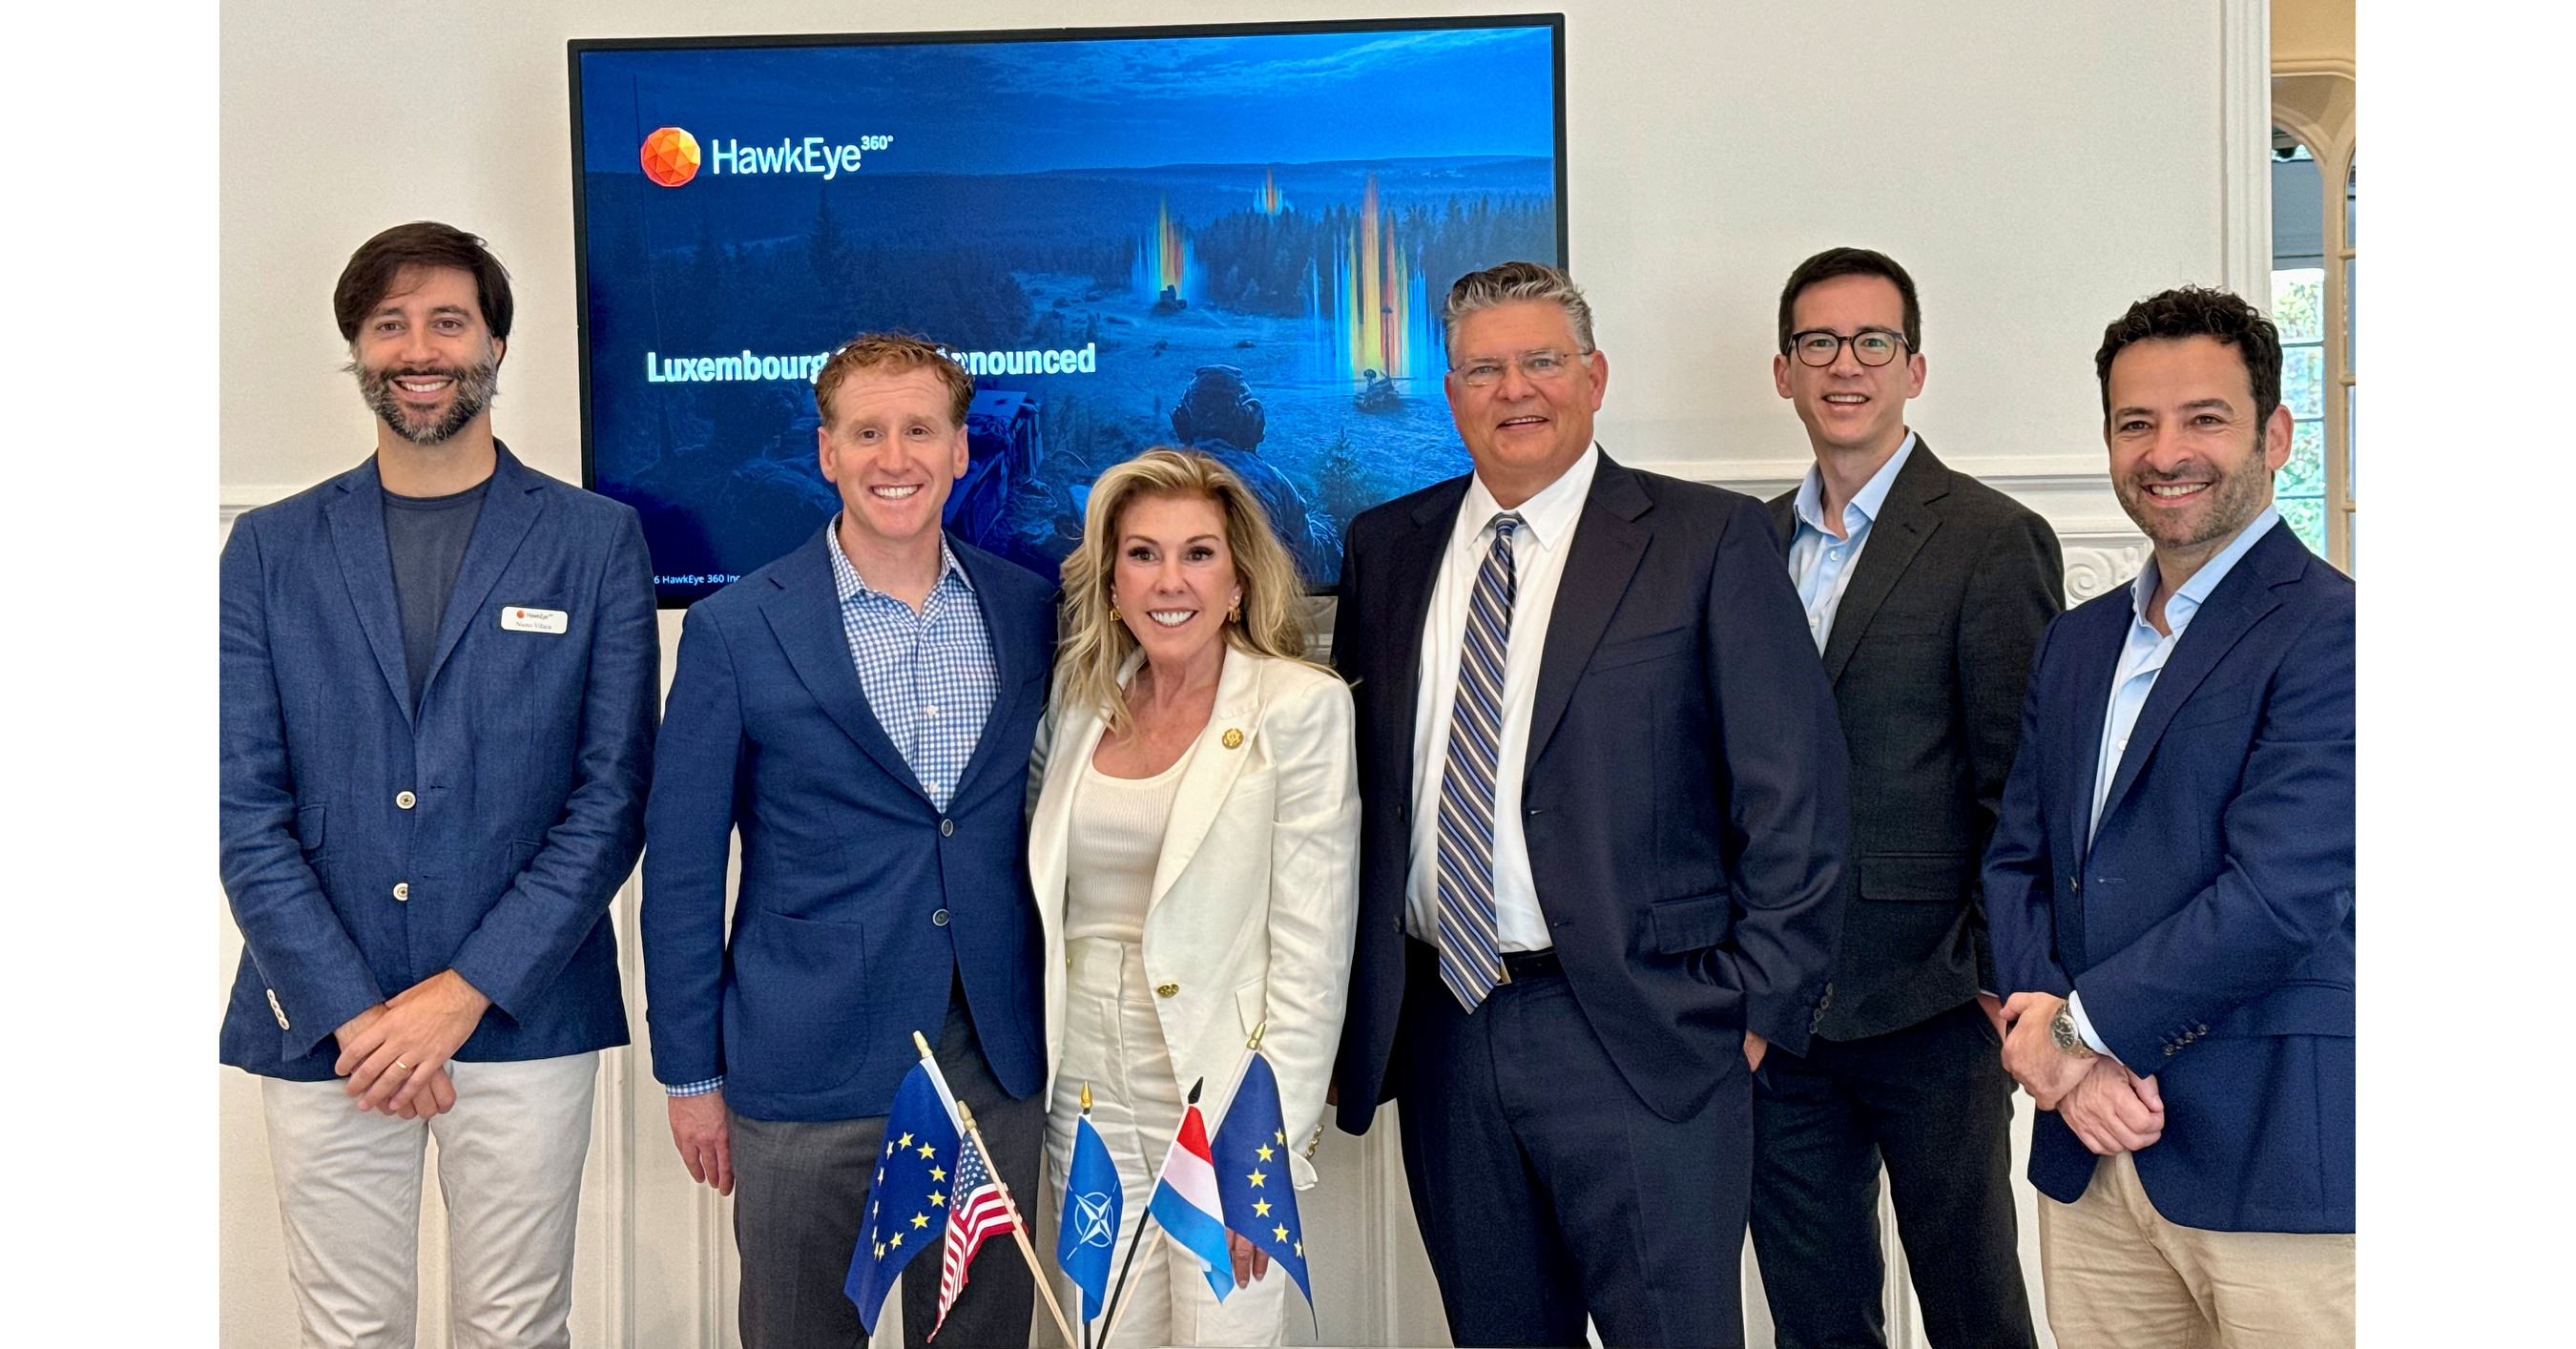
HawkEye 360 established HawkEye 360 Luxembourg, S.à r.l., its first European subsidiary, to expand its EU operational presence and pursue emerging European defense and space programs. The Luxembourg hub is intended to deepen government and industry partnerships and bring the company's space-based radio-frequency data, signal processing and AI analytics closer to European customers. The move supports long-term growth positioning amid accelerating European defense requirements, but the release provided no financial targets, contract awards or quantified revenue impact.
Analysis
The subsidiary is strategically useful only if it converts into eligibility for sovereign procurement, local-content scoring, or classified-data handling—not merely commercial proximity. European defense budgets increasingly favor interoperable but politically acceptable suppliers; a Luxembourg footprint can lower procurement friction for HAWK, yet it also requires local hiring, compliance and partner economics that may dilute near-term gross margin before revenue appears. The more immediate read-through is competitive: HAWK becomes a more credible RF-intelligence partner to European primes, while listed geospatial peers BKSY, PL and SPIR face a modest disadvantage where customers seek multi-source intelligence architectures with local operational support.
The market should not capitalize this announcement as a material revenue catalyst absent named contract awards, a European backlog disclosure, or evidence of a sovereign data-processing arrangement. European defense sales cycles are typically 12-36 months, and the relevant 1-3 month catalyst is inclusion in a funded program or a prime-contractor partnership, not additional diplomatic or marketing announcements. A failed thesis would be rising international operating expense without a corresponding increase in bookings, backlog, or management guidance by the next two earnings reports.
Contrarian view: local presence may be table stakes rather than differentiation, particularly as European governments emphasize strategic autonomy and indigenous space capabilities. The greatest upside is therefore not standalone EU sales but embedding HAWK's RF layer into systems sold by European defense primes; that route improves distribution but gives primes bargaining power and may limit HAWK's share of economics. With no contract value or capex commitment disclosed, this is an information-development signal rather than a standalone reason to add risk.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- Maintain HAWK as a watch-list long rather than initiating on the release; add only after a disclosed EU contract, funded pilot conversion, or international-bookings/guidance uplift. Target a 6-18 month holding period once commercial validation is present.
- Set an earnings alert for international revenue growth, backlog, sales-and-marketing expense and gross-margin commentary over the next two quarters; escalating EU costs without bookings is a short-term negative and invalidates the localization thesis.
- For existing HAWK exposure, use a 3-6 month relative-value hedge via a small long BKSY or PL basket until contract evidence emerges; this reduces broad geospatial-defense multiple risk while preserving HAWK-specific upside from procurement wins.
- Do not pursue options until implied volatility and liquidity are assessed; the missing variables are contract timing, award size and EU operating-cost commitments, making directional premium spend unattractive at this stage.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- BOJ expected to hike rates by 25 basis points to fresh three-decade high: CNBC survey
- Saudi coalition says Houthi drone destroyed near Mecca
- Iran war increasing inflation, straining US munitions: congressional report
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard