
Breaking Boundaries: EcoFlow Unveils RIVER Gen4 and PowerRock 4000 at IFA 2026
Source: PR Newswire
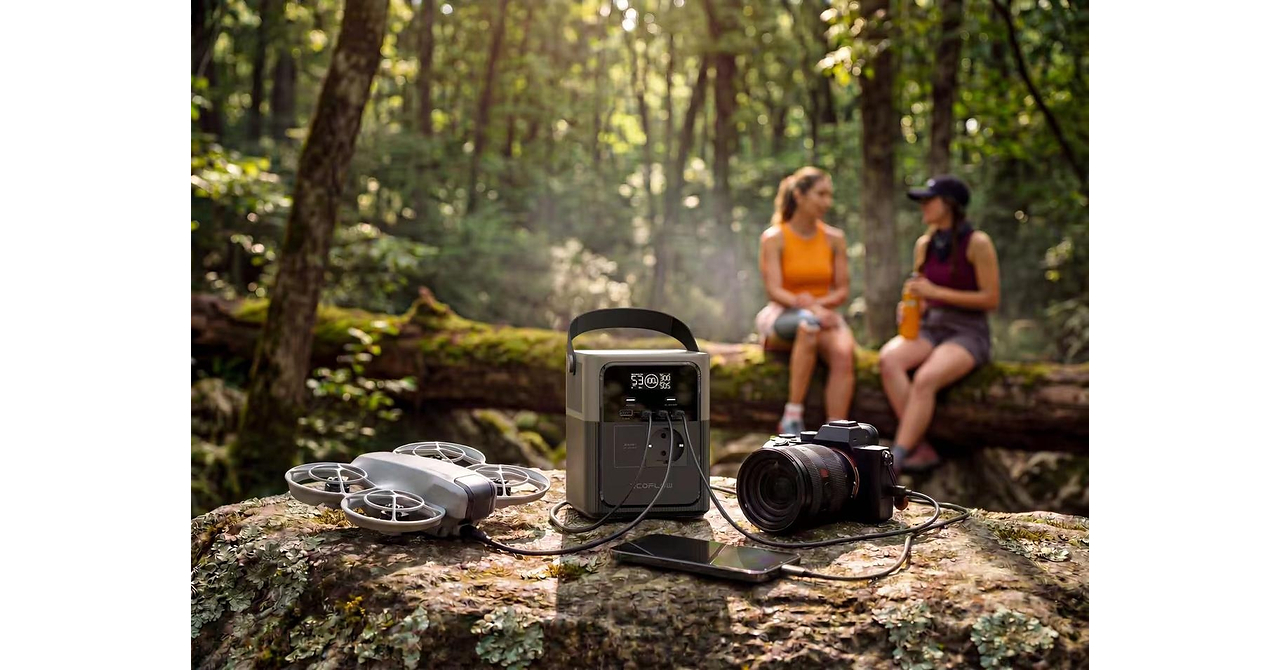
EcoFlow unveiled two new products at IFA 2026—RIVER Gen4 portable power stations (256 Wh/300 W for RIVER 260 Gen4 and 512 Wh/500 W for RIVER 520 Gen4) and an industrial PowerRock 4000 rated at 4 kW continuous and 7.2 kW for up to 100 seconds—with UPS switchover under 10 ms on the RIVER models. The company also highlighted OCEAN 2 three-phase home storage (up to 63 A whole-home backup switching in 0 ms) and the STREAM home battery series with Local Mode from October 2026. Messaging is upbeat on efficiency (e.g., up to 77.6% claimed household electricity cost reduction for OCEAN 2 with solar), but this is primarily product/launch news with limited immediate financial market read-through.
Analysis
This is more of a competitive intelligence signal than a direct fundamental event: the interesting part is not the launch itself, but the bundling of consumer, prosumer and light-commercial use cases into one installation ecosystem. That suggests the European storage market is moving from “battery as appliance” toward “battery as channel,” where software, installer workflow and retrofit simplicity matter as much as cell chemistry. The second-order winner is whoever controls the local installer/distributor relationship and can compress quoting-to-commissioning time; that favors scaled inverter/battery platforms over point-product niche brands.
For public comps, the pressure is most relevant to ENPH, SEDG and TSLA Energy in Europe, plus smaller generator/genset and rental incumbents that rely on temporary power, indoor events and urban construction. The industrial portable power angle is a substitution story: if battery units keep taking share from small diesel gensets, the first-order hit is not unit volume at Cummins or industrial rental fleets, but mix erosion in the higher-margin accessory/service stack. In the near term this is more about share-of-mind and channel expansion than immediate revenue displacement.
The contrarian view is that the headline can overstate TAM. These products still face economics, certification and installer-friction hurdles, and the claims are about capability rather than converted demand. The catalyst path is likely 1-3 quarters of distributor rollout data and installer adoption; absent evidence of material European backlog or channel inventory build, the stock-level impact on public peers should stay muted. The real falsifier for a bearish storage thesis would be sustained European residential attach rates or pricing discipline at the public comps into the next earnings cycle; otherwise this reads as competitive noise, not a regime shift.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Do not initiate a stand-alone trade on EcoFlow; treat this as a watch item until we see distributor sell-through or installer adoption data in Europe over the next 1-2 quarters.
- For storage exposure, prefer a relative-value pair: long ENPH vs short SEDG into the next earnings window if European channel checks confirm faster retrofit traction and better installer economics for lower-friction systems.
- Add a tactical alert on CMI and major rental/genset names for 6-12 months: if battery-based jobsite power gains visible share in dense EU cities, the risk is mix compression rather than outright volume loss; consider trimming only on evidence of weaker small-generator orders.
- If holding clean-energy equities, use any pop in European home-storage enthusiasm to fade over the next 1-3 weeks unless company commentary shows real backlog conversion; product launches alone do not justify multiple expansion.
- Set a trigger on public storage peers: if EU residential storage gross margins compress by >200 bps or channel inventory rises next quarter, increase the short in SEDG/underweight in the group; if margins hold, the competitive threat is likely overstated.
More News
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- Ukraine launches over 1,000 drones at Russia, setting oil facilities ablaze
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Trump defends Russian sanctions relief, lashes out at Zelenskyy
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- China’s Coal Output Drops as Concerns Build Over Winter Supply
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate Consensus Estimates Platforms With AI
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More