
Reddit vs. The Trade Desk: One's Revenue Growth Overtook the Other's Lead
Source: fool.com
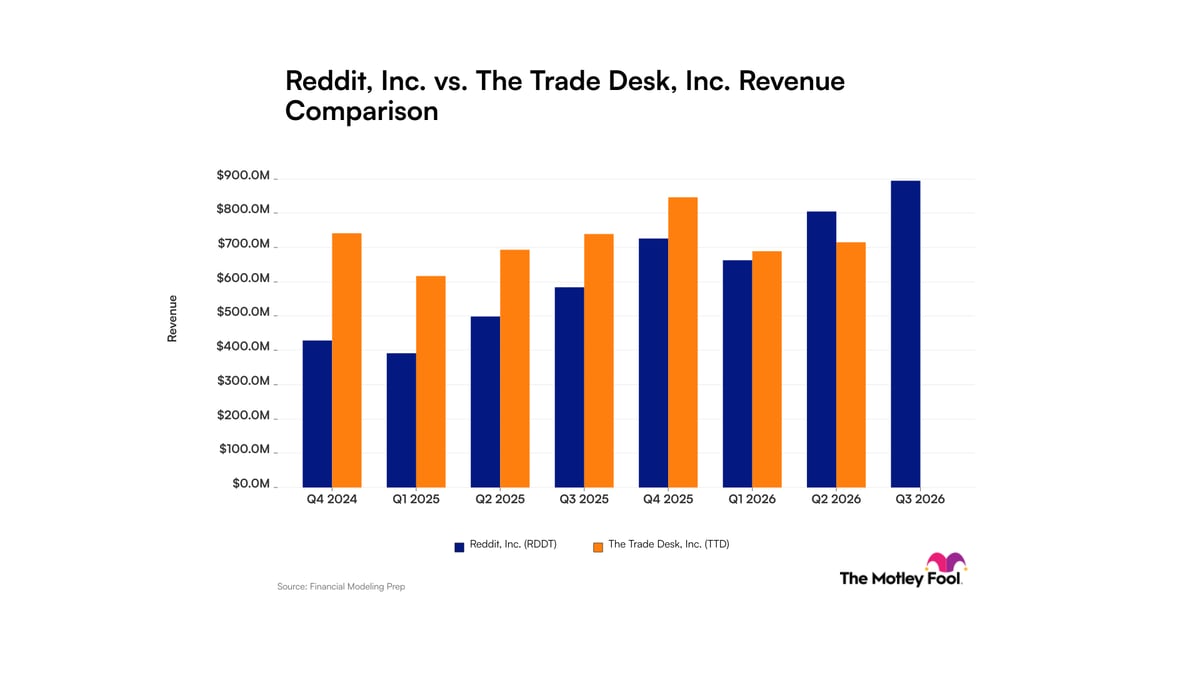
Reddit reported Q3 2026 revenue of $895 million, up 53% year over year, with daily active unique users rising 12% to 130.3 million; its quarterly revenue has surpassed The Trade Desk's in 2026. The Trade Desk's revenue growth slowed from 22% year over year in Q4 2025 to 3% in Q2 2026, and it expects a year-over-year revenue decline in Q3 amid intensifying competition for digital ad spending.
Analysis
The key divergence is monetization, not simply audience growth: Reddit’s revenue rising much faster than its reported DAU points to stronger monetization per user, but the article does not separate pricing, ad load, mix, or geography. That makes the growth less durable until ARPU and advertiser retention confirm it. Mandatory login tests could improve identity and ad targeting, yet risk shrinking logged-out reach, search referrals, and community discovery; monitor DAU, engagement, and traffic sources alongside revenue. Google Cloud’s extension supports continuity, not proof of favorable economics or incremental licensing revenue. S&P 500 inclusion may support near-term ownership and liquidity, but is not an operating catalyst.
For The Trade Desk, weaker growth and expected contraction raise the risk that advertisers shift toward closed platforms and direct-buy inventory, including Netflix and Reddit. However, these platforms are not necessarily one-for-one substitutes for an independent buying platform; a broader ad-budget pullback could also explain deceleration. Workforce cuts may protect costs but could impair product execution. Allegations involving a former finance director are a governance headline, not evidence of company involvement.
The source’s TTD chronology is internally inconsistent: its revenue table ends at Q2 2026, while the narrative cites a Q3 outlook and labels a Q4 figure as 2026. Verify filings and guidance before trading. Near term, expect headline volatility; over 1–3 months, monetization and guidance updates matter; over 6–18 months, Reddit’s ability to scale ad yield without degrading engagement is the structural test. Contrarian angle: Reddit’s growth may be extrapolated too readily, while TTD’s platform could be discounted as if advertiser choice automatically means disintermediation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing RDDT solely on reported growth or index inclusion. Track ARPU by geography, ad load, advertiser retention, and logged-in test effects; a slowdown in engagement or monetization would challenge the bull case.
- Treat TTD as an underweight and consider short exposure only after verifying the latest reported quarter and formal guidance. Falsifiers include renewed growth acceleration, stable customer spend, or evidence that independent-platform budgets are holding up.
- A small, risk-controlled RDDT/TTD pair is a watch-list trade, not a clean relative-value signal: both remain exposed to digital-ad demand. Reassess after reconciling TTD’s conflicting dates and confirming comparable reported periods.
- Do not assign material value to the Google Cloud extension without disclosed economics; monitor Reddit’s cloud costs and any verified licensing revenue, and watch whether login requirements reduce referral traffic or unique-user growth.
More News
- Why AI is boosting Meta's ad business while hurting Google search
- Here are 3 big things we're watching in the stock market in the week ahead
- Companies promised AI gains— here's how the payoff showed up in earnings
- TechCrunch Mobility: A new, bigger AV boom is here
- Street Calls of the Week
- Unicaja Q3 2026 slides show 8% profit gain, 95% payout ratio