
Why Northrop Grumman Stock Rallied Today
Source: fool.com
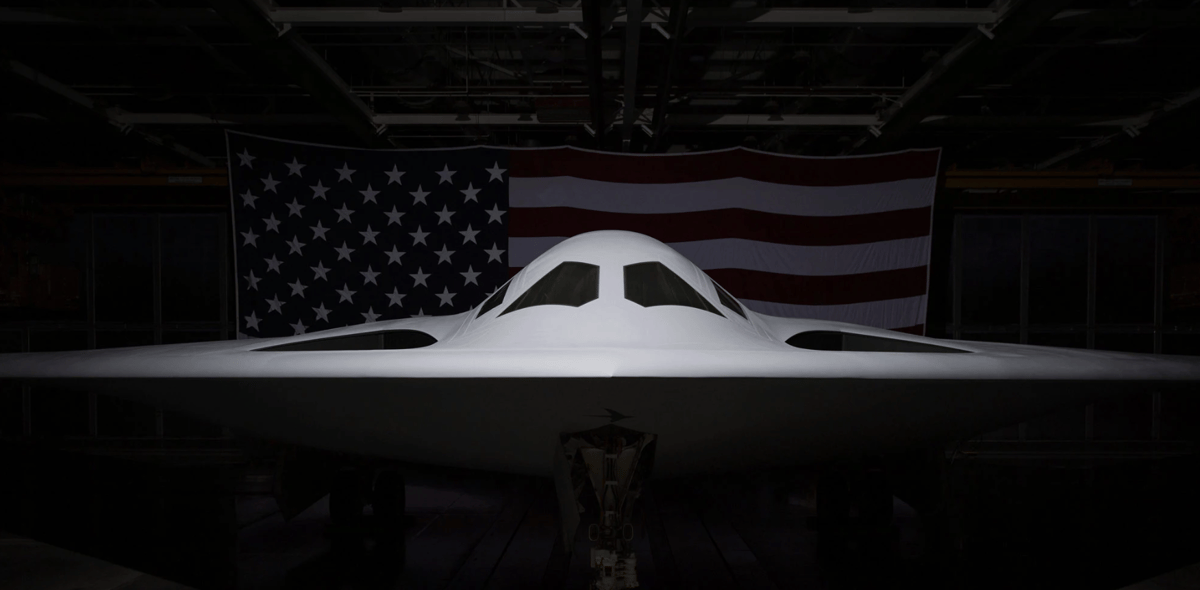
Northrop Grumman reported third-quarter sales up 7% year over year to $11.1 billion and net earnings up 2% to $1.1 billion; EPS of $7.89 beat the $7.18 analyst expectation. Net awards of $16.4 billion lifted its order backlog to $109.6 billion, while management forecast 2026 sales of $44 billion, adjusted EPS of $29.35–$29.75, and free cash flow of $3.1–$3.5 billion. Shares rose more than 4% as the company cited rising demand for defense capabilities amid conflicts in Ukraine and the Middle East.
Analysis
The earnings reaction is positive, but the more important signal is whether demand converts into profitable, cash-generative delivery. Sales grew faster than net earnings, so the headline beat does not by itself establish operating leverage; segment margins, program charges and working-capital movements are the key checks. A large backlog can support visibility without guaranteeing near-term funding, margin or cash conversion—particularly for complex development programs such as B-21 and Sentinel.
Near term, Tuesday’s sharp move raises the bar for further upside: estimate revisions and confirmation of the full-year free-cash-flow range matter more than another broad statement about defense demand. Over 1–3 months, watch contract awards become funded orders and whether cash flow tracks earnings. Over 6–18 months, sustained allied procurement could support the sector, but budget constraints, schedule slippage or cost growth could turn long-duration backlog into execution risk. Lockheed Martin, RTX and General Dynamics may benefit from broad defense spending, while competition for budgets and skilled labor can limit how much industry-wide demand becomes incremental margin.
Contrarian read: investors may be treating backlog as near-term earnings visibility. Its value depends on timing, funding and program economics. The thesis weakens if management cuts cash-flow guidance, margins deteriorate, or major programs show further execution problems; it strengthens if cash conversion and margins improve alongside awards.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Do not chase the post-earnings jump on demand commentary alone. Reassess after reviewing segment margins, program charges and working-capital detail; these determine whether the sales growth is translating into earnings quality.
- For a 1–3 month catalyst, track funded awards and quarterly free-cash-flow progress against management’s range. Treat a guidance reduction or persistent cash-flow shortfall as a thesis-failure signal, not merely a timing issue.
- Keep NOC on a conditional pullback-buy watchlist rather than initiating a momentum position here. The upside case is durable, funded demand with improving cash conversion; the downside is that program execution absorbs the apparent demand benefit.
- For sector exposure, compare NOC’s margin and cash-flow revisions with Lockheed Martin, RTX and General Dynamics before expressing a relative-value trade. The article alone does not establish which peer offers better valuation or execution-adjusted upside.
More News
- AI Fears Return With Data Center IPO Flop; SpaceX, Netflix Earnings
- Stocks making the biggest moves midday: Hasbro, Northrop Grumman, Equifax, General Motors & more
- Stocks making the biggest moves premarket: RTX, General Motors, Northrop Grumman, Steel Dynamics & more
- Northrop Grumman: 3 Key Takeaways for Long-Term Investors
- Elon Musk says SpaceX and Tesla exploring largest merger in history
- Jio’s Record $3.2 Billion IPO Puts India’s Market Muscle to the Test
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Analyze SEC Filings With AI: A Verification-First Guide
- AI for IR Street Intelligence: Notes, Estimates, and Peers