
Meijer Debuts Sage & Sky, a Juniors Athleisure Line Built on Comfort and Everyday Value
Source: PR Newswire
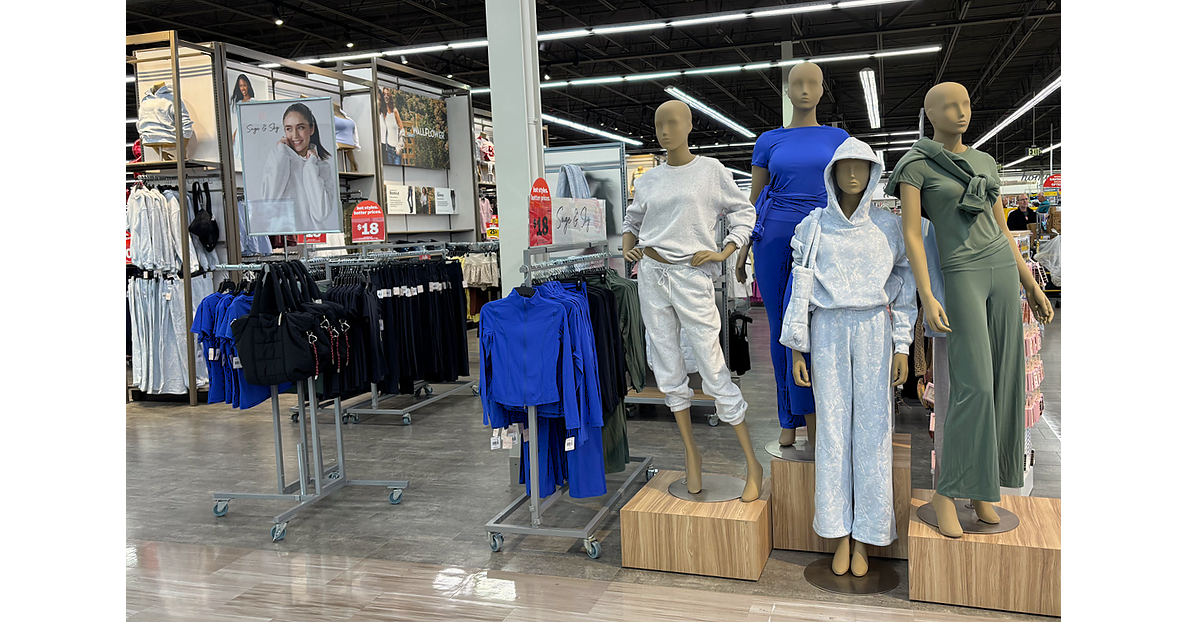
Meijer launched Sage & Sky, an exclusive juniors athleisure line, with tees starting at $14, active bottoms at $18, and fleece pieces at $20 each. Circana estimates activewear represents 35% of the clothing market, while junior sizes in the category are growing 20% year over year.
Analysis
This is a competitive signal, not an earnings catalyst: a value-priced private label lets Meijer test whether juniors athleisure can lift apparel conversion and broader basket attachment without paying for a national brand. The second-order risk is greater pressure on entry-price basics at Target and Walmart, and on brands that rely on wholesale distribution for low-differentiation items. But a single launch does not establish meaningful share capture; unknowns include distribution depth, inventory commitment, sell-through, replenishment, markdowns, and whether purchases are incremental or displace Meijer's existing apparel.
Near term, the launch has little investable impact: Meijer is private, and there is no evidence here of a material exposure change for public peers. Over 1–3 months, watch for expansion beyond the initial assortment, repeat availability, and competitor price or private-label responses. Over 6–18 months, sustained expansion with full-price sell-through would support the thesis that retailers can take more basic apparel demand in-house; weak sell-through or heavy markdowns would instead highlight the limits of trend-led private labels. The contrarian read is that category growth and low opening prices can attract attention while concealing thin unit economics or cannibalization. No public-equity trade is warranted on this announcement alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate position: the launch is too small and operationally unverified to support a directional trade in public retailers.
- Put Target and Walmart on watch for signs of accelerated value-tier athleisure promotions or private-label expansion; treat any effect as a competitive risk to monitor, not an established earnings headwind.
- Reassess only if Meijer broadens distribution or follow-on disclosures provide evidence on sell-through, replenishment, markdowns, and basket incrementality. Those are the missing data needed to judge whether this is share capture or assortment churn.
- Falsification: if the range remains limited, availability is inconsistent, or markdowns rise, the private-label share-capture thesis weakens; sustained expansion with repeat full-price demand would strengthen it.
More News
- Meta put out an ambitious roadmap to Muse monetization after strong quarter and guide
- Sovereign wealth funds' China and Hong Kong investments surge 190% after a bruising slump
- Apple's iPhone Duo in short supply — plus, the 2 stocks fueling an AI rebound
- Billionaires fleeing California could turn a $30 billion tax windfall into a $39 billion loss, Stanford economists warn
- Capital One delivered a strong quarter. Why we're not declaring victory just yet
- Tesla stars Optimus robot production in California as profit falls 43%
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Family Offices: A Stack by Decision Type
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs