
UK Retail Sales Fall, Consumer Confidence Worst Since Covid
Source: Bloomberg
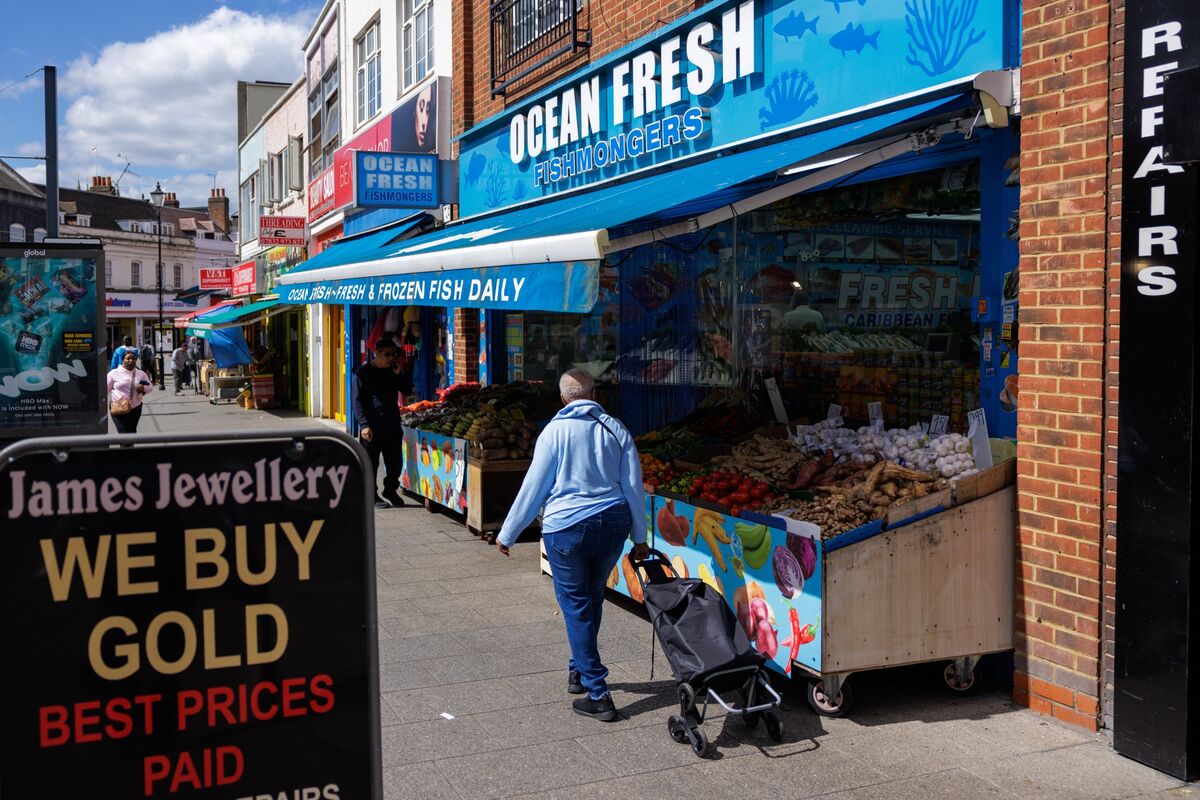
UK retail sales weakened and consumer confidence fell to its lowest level since Covid, with unusually warm September weather cited as unfavorable for retailers. Despite the gloomy consumer data, UK gilts and stocks have shown resilience ahead of next week’s budget; the article provides no sales figures or market-move magnitudes.
Analysis
The useful signal is the divergence between weak household sentiment and resilient UK risk assets: markets may be treating the retail weakness as seasonal/weather-related rather than evidence of a durable demand break. That distinction matters more for apparel and other discretionary categories with seasonal inventory exposure than for the broad market. If weak demand persists after the weather comparison normalizes, discounting could pressure margins before it appears in headline sales; the 1–3 month test is retailer commentary on volumes, promotions and inventories, not confidence alone.
Near term, budget positioning may be suppressing visible stress in gilts and equities. Resilience is not proof that fiscal risk is immaterial: a budget perceived as requiring more borrowing could reprice gilt supply and lift financing costs, with a lagged headwind to rate-sensitive UK consumers and domestic businesses. Conversely, credible fiscal restraint could support gilts while prolonging pressure on demand.
Contrarian read: confidence at a post-Covid low is not itself a reliable spending forecast, and September weather may distort seasonal categories. Avoid extrapolating one weak datapoint into a broad UK recession call. The thesis strengthens if subsequent sales and retailer updates confirm weaker volumes or heavier discounting; it is falsified by a rebound in demand without margin deterioration or a budget that leaves gilt yields stable. No company-level conclusions are warranted from the information provided.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.20
Key Decisions for Investors
- No high-conviction outright trade on this evidence. Keep UK consumer discretionary exposure under review and favor relative-value positioning over a broad UK equity short until sales and retailer updates confirm persistence.
- For a tactical expression, consider underweighting UK discretionary retailers versus more defensive UK equity exposure into the next retail-data and earnings updates; size modestly because weather and seasonal effects may reverse. Reassess if sales stabilize and discounting does not worsen.
- Treat gilts as a budget-event risk rather than assuming recent resilience will continue. Watch the budget’s borrowing and issuance implications and the gilt-yield reaction; a sustained yield rise would strengthen the underweight-duration view, while stable yields would argue against it.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- France is flashing euro crisis signals. This time, the fault lines are different
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- Calm Returns to Markets as Tech Rout Subsides
- France is getting its credit rating reviewed by Moody’s. What to expect as French debt turmoil spills overseas.
- AT1s’ Easy-Money Run Fades as Banks Pay Up for Riskiest Debt