
Gemtek, Qualcomm et gFiber collaborent pour intégrer l'IA en périphérie aux passerelles haut débit Wi-Fi 8.
Source: PR Newswire
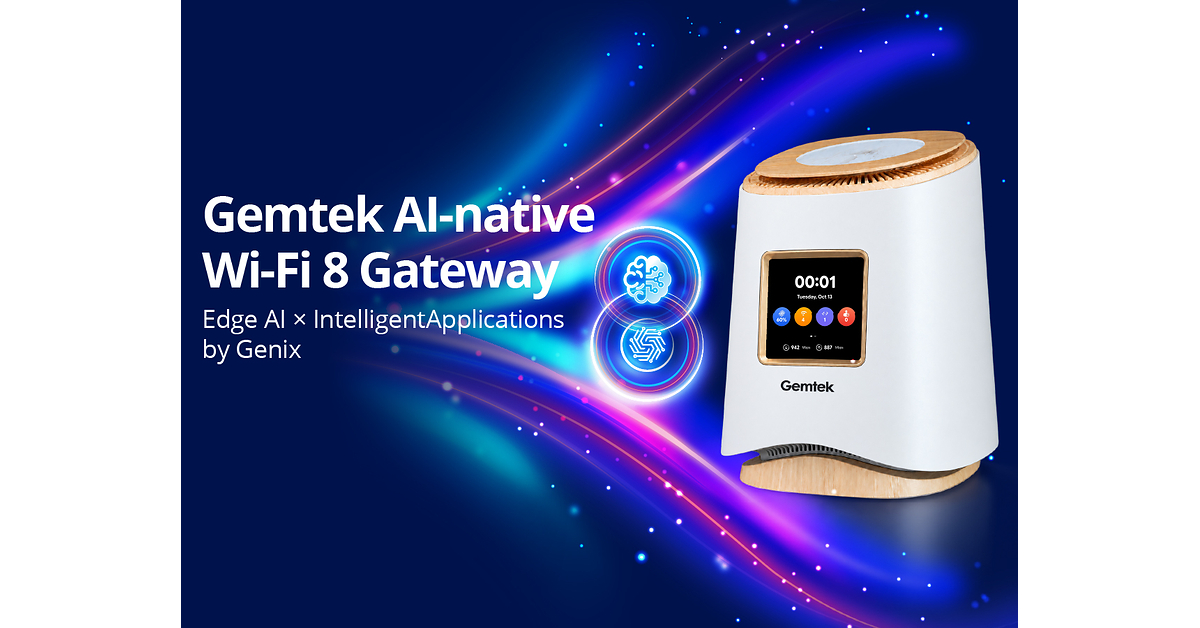
Gemtek, Qualcomm Technologies et gFiber ont présenté une passerelle haut débit Wi-Fi 8 intégrant l’IA en périphérie, développée autour de la plateforme Qualcomm Dragonwing NPro A8 Elite et du logiciel Genix de Gemtek. L’appareil est conçu pour offrir des fonctions locales de gestion du réseau, de sécurité et de commande vocale; le traitement local des demandes prises en charge peut améliorer la réactivité et contribuer à protéger la vie privée. gFiber sera le premier opérateur à la déployer, avec un déploiement commercial prévu en 2027.
Analysis
The strategic value to QCOM is platform validation in a higher-value home-edge compute layer, not evidence yet of a material earnings inflection. The key monetization question is whether operators pay for the added silicon and software, or treat AI features as table stakes while competing mainly on CPE cost. If local inference demonstrably reduces cloud usage, support calls, or churn, broadband operators could justify premium gateways; otherwise, the extra compute, power, and security burden risks becoming an unrecovered BOM cost. Broadcom and MediaTek are plausible platform competitors, while gateway vendors face pressure to match integrated silicon-plus-software offerings.
Near term (days): likely limited fundamental signal; the announcement does not establish shipment volume, pricing, or operator commitments beyond the launch partner. Over 1–3 months, watch for named follow-on operators, production specifications, and procurement commitments. Over 6–18 months, 2027 deployment provides the real test of unit economics, subscriber adoption, and recurring software value. The contrarian point: “AI gateway” may be a product-marketing label before it is a monetizable category, and Wi-Fi 8 timing could defer broad adoption. The thesis improves with multiple operator deployments and measurable service-cost or retention benefits; it weakens if launch slips, features remain cloud-dependent, or operators decline the premium. No company-specific earnings sensitivity can be inferred from the announcement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not add QCOM solely on this announcement; treat it as product validation rather than an estimate-changing catalyst. No near-term position is warranted absent scale or financial disclosure.
- Set an alert for production deployment timing, follow-on operator wins, and evidence of paid software or premium gateway pricing. These are the missing inputs needed to underwrite revenue and margin contribution.
- For existing QCOM exposure, retain the thesis only if subsequent disclosures show broader adoption; reassess if deployment slips beyond 2027 or operator commitments remain limited to the launch partner.
- Track operator economics alongside adoption: evidence of lower support costs, reduced churn, or paid feature uptake would support the premium-gateway case; otherwise, added hardware and security complexity may be absorbed without attractive returns.
More News
- Arm shares fall after jury rules in favor of Qualcomm in license dispute
- Delaware jury awards Qualcomm $2 in damages, finds Arm breached license agreement
- US fines Bank of America $1.2bn for money laundering, sanctions violations
- South Korean carmaker Hyundai plans 'strategic' investment of $15.5 billion in India by 2032
- Applied Materials’ $5 billion AI lab aims to cut chip development time in half—and restore Silicon Valley’s edge
- China's exports likely grew by double-digits in September