
Zerova präsentiert seinen MCS-Dispenser auf der IAA TRANSPORTATION 2026 erstmals in Europa
Source: PR Newswire
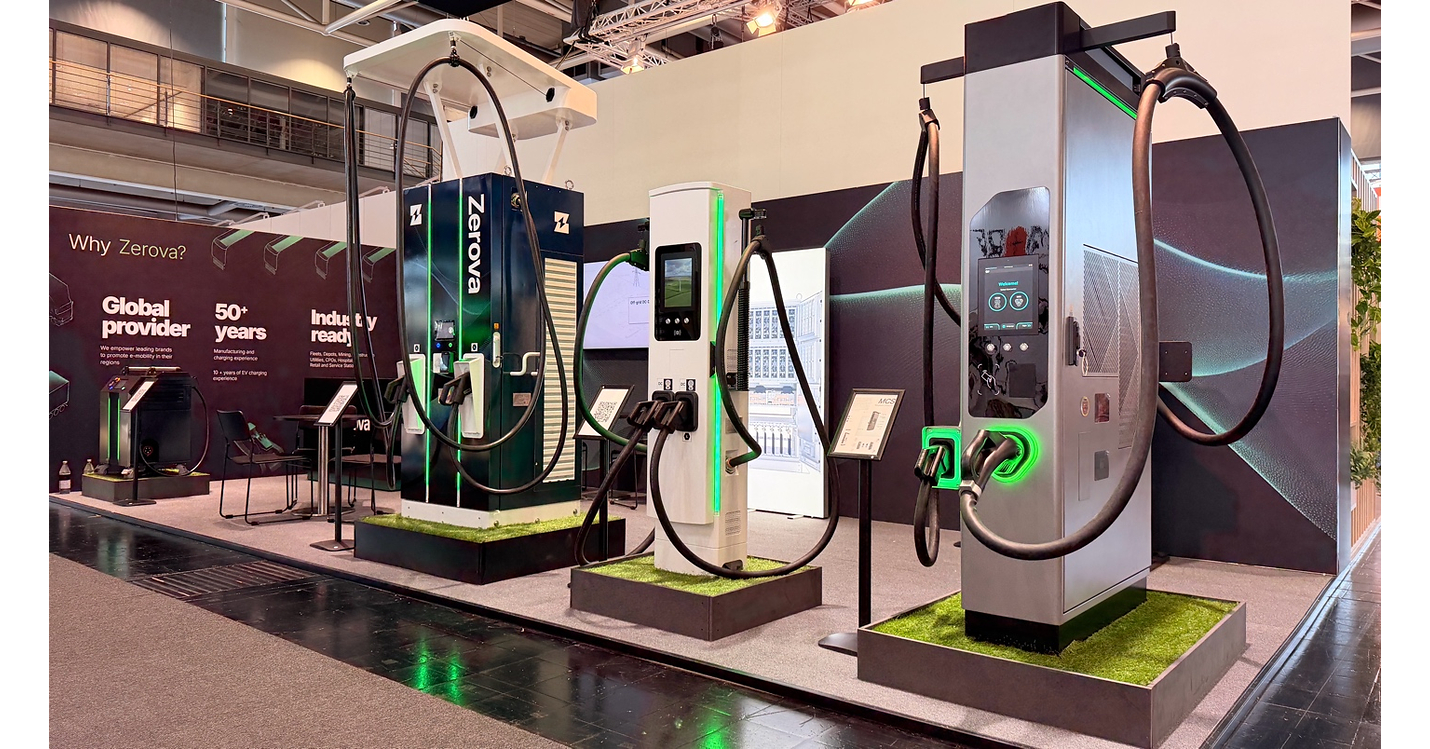
Zerova launched its MCS Dispenser in Europe at IAA Transportation 2026, targeting fleet electrification for heavy-duty trucks and buses. The satellite DC charger delivers up to 1,440 kW and 1,500 A through liquid-cooled cabling, supporting both MCS and CCS2 connectors. The platform is designed for depot and highway-corridor deployments, with OCPP 1.6J/2.0.1 interoperability and EU/EEA compliance as megawatt charging infrastructure expands.
Analysis
This is not independently investable as a Zerova-specific event, but it reinforces that the value pool in heavy-duty electrification is shifting from vehicle hardware toward depot power architecture, grid interconnection, and managed charging. ABB, Schneider Electric (SU.PA), Siemens Energy (ENR.DE) and Eaton (ETN) have broader exposure to switchgear, transformers, power conversion and site engineering; these components can command better service revenue and lower warranty risk than the charger dispenser itself. The near-term constraint is unlikely to be charger availability: multi-megawatt depots require lengthy utility studies, medium-voltage equipment and capacity upgrades, making grid-equipment order flow the more investable 6-18 month read-through.
Public charging pure-plays should not automatically rerate on MCS announcements. Higher-power systems raise thermal-management, uptime, utilization and demand-charge exposure; low initial truck utilization can make asset returns unattractive even where fleet demand is real. Kempower (KEMPOWR.HE) is the closest listed European charging peer but faces intensified pricing competition as established electrical OEMs bundle chargers with site power systems. The key 1-3 month catalyst is evidence of contracted installations with named fleet customers and utility connection dates, rather than trade-show product specifications; absent this, the announcement has limited earnings relevance.
Contrarianly, MCS standardization may compress the differentiated hardware opportunity by reducing switching costs and making dispensers more interchangeable. The beneficiaries may therefore be operators with secured grid capacity and fleet contracts, including private-depot integrators, rather than charger manufacturers. Monitor Daimler Truck (DTG.DE), Volvo AB (VOLV-B.ST) and Traton (8TRA.DE) order commentary: sustained battery-electric heavy-truck backlog growth would validate infrastructure demand, while deferred fleet orders due to connection delays would favor a short-duration, selective approach to charging-equipment exposure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- Maintain a 6-18 month overweight bias toward ETN and SU.PA versus pure-play charging OEMs: seek exposure on broad industrial pullbacks, as grid interconnection and electrical-balance-of-plant content should capture a larger and more durable share of heavy-duty charging capex. Falsifier: European utility-capex guidance or medium-voltage order backlog weakens materially.
- Use a relative-value watch: long ETN or ABBN.SW / short KEMPOWR.HE only after MCS-related customer awards begin to lift charger valuations without corresponding disclosed utilization, gross-margin or service-backlog improvement. Target a 10-15% relative move over 3-6 months; cover if Kempower reports contracted multi-year service revenue or margin expansion despite price competition.
- Do not initiate a directional position in charging pure-plays from this product launch alone. Upgrade only if announced European installations include binding fleet volumes, funded grid connections and commissioning dates within 12 months; these data points determine whether hardware shipments convert into recurring utilization and service economics.
- Track DTG.DE, VOLV-B.ST and 8TRA.DE quarterly for electric-truck order intake and delivery timing. A sequential acceleration in BEV orders alongside disclosed depot-connection commitments would support adding infrastructure exposure; order delays attributed to charging or grid readiness would invalidate the near-term demand thesis.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- US official says upcoming spectrum auctions could generate more than $100 billion
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- Oil Extends Slump as Saudi Arabia Moves to Restore Key Pipeline
- AI Buildout Hits Inflation as Fed Hikes Rates
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can ChatGPT or Claude Replace a Research Platform?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance