
Paul Mueller: Betting On The Reshoring Of Pharma Manufacturing
Source: seekingalpha.com
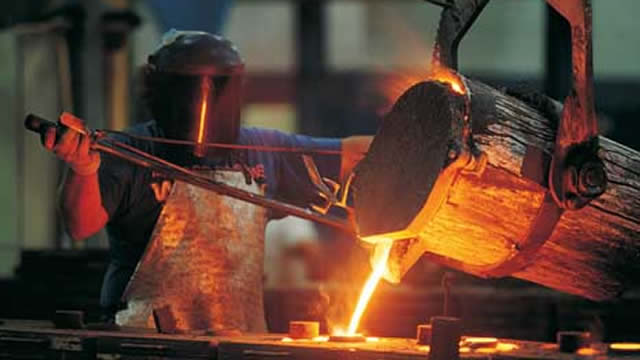
Paul Mueller's Q3 revenue rose 50.6% year over year to $92.5M, while gross margin expanded to 30.5% and net margin to 12.6%. Pharma modular systems and U.S. reshoring trends are supporting growth, and backlog remains near record levels; however, cash flow turned negative amid working-capital needs and heavy capex.
Analysis
The key underwriting question is whether the growth is converting into durable cash earnings, not whether demand is currently strong. A large backlog can support near-term factory utilization, but it is not equivalent to profitable revenue: project timing, customer acceptance, and working-capital intensity can delay cash realization. If capex and inventory/receivables continue to absorb cash, reported margin expansion may overstate the near-term improvement in owner earnings and could constrain the company’s ability to add capacity without further funding. Over the next 1–3 months, the most useful signals are operating cash flow, backlog conversion and cancellations, and whether incremental capex produces throughput rather than merely higher fixed costs. Over 6–18 months, sustained U.S. pharma and bioprocess investment could support specialized equipment demand, but the benefit is conditional on continued customer investment and successful execution. Competitors such as Alfa Laval, GEA Group, and SPX Technologies may face stronger bidding pressure if capacity expands, while suppliers of stainless-steel components could benefit from higher equipment volumes but remain exposed to input-cost pass-through. The contrarian risk is extrapolating one strong quarter into a new earnings run rate: project-based demand can be lumpy, and cash conversion is the test. A reversal in bookings, backlog quality, or cash generation would weaken the thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.50
Key Decisions for Investors
- No directional position in Paul Mueller on this information alone: first verify investability, trading liquidity, valuation, and the durability of backlog conversion; the supplied data does not establish those points.
- Set a next-quarter alert for operating cash flow, receivables/inventory growth, capex, and backlog cancellations or deferrals. Persistent cash outflow alongside continued capex would argue against treating margin gains as fully bankable.
- For a 1–3 month catalyst view, favor a watchlist rather than a sector-wide long: seek evidence that bookings and backlog are translating into shipments and cash, not just reported revenue. Compare order commentary and execution trends at Alfa Laval, GEA Group, and SPX Technologies before inferring broad-based industry strength.
- Falsify the constructive view if management indicates weaker order intake or material project delays, or if cash conversion deteriorates despite continued margin expansion; conversely, improving cash generation without a step-up in capex would strengthen the case for durable operating leverage.
More News
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- The Strait of Hormuz closure has cost Europe an extra $142 billion for the same energy it was already buying
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- Opening Statement before the House of Commons Standing Committee on Finance