
Lavior Promotes Ashlyn Tapley to Vice President of Sales
Source: PR Newswire
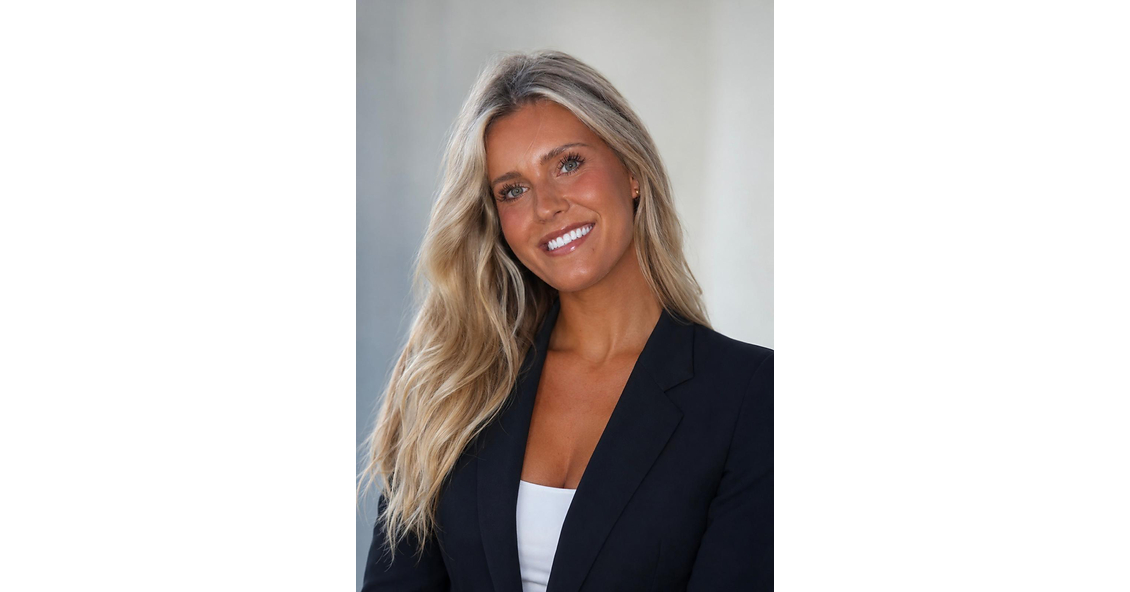
Lavior promoted Ashlyn Tapley from National Sales Director to Vice President of Sales, assigning her leadership of U.S. sales strategy, business development, and select international markets. The botanical wound- and skin-care company is targeting expanded clinician, skilled-nursing, DME, distributor, physician-direct, and retail relationships, supporting its stated U.S. and global growth ambitions. The announcement contains no financial results, guidance, or quantified commercial targets.
Analysis
This is not a tradable public-markets catalyst absent evidence that Lavior is publicly listed, has a disclosed funding event, or supplies a listed healthcare company. A sales-leadership promotion does not establish incremental reimbursement, formulary access, clinical differentiation, manufacturing capacity, or distributor economics—the variables that determine whether a wound-care product can scale beyond regional channels.
The more relevant read-through is competitive pressure at the low-acuity diabetic wound and skin-protection edge, where sales execution can marginally affect local purchasing behavior but is unlikely to alter earnings for diversified incumbents such as Solventum (SOLV), Smith+Nephew (SNN), Mölnlycke (private), or Organogenesis (ORGO). Expansion toward physician-direct and retail channels could face margin dilution: customer acquisition, distributor rebates, returns, and consumer-marketing spend are typically higher than institutional wound-care selling, while reimbursement support is less certain.
Over the next 1-3 months, treat any claimed commercial acceleration as unverified until there are disclosed provider contracts, Medicare/DME reimbursement coding support, peer-reviewed outcomes data, and repeat-order metrics. Over 6-18 months, a credible botanical alternative could matter only if it demonstrates lower total cost of care—faster closure, fewer infections, or reduced clinician time—rather than merely product-level efficacy. The thesis is falsified for any competitive concern if adoption remains confined to independent representatives without national distribution, reimbursement validation, or measurable reorder velocity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No position: do not infer a public-equity catalyst from this announcement; confirm Lavior's ownership structure, financing history, and any listed distributor or strategic partner before assigning a tradable read-through.
- Place ORGO on a 6-12 month competitive watchlist rather than shorting: monitor diabetic-wound revenue growth, gross-margin guidance, and customer concentration for evidence that lower-cost topical substitutes are affecting utilization. A standalone personnel announcement is insufficient signal.
- For SOLV and SNN, maintain existing fundamental views; reassess only if Lavior announces a national GPO/distributor agreement, reimbursement milestone, or controlled clinical data showing superior healing economics. Those events—not sales titles—would be the potential catalysts for localized pricing pressure.
More News
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying
- The Tiny Magnet Maker That Attracted $1.6 Billion From Lutnick
- Wall Street Week | China’s Trade Reckoning, Syracuse’s Second Chance, Humanoids in Healthcare
- ‘U.S. trade policy is damaging the U.S. auto industry’: Canada’s purchase of American cars hits new low as Trump’s tariffs backfire on U.S. automakers
- Yields keep rising, Novo's tough week, why cat product sales are surging and more in Morning Squawk
- Beware borrowing costs: The jump in yields could hit these debt-laden stocks the most