
CordenPharma ernennt Dr. Jean-Luc Herbeaux zum Geschäftsführer für die nächste Wachstumsphase
Source: PR Newswire
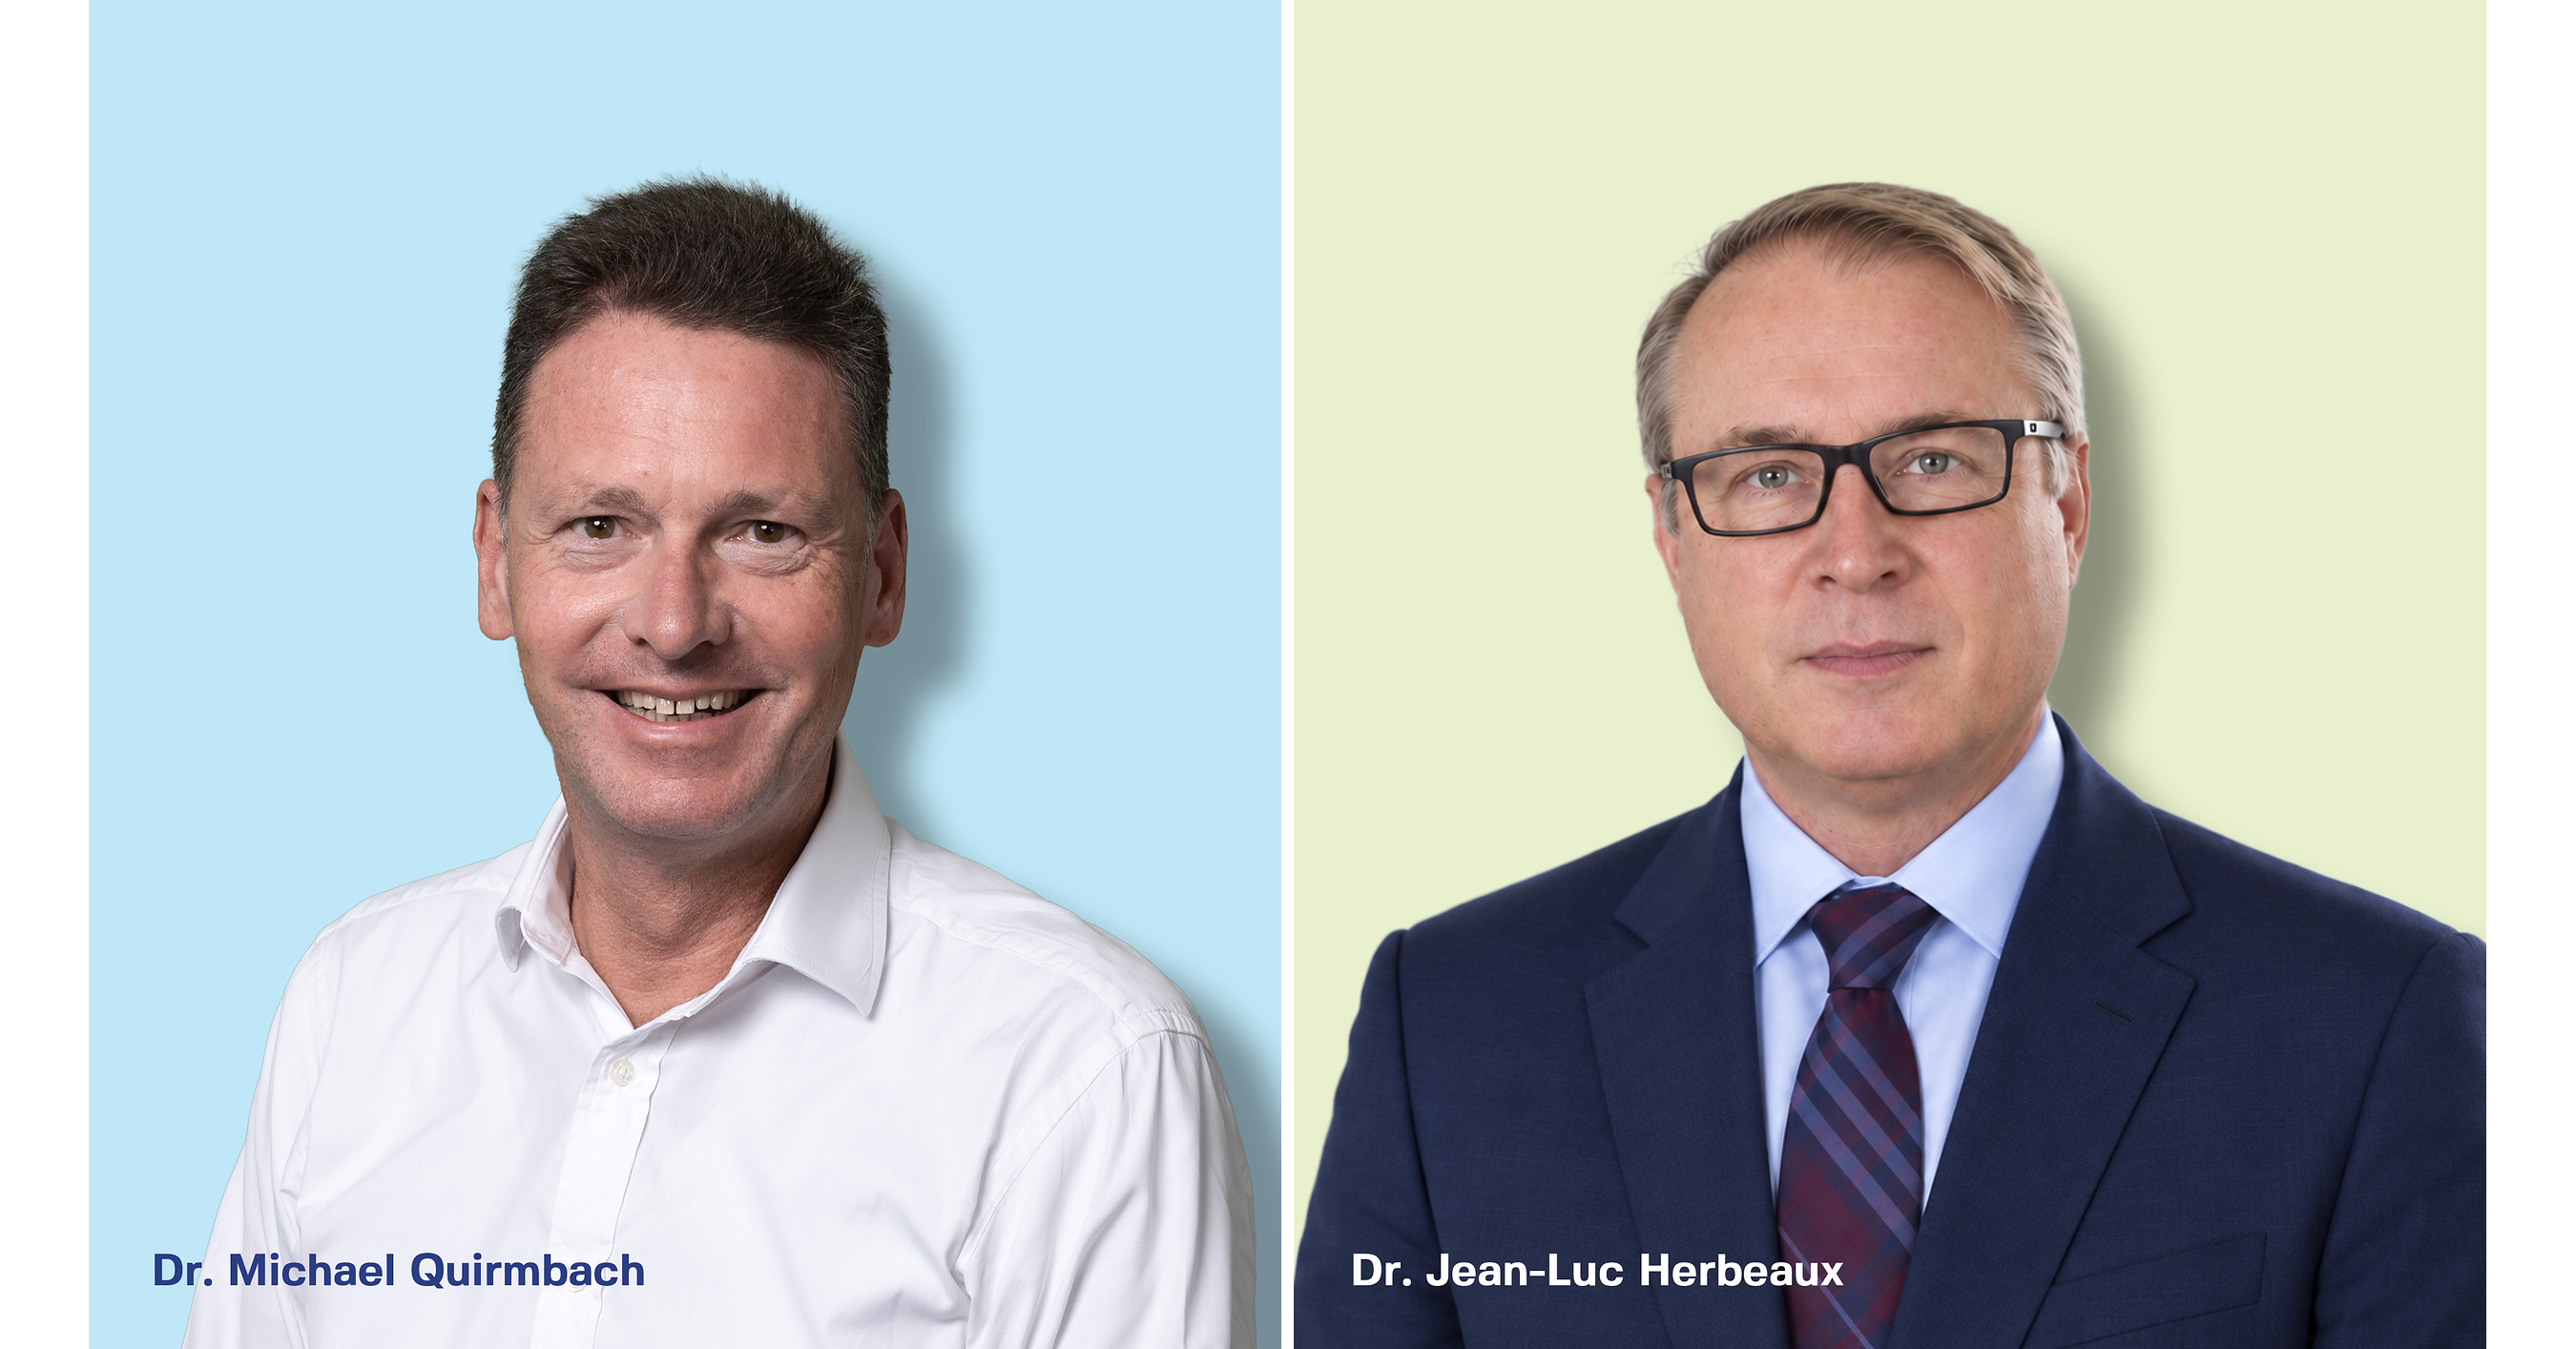
CordenPharma appointed Jean-Luc Herbeaux, formerly CEO of Hovione, as CEO effective October 1, 2026, succeeding Michael Quirmbach, who will remain a board member and senior adviser. The planned transition follows 12 years of expansion in which annual revenue grew from €245 million to more than €1 billion; FY2025 revenue was €960 million. The company is positioning for further growth following its AmbioPharm acquisition and investments in global development and manufacturing capacity.
Analysis
This is not a direct EVK earnings catalyst: the executive’s prior tenure at Evonik is historical, and there is no disclosed commercial linkage, contract transfer, or financial exposure. The relevant read-through is instead competitive: a CordenPharma CEO with operating experience across specialty chemicals and CDMO manufacturing could raise execution intensity in high-value modalities where EVK’s Health Care unit participates, particularly lipid excipients/LNPs and complex drug-delivery inputs.
Near term, the announcement is unlikely to move listed CDMO or specialty-ingredient valuations; it is a planned succession with continuity retained at the board level. Over 6-18 months, the more material question is whether Corden’s expanded peptide platform translates into faster capacity utilization and more aggressive customer bidding. That could incrementally pressure peers with less differentiated capacity, while favoring suppliers of regulated, scarce inputs if customer programs reach commercial scale.
The contrarian view is that private-equity-backed CDMO expansion is often mistaken for immediate demand creation. New capacity can dilute returns when biotech funding, clinical conversion, or launch volumes disappoint; management credibility alone does not resolve utilization risk. For EVK, the thesis only becomes investable if subsequent disclosures show Health Care order growth, improved mix, or higher-margin lipid/LNP volumes rather than generic optimism around outsourced pharma manufacturing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate EVK position change; treat this as a watch item rather than a tradable catalyst given the absence of disclosed revenue, supply, or contractual linkage.
- Monitor EVK’s next two reporting cycles for Health Care organic growth, divisional margin progression, and commentary on lipid/LNP utilization. A sustained acceleration versus group growth would support a 6-12 month EVK overweight; lack of margin conversion would falsify the competitive read-through.
- For CDMO exposure, prefer listed, differentiated platforms such as LONN.SW or VTRS-adjacent outsourced-manufacturing beneficiaries only after evidence that peptide/oligonucleotide order books are converting into commercial volumes; avoid treating announced capacity or leadership changes as proof of demand.
- Set an alert for new Corden customer wins, plant commissioning delays, or pricing commentary from peers. Evidence of discounting or underutilization would be a negative read-through for the broader complex-therapy CDMO cohort, not a specific EVK short signal.
More News
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- Analysis: How Trump could reignite the Fed independence fight after Warsh's rate hike
- Fed delivers its first hike in 3 years. Plus, what's moving Starbucks and GE Vernova
- Status Of Anthropic IPO As AI Fears Mount
- Snap tries to bring AR glasses to enterprise market, partnering with Nvidia, AWS and Salesforce
- Harold Hamm’s Continental Set to Announce Venezuela Oil Deal