
BYD Challenges Hyundai’s South Korea Dominance With EV Expansion
Source: Bloomberg
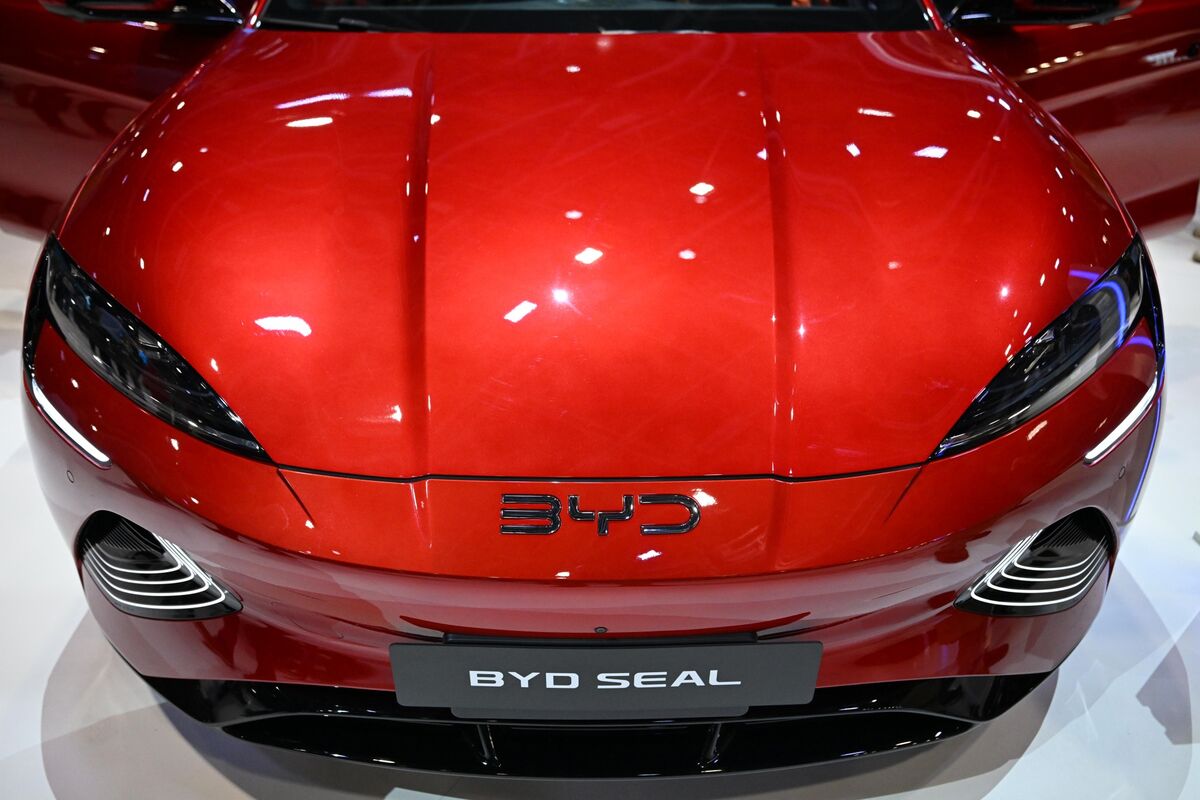
BYD is expanding into South Korea, targeting Hyundai and Kia’s home market with competitively priced electric and hybrid cars. The article describes South Korea as a difficult market for foreign automakers but gives no sales figures, financial impact, or market reaction.
Analysis
The investable question is not whether BYD can enter Korea, but whether it can force Hyundai and Kia to defend share with discounts. If incumbents respond through incentives rather than losing volume, the first-order effect could be margin dilution before it appears in headline sales. A sustained foothold would also challenge the assumption that domestic brand loyalty reliably protects pricing in a mature auto market; that signal could matter more to regional competitive expectations than Korea’s near-term unit contribution.
The counterpoint is that a launch or early sales momentum does not establish durable economics. Service coverage, resale values, customer acquisition costs, and any policy or distribution friction could limit repeat purchases and constrain expansion. Over days, this is likely a sentiment headline, not a standalone earnings catalyst. Over 1–3 months, watch registration/share data, incentive intensity, and Hyundai/Kia commentary. Over 6–18 months, the key test is whether BYD can build an aftersales ecosystem while maintaining competitive pricing—and whether incumbents export defensive pricing to other markets.
The article provides no sales, pricing, or margin data to quantify exposure. Treat any near-term read-through as conditional; do not infer a material earnings hit from market entry alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No immediate directional trade: the evidence is too thin to justify shorting Hyundai or Kia on a market-entry headline. Reassess if Korean registrations show sustained share gains alongside rising incentives or weaker realized pricing.
- Set an alert for Hyundai and Kia earnings commentary and monthly Korean registration data over the next 1–3 months. Falsification: BYD registrations remain marginal, or incumbents retain share without increased discounting.
- If competitive pressure becomes measurable, consider a relative-value underweight in the more exposed incumbent versus a broad auto basket rather than a broad sector short; confirm model-level overlap, incentive trends, and valuation first.
- Watch for policy, dealer/service expansion, and resale-value evidence over 6–18 months. These determine whether the entry becomes a repeatable competitive threat or remains a limited launch.
More News
- From Wall Street to Silicon Valley, Anthropic IPO poised to have massive 'trickle-down effect'
- A shock in Brazil sends stocks plunging, while neoclouds take another hit
- Anthropic’s IPO filing shows explosive growth, risks and staggering costs
- Microsoft offers buyouts to nearly 30% of workforce in ongoing AI shift
- Elon Musk warns more than 200 AI cloud companies face ‘guppy-level death’ as the AI boom runs into a debt crisis
- China’s industrial profit growth picks up amid deepening economic divergence