
Youku's 'The Early Spring' Reaches No. 2 on Netflix's Global Non-English TV List
Source: PR Newswire
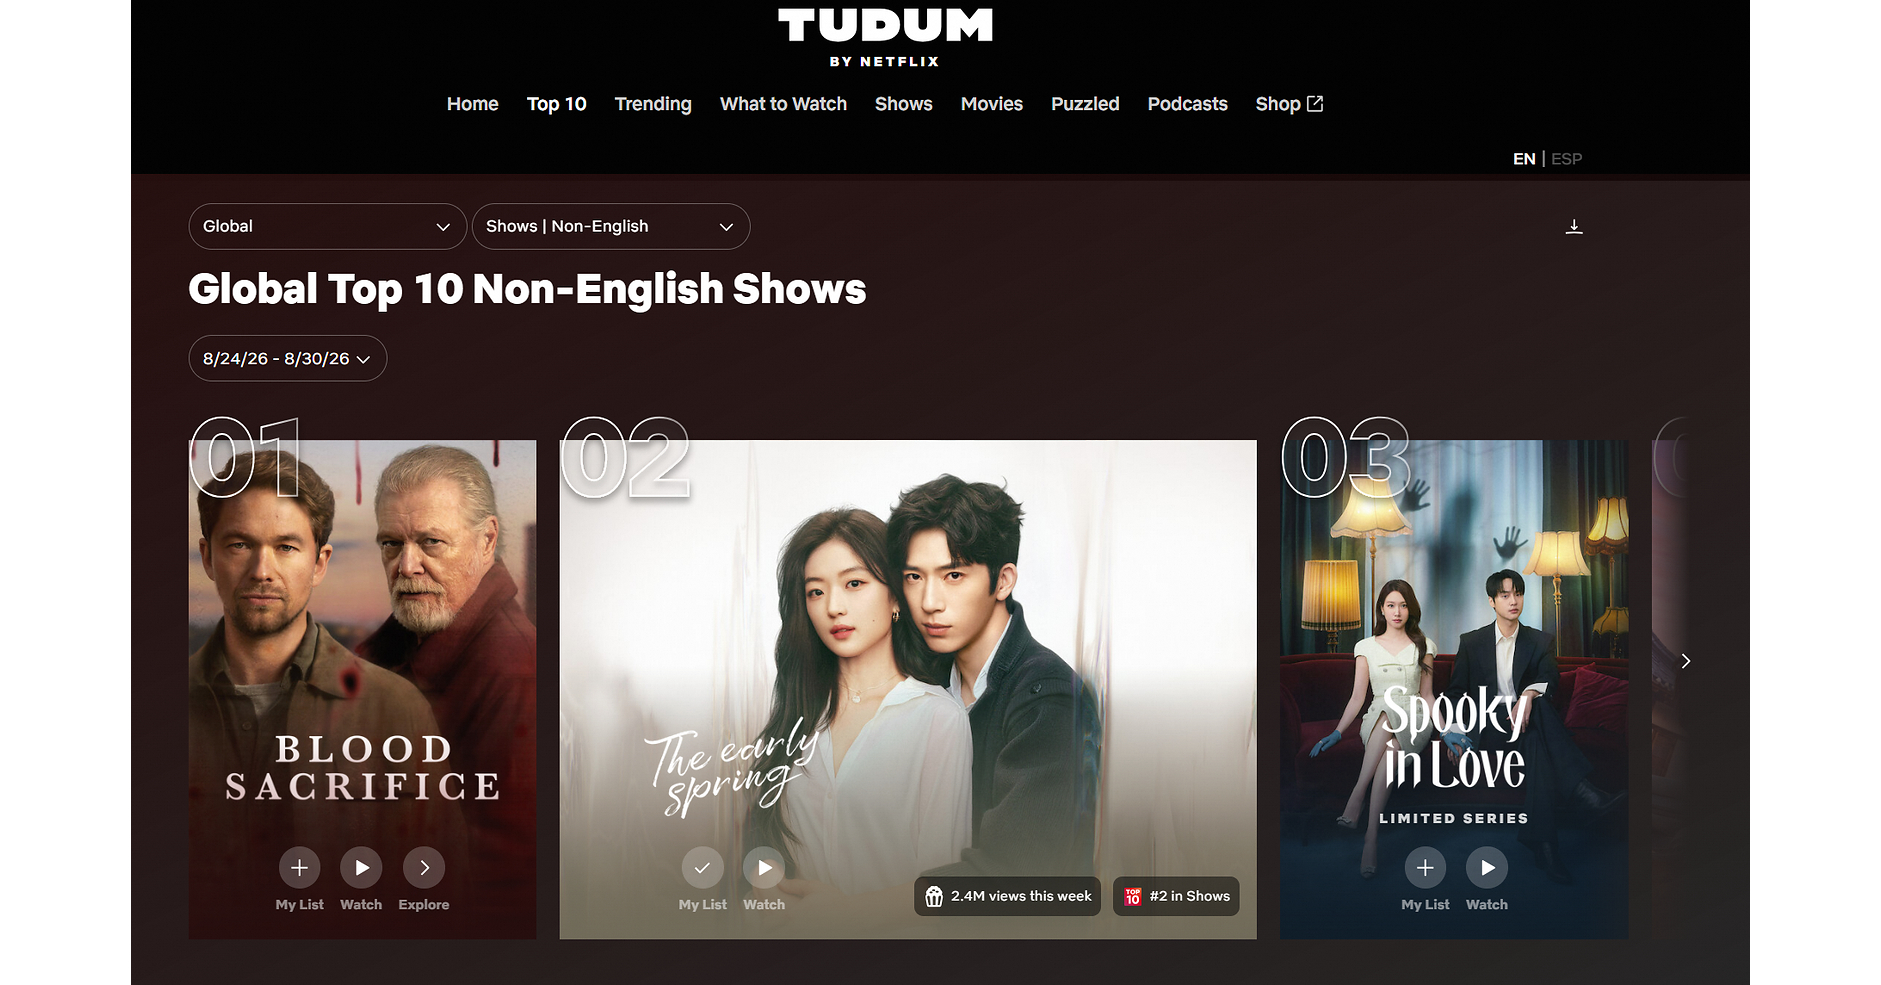
Youku’s workplace romance “The Early Spring” hit No. 2 on Netflix’s Global Non-English TV list for Aug. 24-30, with 2.4M views and 21.5M hours viewed on Netflix in just five days (No. 6 on the global daily chart within two days). The series also reached Netflix Top 10 across 22 markets and topped TV charts in Hong Kong/Taiwan, Thailand, and Vietnam, signaling continued momentum for Youku’s original-content strategy. Overall impact is likely limited to incremental brand/content traction rather than a broad market move.
Analysis
This is more useful as a signal on content optionality than as a direct earnings event. For BABA, the economic lever is not the view count itself; it is whether Youku can repeatedly export low-cost IP that improves engagement, ad load, and retention without a matching rise in content spend. If that loop works, the upside is incremental margin leverage in China media, but the contribution is still too small to matter for consolidated valuation unless management can show sustained monetization, not just chart placement.
NFLX is the cleaner structural beneficiary because globally traveling non-English content reduces acquisition risk and improves library efficiency. That strengthens the case for a platform model where international discovery lowers the need for expensive proprietary production in every market, while smaller regional streamers and local broadcasters face a harder competitive set. Second-order, successful Chinese dramas may raise the licensing value of Asian content libraries, but they also increase bargaining power for top IP owners rather than the platform that originated them.
The key risk is extrapolation: one breakout title does not prove a durable export franchise. The thesis weakens if the next 2-3 Youku originals fail to repeat the international traction or if the platform’s monetization metrics stay flat despite stronger heat indices. Over 1-3 months, the market may overread the headline; over 6-18 months, repeatability and ad/subscription conversion will decide whether this is a real competitive edge or just a one-off distribution win.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not chase BABA on this print; treat it as a watch item until the next quarterly report shows Youku engagement translating into higher ad revenue or paid-user growth. Falsifier: no improvement in China media monetization metrics over the next 1-2 quarters.
- If BABA pulls back after an initial pop, use a small 3-6 month call spread rather than stock: the setup is convexity on repeatable content export, not a full re-rating. Risk/reward is attractive only if management can show a second hit quickly.
- Relative value: long NFLX / short KWEB for 1-3 months as a modest expression of global-content scalability versus China internet beta. Thesis breaks if Netflix non-English chart performance fades or if China internet sentiment is driven by macro rather than content fundamentals.
- Set an alert on Youku’s next two originals and any disclosure of ad ARPU or membership growth; if the pipeline does not convert, fade the narrative and rotate back to core Alibaba fundamentals.
More News
- If I Could Own Only 1 "Magnificent Seven" Stock for the Next 10 Years, It Would Be This One.
- These 6 retro sites let you relive the glory days of 2000s Flash games
- Asian stocks skid, Wall Street and bonds aided by oil slip
- Here are the 3 big things we're watching in the stock market this week
- What to Expect in Markets This Week: Meta, Tesla Report; Airlines, Streaming Giants' Results Due
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount