
Lockheed Martin: Strong Buy, But Not For The Obvious Reasons
Source: seekingalpha.com
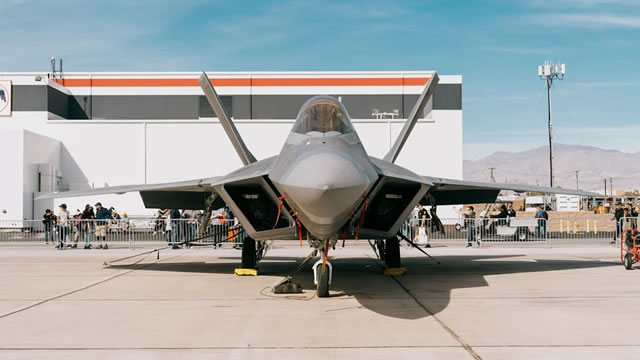
Lockheed Martin was upgraded to Strong Buy, with the analyst citing 28–40% upside because current share prices do not reflect 2024 or 2025 earnings. Record backlog, missile defense demand, and the Ultra Maritime acquisition support multi-year growth, while supply-chain constraints and investment needs limit near-term margin upside. Recent share-price declines are attributed to sentiment and earnings-yield pressure rather than weakening earnings or demand fundamentals.
Analysis
The upgrade is a valuation thesis, not evidence of a near-term earnings inflection. The key market mechanism is whether backlog converts into funded deliveries and cash flow quickly enough to offset supply-chain friction, investment needs, and acquisition integration costs. Until that conversion is visible, investors may continue to price LMT more like a long-duration income stock—leaving it exposed to higher real yields—even if demand remains intact. A further second-order risk is that constrained suppliers and labor can absorb incremental defense spending before it reaches prime-contractor margins.
Over days, the upgrade may support sentiment, but the 28–40% upside claim is not independently testable here: verify the underlying earnings estimates, valuation assumptions, and cash-flow bridge before underwriting it. Over 1–3 months, earnings, guidance, and evidence of delivery/margin execution matter more than backlog headlines. Over 6–18 months, successful conversion and integration could support estimates; persistent cost pressure or weaker funded orders would undermine the rerating case.
Contrarian angle: the market may be over-penalizing sentiment and yield sensitivity, but the article may understate how long operational bottlenecks can defer cash realization. No trade should rely on the headline upside alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Consider a staged, modest long in LMT rather than chasing the upgrade; add only if reported delivery growth and free-cash-flow conversion support the earnings case.
- Before sizing, verify consensus 2024–2025 estimates, valuation multiples, guidance, funded-order trends, and the acquisition’s expected contribution and integration costs. These are missing inputs, not established facts in the article.
- Use the next earnings and guidance updates as 1–3 month catalysts. Reassess or cut the thesis if margins or free cash flow weaken despite revenue growth, funded orders soften, or management lowers delivery expectations.
- For a relative-value expression, pair a small LMT long with a short position in a diversified defense-sector proxy to isolate company execution from rates and sector sentiment; avoid the pair if broad defense exposure is the intended bet.
More News
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- Authorities said Houthi-claimed attacks on Riyadh airport killed three Saudi citizens, as airlines suspend at least 124 flights
- Rising fuel costs slashed Delta’s profit outlook despite strong demand
- Wall Street Week | Michigan Manufacturing, AI Debt Investments, Baby Bonds, Canadian Coal Fight
- OpenAI's revenue scare, Delta earnings, what investors think of a Starbucks-Chipotle deal and more in Morning Squawk
- Delta Cuts Profit Outlook as Surging Fuel Costs Tighten Grip