
First Look: New Luxury Amenities at RT500 Unveiled as Leasing Momentum Builds at The Park in Berkeley Heights, NJ
Source: PR Newswire
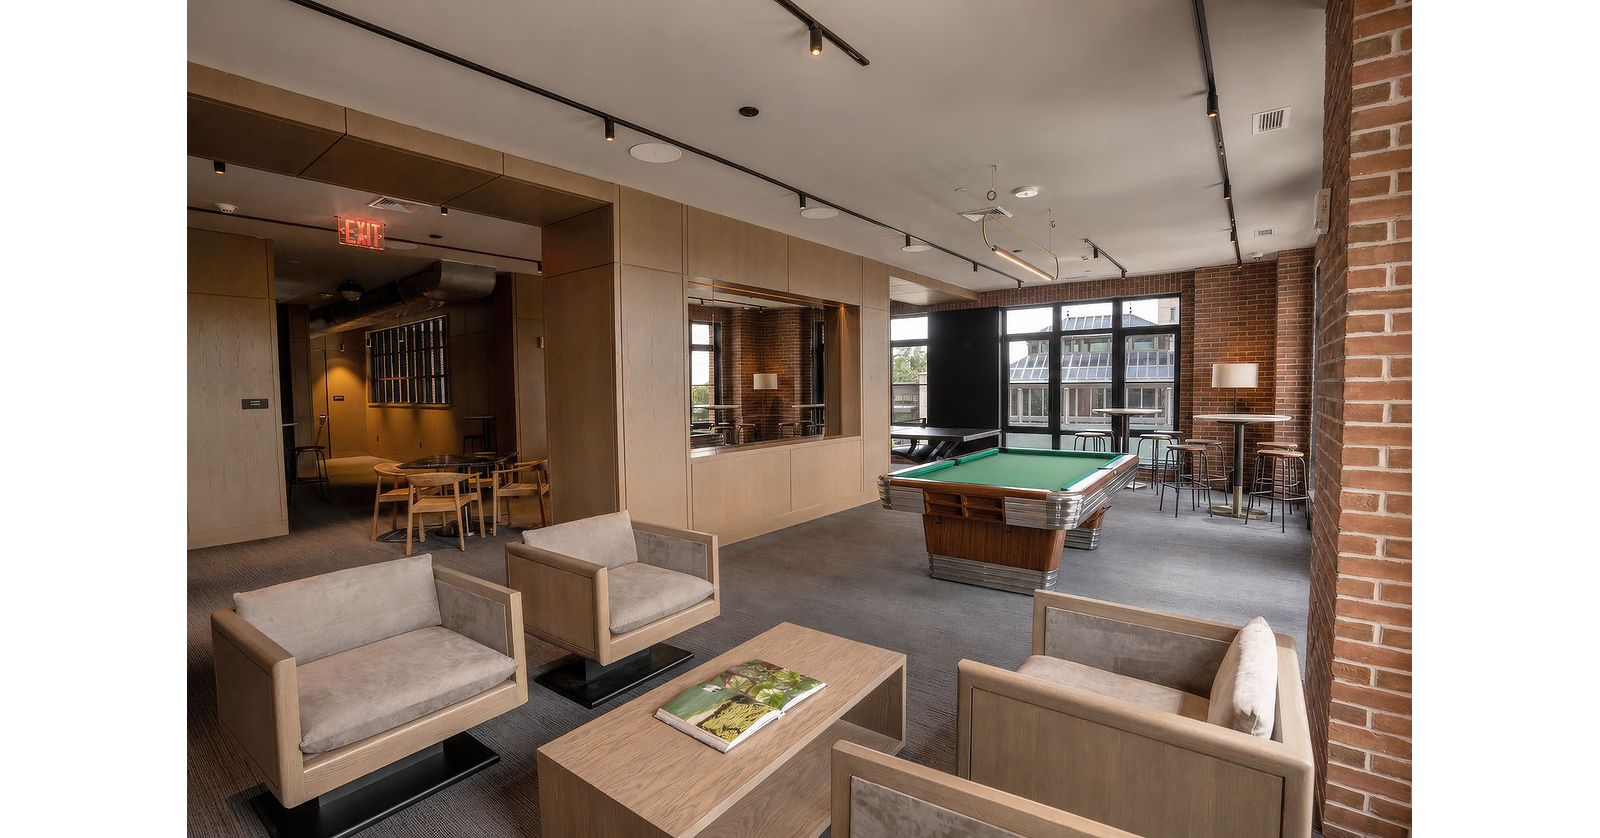
RT500, a 179-unit luxury residential tower in The Park (Berkeley Heights, NJ), began move-ins on Aug. 1 as leasing activity continues to build. The 11-story community is positioned within a 185-acre mixed-use redevelopment and highlights amenity expansion (including a dedicated co-working space and upgraded fitness/wellness facilities). The announcement signals ongoing demand and execution against The Park’s broader ~$500 million redevelopment plan, but it is unlikely to materially impact public market prices.
Analysis
This is less a direct earnings event than a proof point for the premium mixed-use model: the economics work only if the operator can convert amenity density into lower churn, faster absorption, and pricing power across housing, retail, and hospitality. The cleanest listed read-through is LTH, not because this specific asset moves its numbers, but because the campus design effectively markets Life Time-style wellness as a resident-retention tool. The second-order beneficiary is any landlord that can bundle daily-life services into one location; the loser is the commodity suburban apartment or office asset that competes only on rent.
Near term, the stock impact should be muted unless management can quantify occupancy, concessions, or NOI lift. The risk is that this is still a lease-up story dressed as a lifestyle story: if the pace of move-ins slows or incentives rise, the implied margin on the broader redevelopment could compress even as top-line leasing sounds healthy. Over 6-18 months, the real catalyst is whether the campus sustains enough foot traffic to support adjacent retail and hospitality revenue without excessive capitalized costs.
Contrarian view: consensus may be overweight the branding and underweight the capital intensity. A single trophy project in an affluent market does not prove that live-work-play can be replicated at acceptable returns elsewhere; the spread between construction cost and stabilized cap rate is the key variable. If rates stay elevated or leasing is only achieved through concessions, the model can look busy but still destroy economic value.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in PRK or the private developer on this release; wait for verified occupancy, concession, and stabilized NOI data before expressing a view.
- Use LTH as a conditional long only on pullbacks after evidence of improved member conversion/retention from co-located residential assets; 3-6 month horizon, with the thesis invalidated if management does not show measurable traffic or margin benefit.
- If forced to express the theme, run a small pair long LTH / short a commodity apartment REIT basket (e.g., EQR, AVB) for 1-2 quarters; the spread should work only if premium amenity demand keeps outpacing renewal pressure in standard multifamily.
- Prefer quality mixed-use/campus landlords over office laggards in any real-estate beta allocation; KRC is a cleaner beneficiary than VNO/SLG if the market starts rewarding amenity-rich occupancy resilience.
- Set a watch item on leasing economics: if concessions rise or move-in velocity stalls over the next 60-90 days, fade the narrative rather than chase it.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Solar power booms in Philippines as war on Iran spikes energy costs
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- Stock fixing scandal could see Turkish companies frozen out of global indexes
- Tesla is taking $250,000 deposits for a Roadster with SpaceX thrusters. The FAA says it isn’t an aircraft