
Lazard Hires Daniel Burton-Morgan As Head of Equity Capital Markets Advisory, North America
Source: PR Newswire
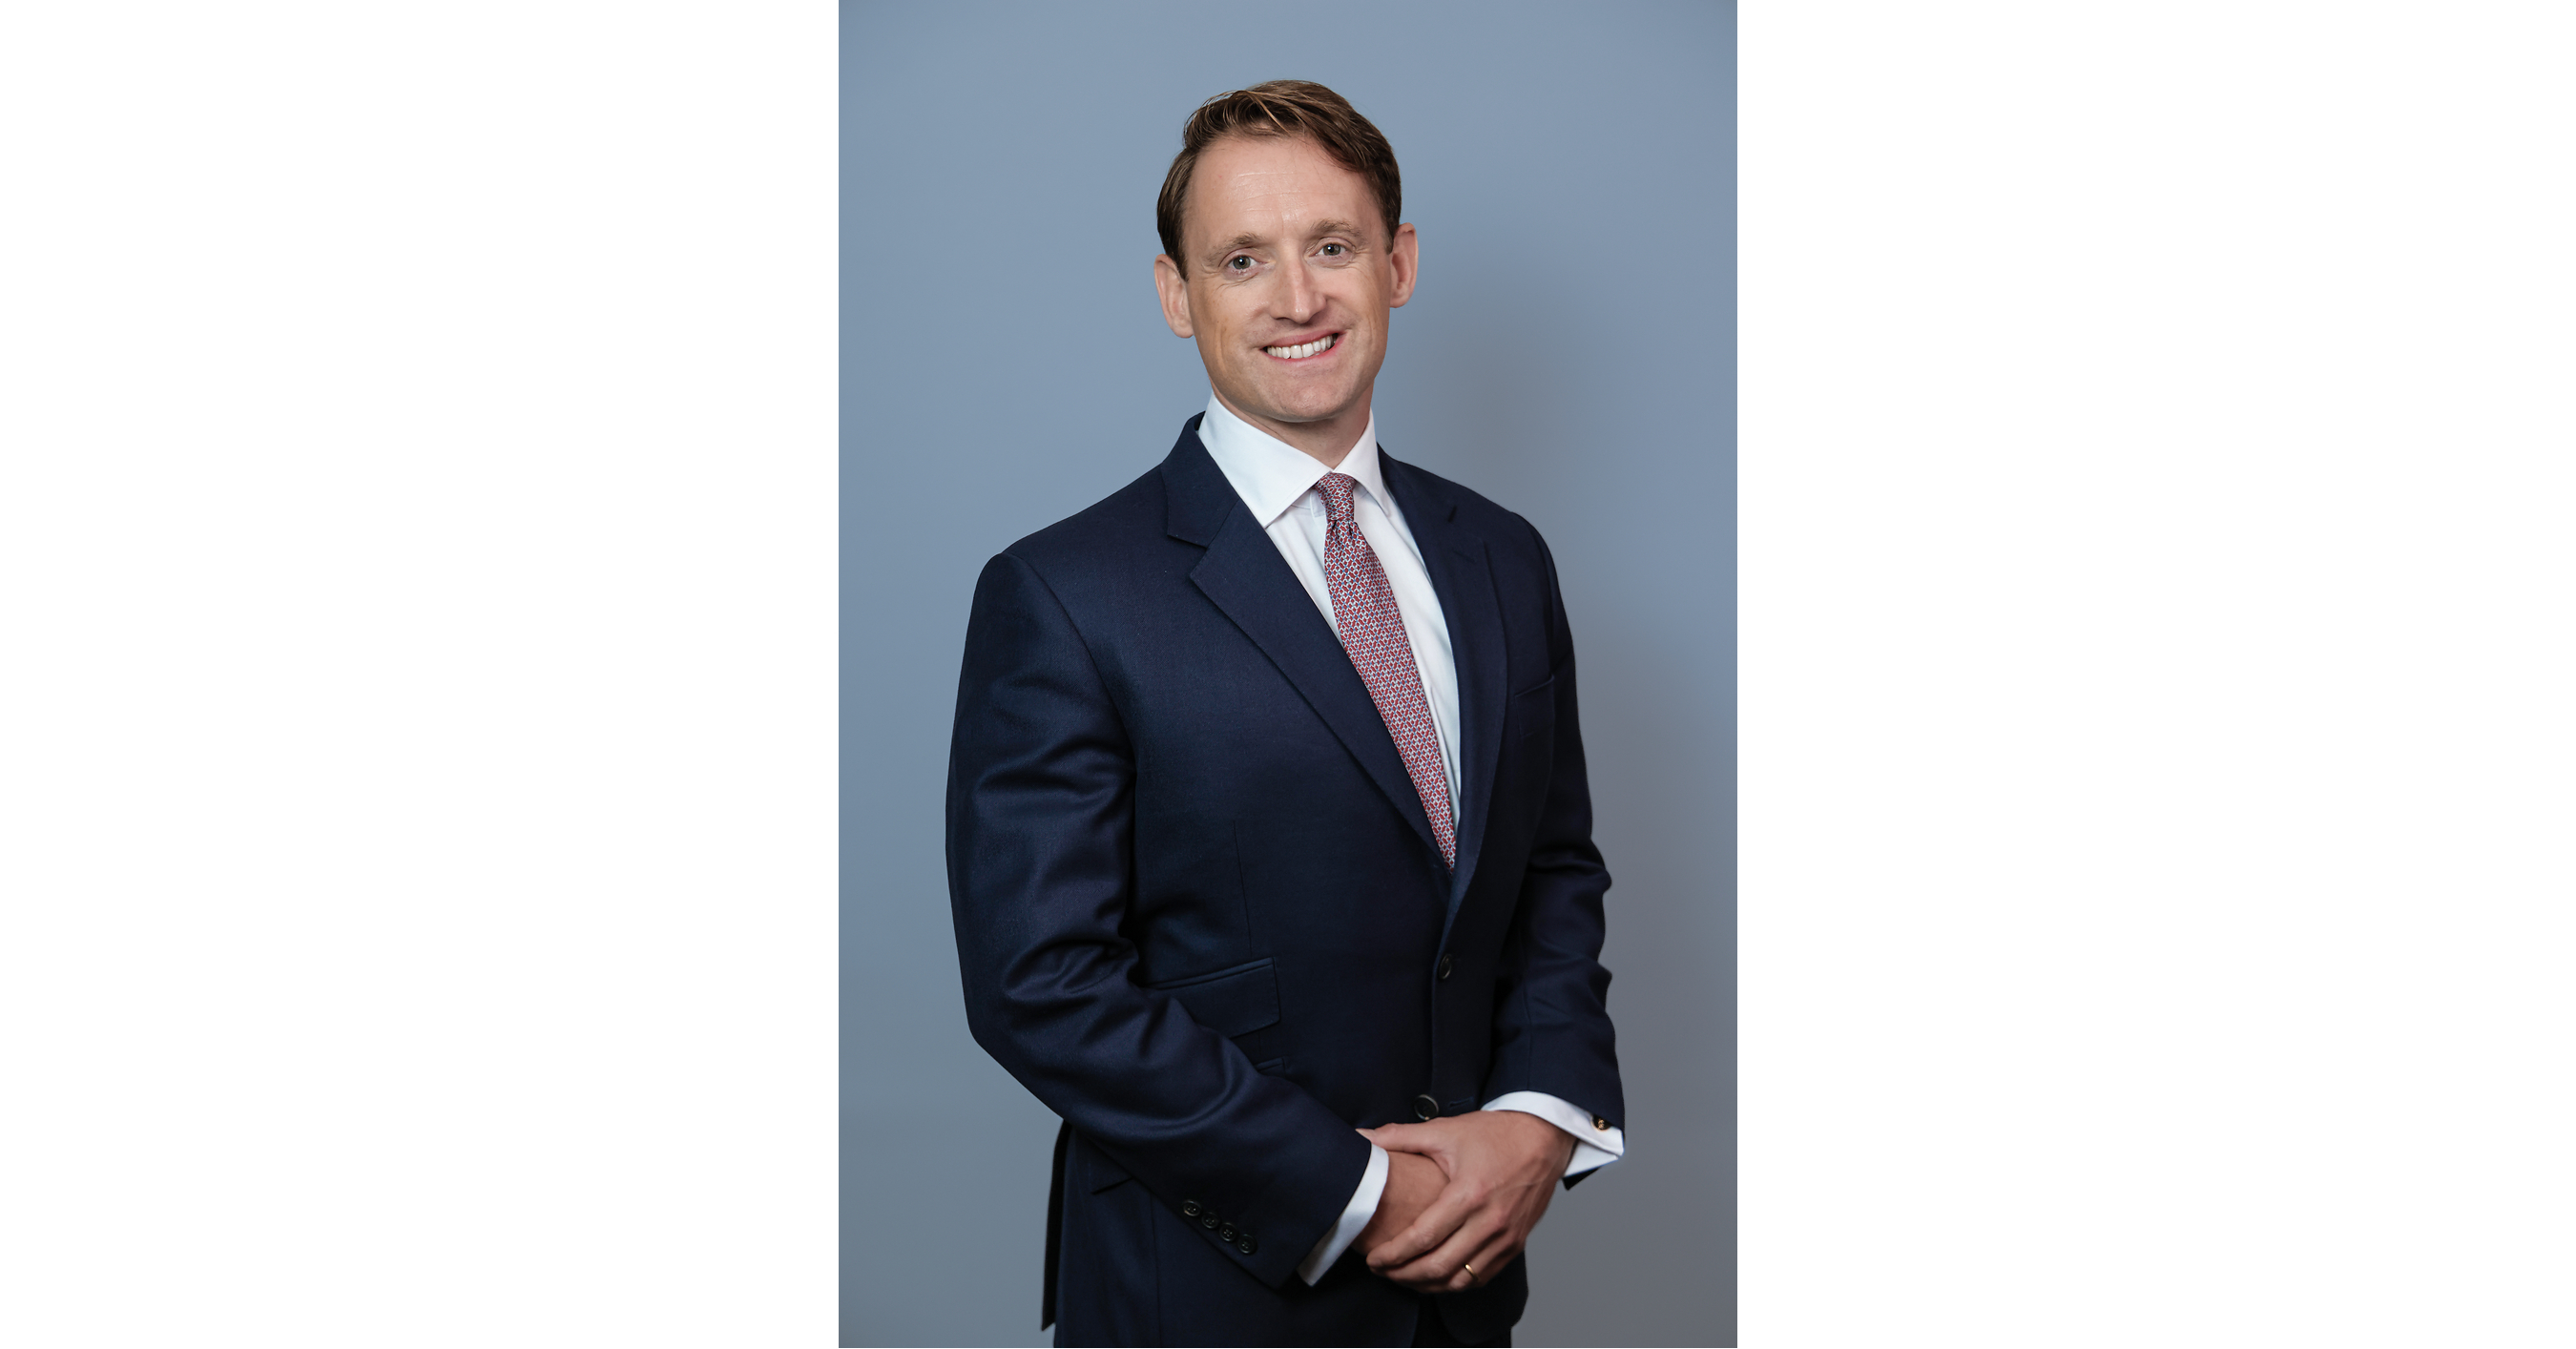
Lazard appointed Daniel Burton-Morgan as Managing Director and newly created Head of Equity Capital Markets Advisory, North America, expanding its Strategic Capital Solutions Group. Burton-Morgan joins from Bank of America, where he was Head of Americas ECM Financial Sponsor Origination, and will advise on IPOs, follow-on and secondary offerings, and block trades. The hire extends Lazard's established European ECM advisory capability into North America, but is unlikely to have a material near-term impact on LAZ shares.
Analysis
This is strategically sensible but immaterial to near-term LAZ earnings: a single senior hire does not alter advisory revenue until it converts sponsor relationships into mandates, likely a 6-18 month process. The relevant upside is less IPO underwriting economics than higher-value independent advice around secondary sell-downs, block trades and capital-structure decisions, where Lazard can cross-sell M&A, restructuring and shareholder advisory without committing balance sheet. Success would modestly reduce LAZ's dependence on episodic M&A fees and support a higher-quality advisory revenue mix.
The competitive implication is modestly negative for bulge-bracket ECM franchises such as BAC only at the margin. Lazard's independence is most differentiated when sponsor-backed issuers seek advice on timing, valuation and shareholder messaging separate from the underwriting syndicate; however, BofA and peers retain the decisive advantages in distribution, financing commitments and execution infrastructure. The hire is not evidence that LAZ can capture underwriting-like economics, and investors should not capitalize the announcement as a material market-share shift.
Near term, no standalone catalyst exists beyond evidence of team build-out or disclosed mandates. The thesis becomes investable only if LAZ's advisory fee backlog, compensation ratio, or management commentary indicates incremental Strategic Capital Solutions revenue without diluting firmwide margins. Falsification: no visible ECM mandate traction by the next two reporting cycles, or a compensation-ratio increase that absorbs any revenue contribution; either outcome would confirm the initiative is a cost center rather than a scalable fee pool.
Contrarian view: the more important signal may be defensive. Expanding into ECM advice can protect Lazard's client relevance during periods when M&A closes slowly but sponsor liquidity needs rise. Yet this also exposes the firm to a crowded market precisely as a reopened issuance window attracts universal banks with stronger sponsor coverage, making material incremental margins harder to achieve than the strategic narrative suggests.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No directional trade on LAZ from this announcement; treat it as a 6-18 month execution watch item rather than an earnings catalyst.
- Maintain any existing LAZ position only if upcoming results show advisory revenue growth that outpaces compensation expense; flag a firmwide compensation ratio increase of more than 100 bps without corresponding fee acceleration as a negative read-through.
- For financials exposure, do not short BAC on this development: its distribution and financing advantages make the competitive impact de minimis. Reassess only if Lazard discloses repeat sponsor-led ECM mandates or hires a broader execution team over the next two quarters.
- Monitor IPO and secondary issuance volumes alongside LAZ mandate disclosures over the next 1-3 months. A sustained issuance reopening with demonstrated Lazard participation would justify revisiting a tactical LAZ long; absent disclosed conversion, the risk/reward is not differentiated.
More News
- Is Berkshire Bending the Rules With Bending Spoons?
- The PHP Meltdown Shows How AI Makes Bugs More Exploitable
- ROSEN, RECOGNIZED INVESTOR COUNSEL, Encourages Bank of America Corporation Investors to Secure Counsel Before Important Deadline in Securities Class Action
- ROSEN, A RANKED AND LEADING LAW FIRM, Encourages Bank of America Corporation Investors to Secure Counsel Before Important Deadline in Securities Class Action
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Braskem creditors, shareholders near deal on $11bn debt restructuring