
Pharmacists Mutual Names Sharon Duez Shaw Vice President and Head of Claims
Source: PR Newswire
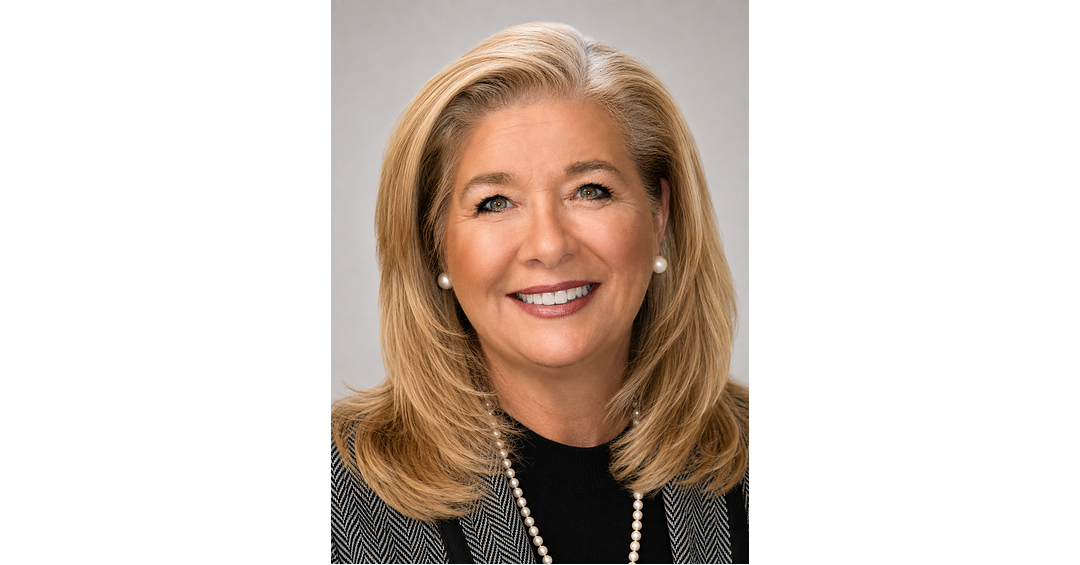
Pharmacists Mutual Insurance Group named Sharon Duez Shaw as Vice President and Head of Claims, effective immediately as part of a planned transition from Peter Lambert, who will retire March 31, 2027. The company emphasized continued investment in specialty underwriting and modernization of claims and litigation strategy, with a six-month handoff to support agents and insureds. No financial guidance or performance metrics were disclosed, making the impact likely limited beyond internal execution.
Analysis
This is essentially a talent-and-process update, not a balance-sheet or underwriting event. The only investable read-through is that specialty carriers are still competing on claims handling and litigation management, which matters most in lines where social inflation can quietly leak combined ratio over 6-18 months. A better claims operator can improve reserve development and defend renewal pricing, but that benefit is company-specific and usually shows up in loss ratio cadence long before it shows up in headline growth.
For public comps, WRB and AXS are the cleanest proxies because they already trade on underwriting discipline and claims sophistication. If anything, the signal is mildly supportive for the sector’s premium multiple: investors continue to reward franchises that can prove they are not just writing niche risk, but managing severity and cycle time better than peers. The second-order risk is the opposite — if this kind of hire is being framed as a growth investment, it can imply the firm expects more litigation intensity and larger-case complexity ahead, which is not a reason to extrapolate margin expansion blindly.
The contrarian view is that the market should largely ignore this. There is no direct public-company earnings catalyst unless we later see evidence of accelerated growth, reserve releases, or materially lower expense ratios at comparable specialty underwriters. The thesis would be falsified if public peers’ loss ratios deteriorate despite similar claims talent moves, or if specialty pricing softens enough to offset any operational gains.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade: treat this as a watch item, not a catalyst, for WRB and AXS over the next 1-3 months unless upcoming earnings show claims-driven margin divergence.
- Relative long WRB / short broader P&C basket on a 6-12 month horizon only if WRB continues to show superior loss-ratio stability; this kind of management emphasis is consistent with a quality premium, but the entry needs confirmation from results, not PR.
- Use AXS as a benchmark for claims efficiency: if its next two quarters show reserve discipline and stable cat loss trends, the stock should hold up better than weaker specialty peers; otherwise fade any multiple expansion.
- Avoid buying volatility around this headline. The probability of a material price reaction is low; any move in WRB/AXS that follows should be viewed as a sector read-through and likely mean-reverting unless reinforced by earnings.
More News
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- UK's Healey Plans to Raise Bank Taxes
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes