
Agthia registra un crecimiento de los ingresos en un entorno de costes complejo
Source: PR Newswire
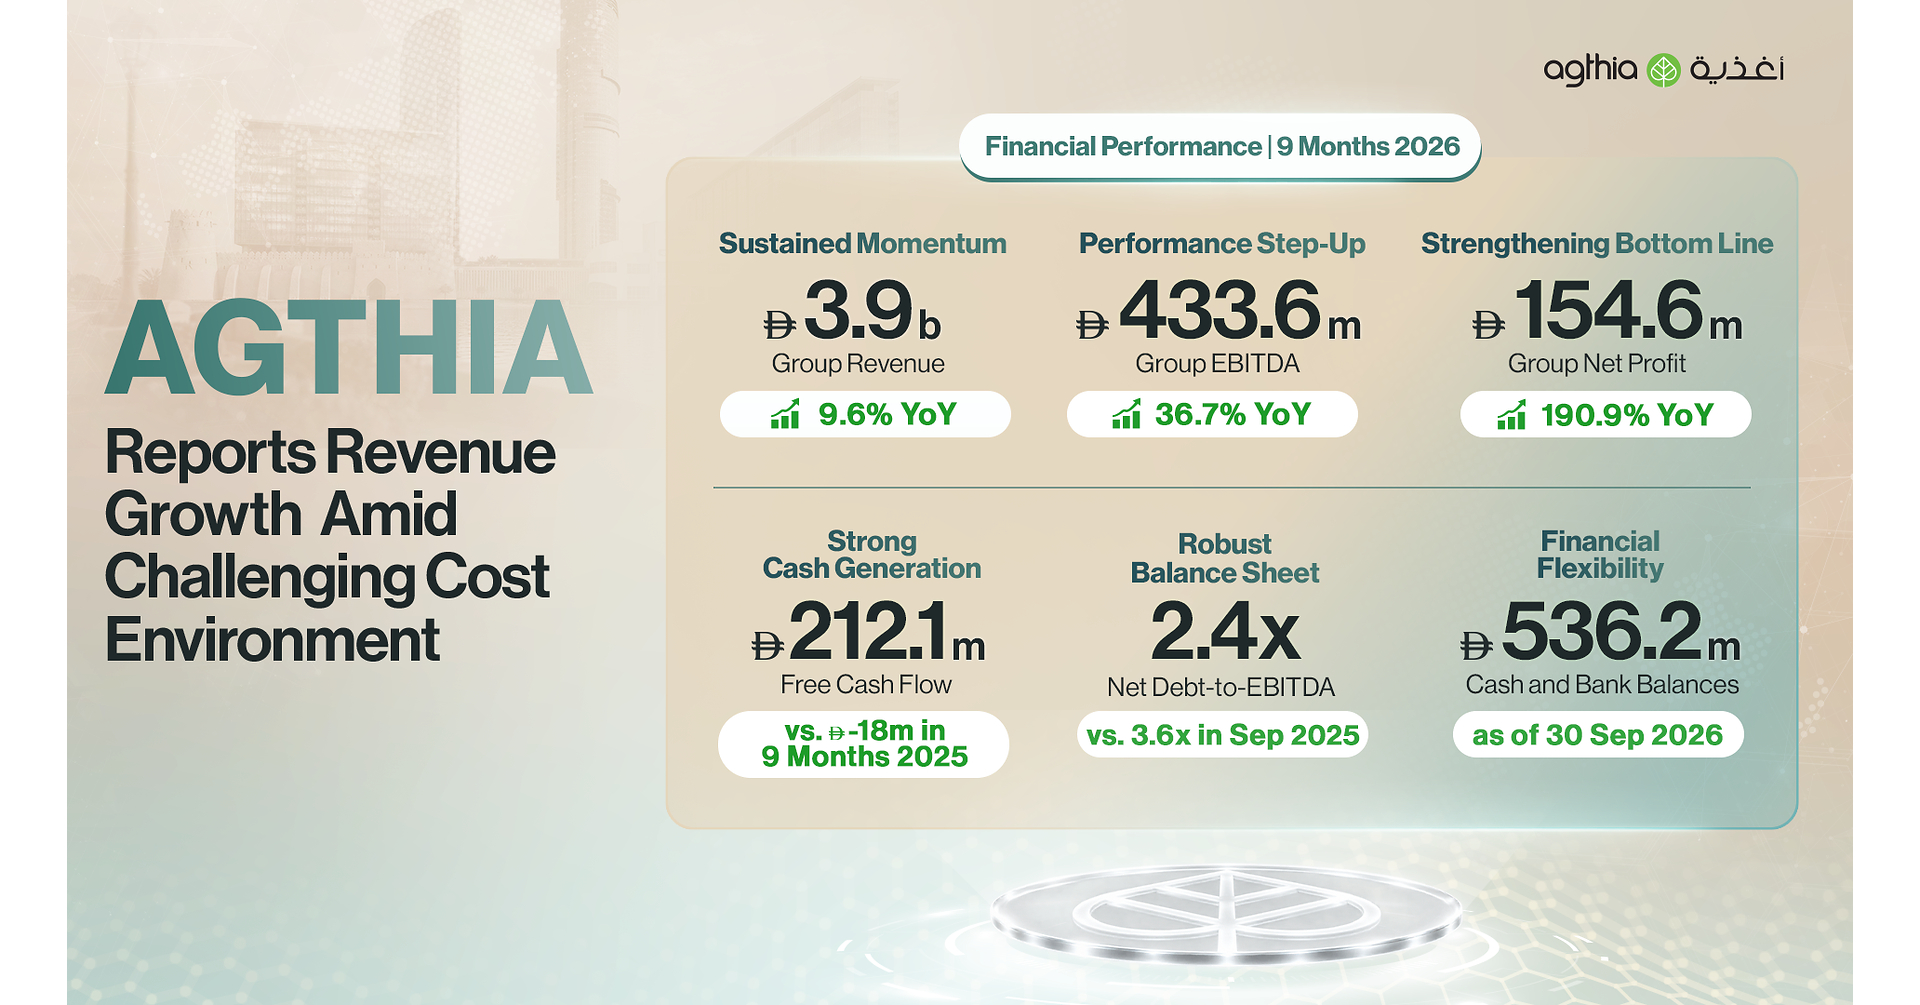
Agthia’s Q3 2026 revenue rose 14.4% year over year to AED 1.3 billion, including AED 104.7 million in one-off sales; underlying growth was 5.2%. EBITDA increased 39.0% to AED 123.1 million and net profit reached AED 33.2 million, versus AED 4.1 million a year earlier, a comparison that included snack-segment impairment charges. For the first nine months, revenue rose 9.6% to AED 3.9 billion, EBITDA gained 36.7% to AED 433.6 million, and free cash flow was AED 212.1 million; higher input, transport and distribution costs pressured some segment margins.
Analysis
The headline earnings acceleration is higher quality than a pure volume story only if it persists: reported revenue includes AED 104.7m of one-off sales (about 8% of Q3 revenue), while underlying growth was materially lower. That creates a risk that investors extrapolate a temporary food-security channel into the run rate. Profit comparisons are also flattered by prior-year snack impairment charges, so EBITDA and segment-level margins are better tests than headline net income.
The key second-order pressure is input-cost pass-through. PET and distribution costs can erode water economics even as home/office demand grows; feed-input inflation has already translated into sharp Agribusiness margin compression despite sales growth. If costs persist, mix and pricing—not top-line growth—will determine whether group EBITDA gains hold. Conversely, snack restructuring and Saudi protein capacity offer operating leverage, but utilization and export-logistics normalization need confirmation.
Near term (days), the release supports a mildly positive read, but likely not a clean re-rating without evidence that core growth and margins are repeatable. Over 1–3 months, watch management commentary and the next trading update for underlying sales, input-cost recovery, and Agribusiness EBITDA. Over 6–18 months, execution on snacks and protein capacity could broaden earnings, while sustained logistics or commodity pressure could absorb those gains. The contrarian risk is that the market focuses on impressive EBITDA growth while underweighting one-off revenue and the unusually easy impairment comparison.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No aggressive post-release position: maintain a conditional positive bias to Agthia shares, but require valuation and liquidity checks before adding; the supplied data do not establish either.
- Add only if subsequent reporting confirms growth excluding one-off food-security sales and stabilizing segment profitability. Track Agribusiness EBITDA/margin, water input-cost pass-through, and snack EBITDA excluding prior-year impairment effects.
- Treat continued PET, feed, or distribution-cost inflation and renewed export disruption as thesis risks. Reassess if core growth weakens or segment margins deteriorate further; improving margins alongside recurring growth would support a more constructive 6–18 month view.
More News
- NextDC shares surge 43% after Goodman, Digital Realty stake purchases
- Qualcomm issues disappointing earnings forecast as memory shortage weighs on smartphone sales
- ‘Seismic’ blue wave triggers the sinking of oil prices, energy stocks, and the chances of power permitting reform
- Softbank’s $5.4 bln takeover of ABB robotics unit blocked by China- FT
- Nifty Bounces Back to Beat All of Asia on Foreign Flows, Earnings
- Snap shares fall over 10% on third-quarter earnings miss