
Eqvista Launches Company-Sponsored Tender Offers, Expanding Private Market Liquidity Capabilities
Source: PR Newswire
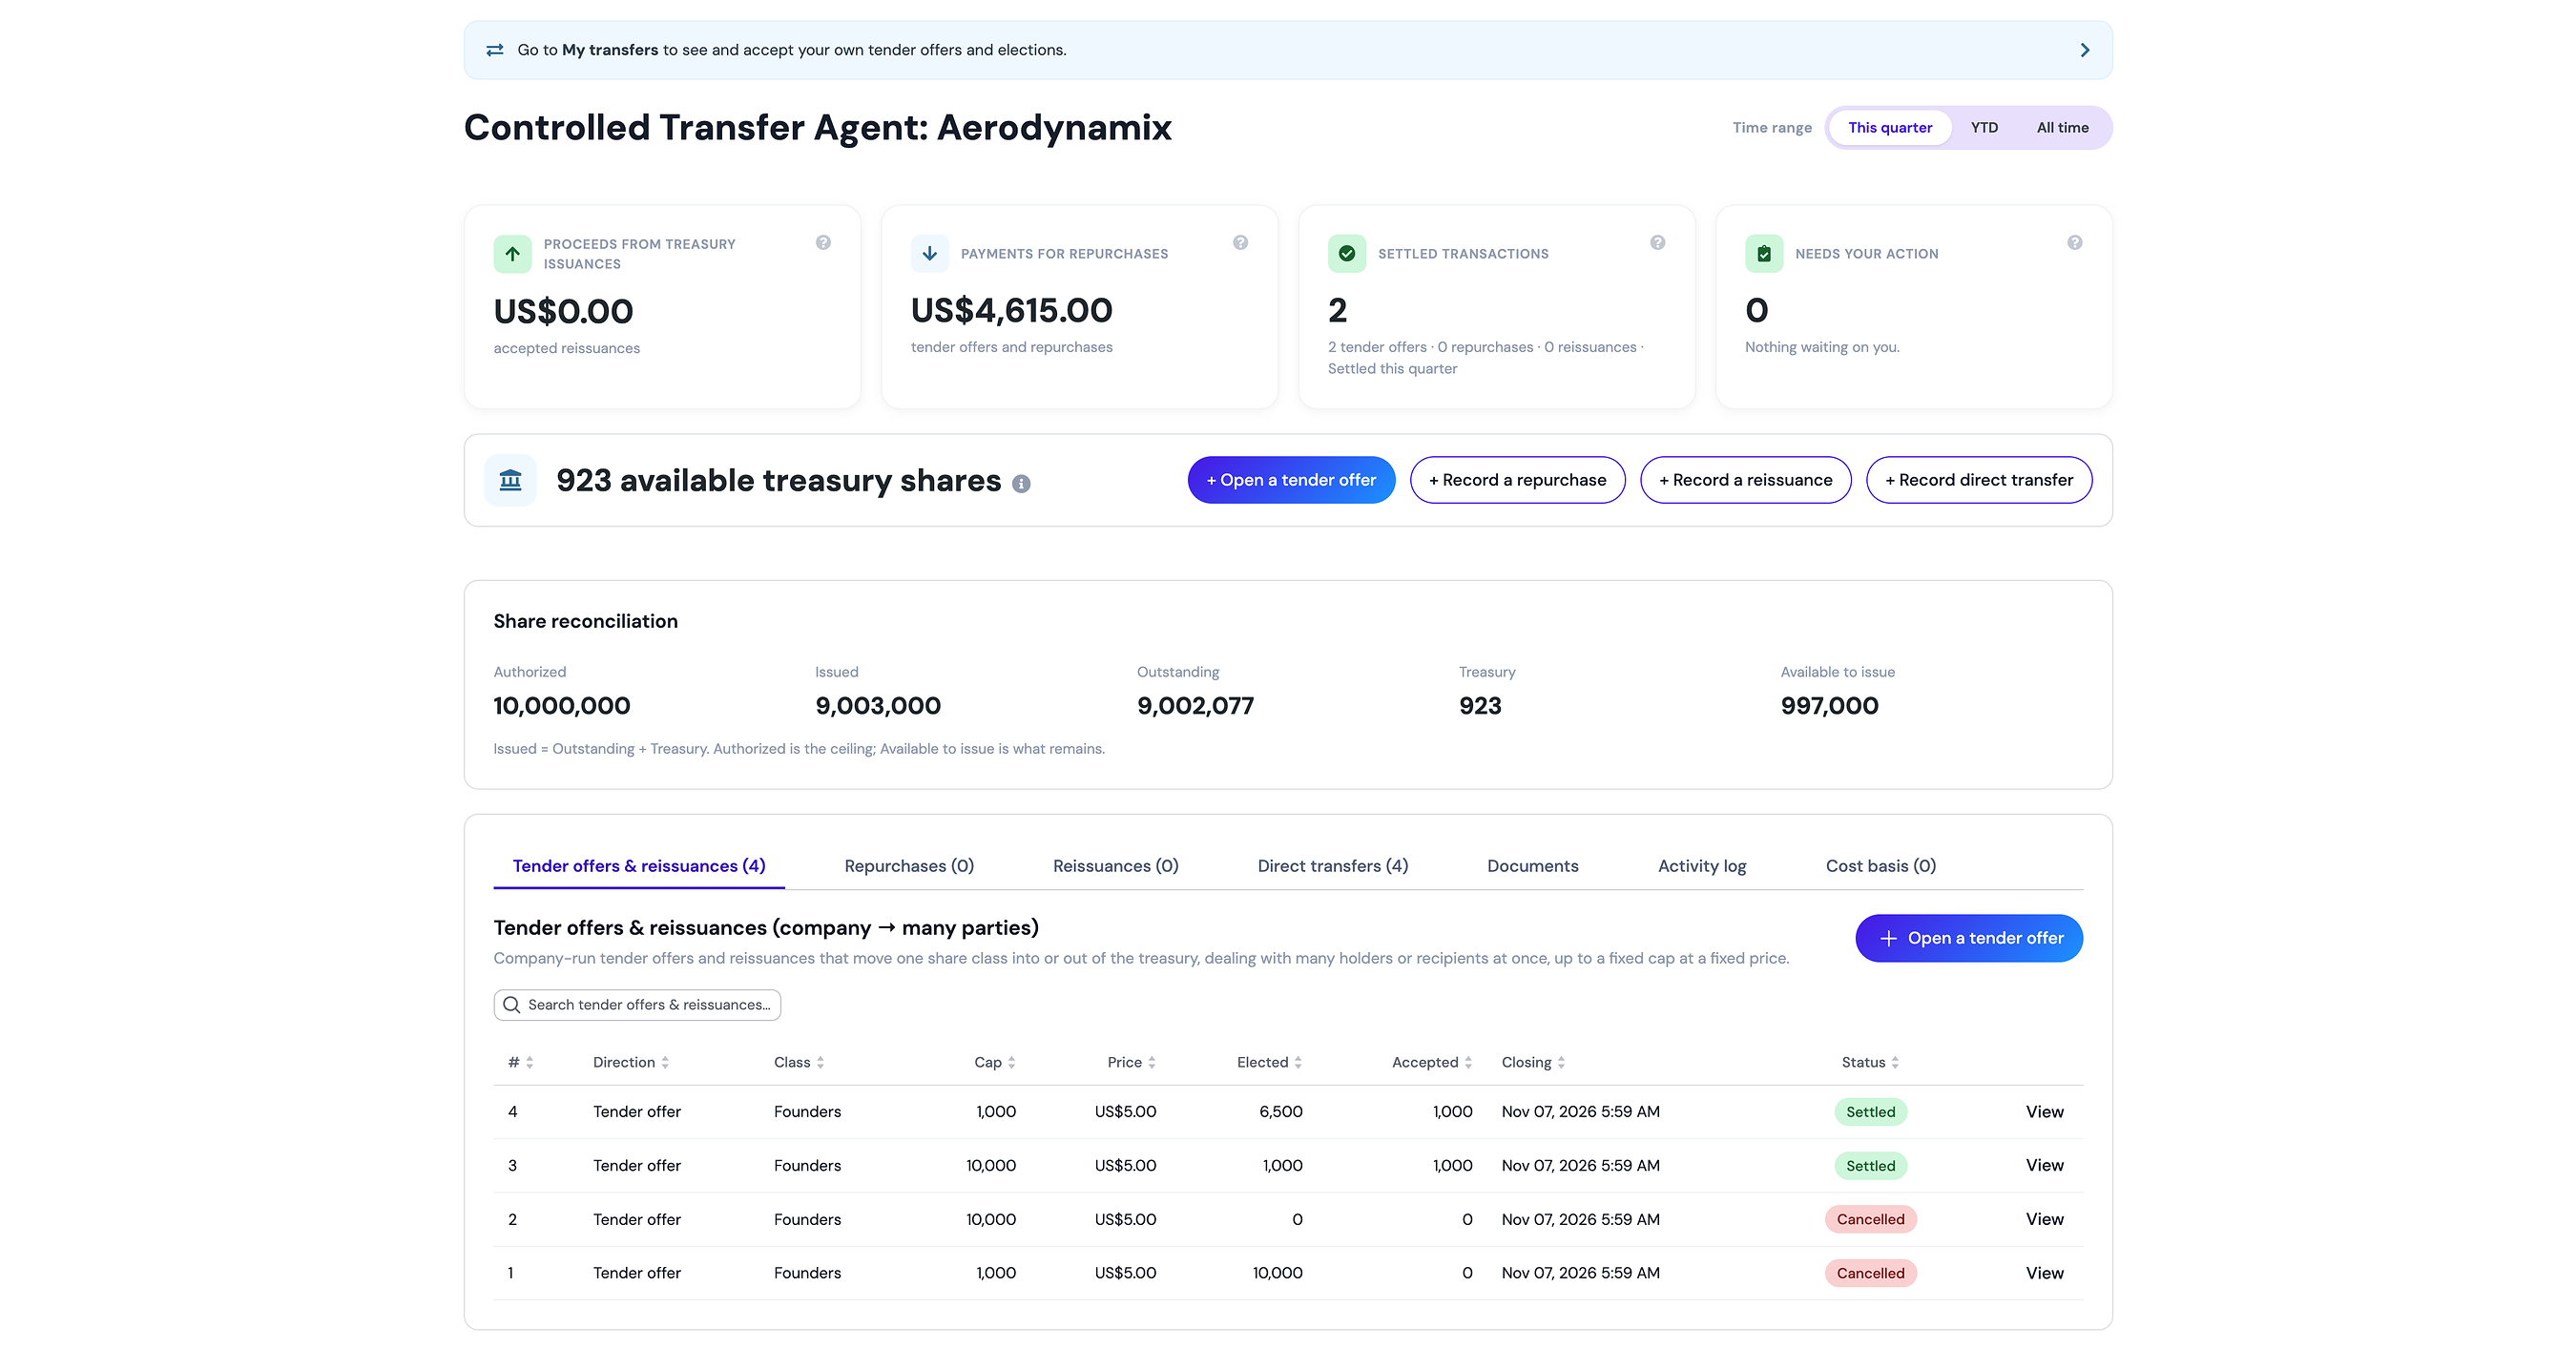
Eqvista launched company-sponsored tender offer capabilities, allowing private companies to manage participant eligibility, transaction terms, allocations, approvals, and ownership changes within its equity management platform. The platform serves more than 25,000 companies, and its real-time valuation data covers approximately 65,000 U.S. private companies with an estimated combined value of $9 trillion. Eqvista said the launch lays groundwork for planned secondary-marketplace capabilities; further details are pending.
Analysis
The announcement is strategically more meaningful than financially actionable: tender-offer workflow can deepen Eqvista’s equity-administration relationships and create a path to transaction revenue, but valuation coverage is not evidence of paid adoption, executable prices, or secondary-market volume. The key monetization test is whether companies repeatedly run offers on-platform and whether buyers and sellers arrive with enough depth to clear transactions.
Potential competitive pressure falls on private-company cap-table providers and secondary intermediaries such as Carta, Forge Global, Nasdaq Private Market, and EquityZen. The second-order risk for standalone intermediaries is disintermediation if issuers prefer liquidity inside their existing ownership system; however, company control may also constrain participation and liquidity, preserving a role for brokers that source buyers and manage complex transactions. A valuation estimate used as a pricing reference is not necessarily a clearing price; stale or optimistic marks could increase disputes and undermine trust.
Near term (days), this is unlikely to support a public-equity earnings revision absent a listed, material exposure. Over 1–3 months, verify customer adoption, completed tender volume, transaction monetization, and whether the planned marketplace obtains required regulatory clearances. Over 6–18 months, successful integration could make equity records and transaction history more valuable, but network effects require repeat buyers and sellers. Contrarian view: the announcement may overstate the importance of valuation-data breadth; liquidity depends more on issuer participation, buyer access, and price discovery. No direct trade is justified on this release alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate position: Eqvista is not identified as a publicly traded issuer in the supplied data, and the release provides no independently verifiable revenue or transaction-volume impact.
- Track adoption rather than platform coverage: seek evidence of completed offers, repeat issuer usage, transaction fees, and buyer participation before treating this as a durable competitive threat to Carta, Forge Global, Nasdaq Private Market, or EquityZen.
- Treat the planned marketplace as a conditional catalyst, not a base-case earnings driver; reassess if regulatory requirements delay launch or if issuer-controlled eligibility materially limits liquidity.
- Falsification watch: the thesis weakens if tender-offer usage remains low, transactions do not generate recurring monetization, or valuation references diverge materially from actual clearing prices.
More News
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Alibaba Backs Chinese Robovan Maker in $400 Million Fundraising
- Walmart’s Flipkart is quietly building a food delivery challenger in India
- Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line