
Alexandria REIT: Q3 Review And A Look At 7.6% Yielding Bonds
Source: seekingalpha.com
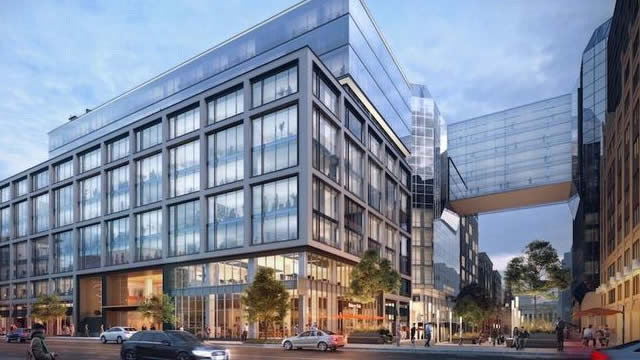
Alexander Real Estate Equities reported Q3 2026 AFFO basically in line with expectations. Robust leasing activity is offset by deteriorating occupancy, elevated vacancies, tenant-favorable market conditions, and costly concessions needed to maintain occupancy.
Analysis
The key risk is earnings quality, not the quarter’s AFFO variance: gross leasing can remain healthy while vacancy, rent concessions and tenant-improvement spending erode effective rent and cash returns. If that pattern persists, reported occupancy may stabilize before leasing economics do, delaying any AFFO recovery and keeping the valuation multiple under pressure. The second-order exposure is to life-science landlords competing for the same tenants; weaker leasing economics can force concessions across the market and prolong absorption of new space. Over the next 1–3 months, watch disclosures on net effective rents, renewal spreads, concessions and tenant improvements—not just leasing volume or headline occupancy. Over 6–18 months, the thesis depends on whether tenant demand absorbs available space faster than new supply comes online. The contrarian case is that robust leasing signals a demand floor, and concessions may be concentrated in particular buildings or submarkets rather than indicate a broad deterioration. With AFFO broadly in line and no quantified leasing economics provided, the evidence supports caution, not an unqualified short. Reverse the bearish view if occupancy and effective rents improve together without rising leasing costs; strengthen it if management indicates further rent pressure or weaker occupancy.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Key Decisions for Investors
- Avoid treating in-line AFFO as a catalyst to buy: it does not resolve the more important question of effective rent and the cost of retaining tenants.
- Keep Alexander Real Estate Equities on a short/underweight watchlist rather than initiating solely on this report. Consider a position only after confirming persistent deterioration in net effective rents, renewal spreads or tenant-improvement costs in the next operating update.
- For a potential relative-value expression, compare Alexander Real Estate Equities with diversified office landlords; do not assume the peer hedge is clean, since tenant mix and property locations may differ materially.
- Set a thesis check for the next 1–3 months: improving occupancy accompanied by stable concessions and leasing costs would falsify the bear case; leasing volume without improvement in those measures would not.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
- Microsoft's Big Bets on AI Start to Pay Off