
Uzbecká skupina TEG působící v pohostinství dokončila fúzi s americkou společností
Source: PR Newswire
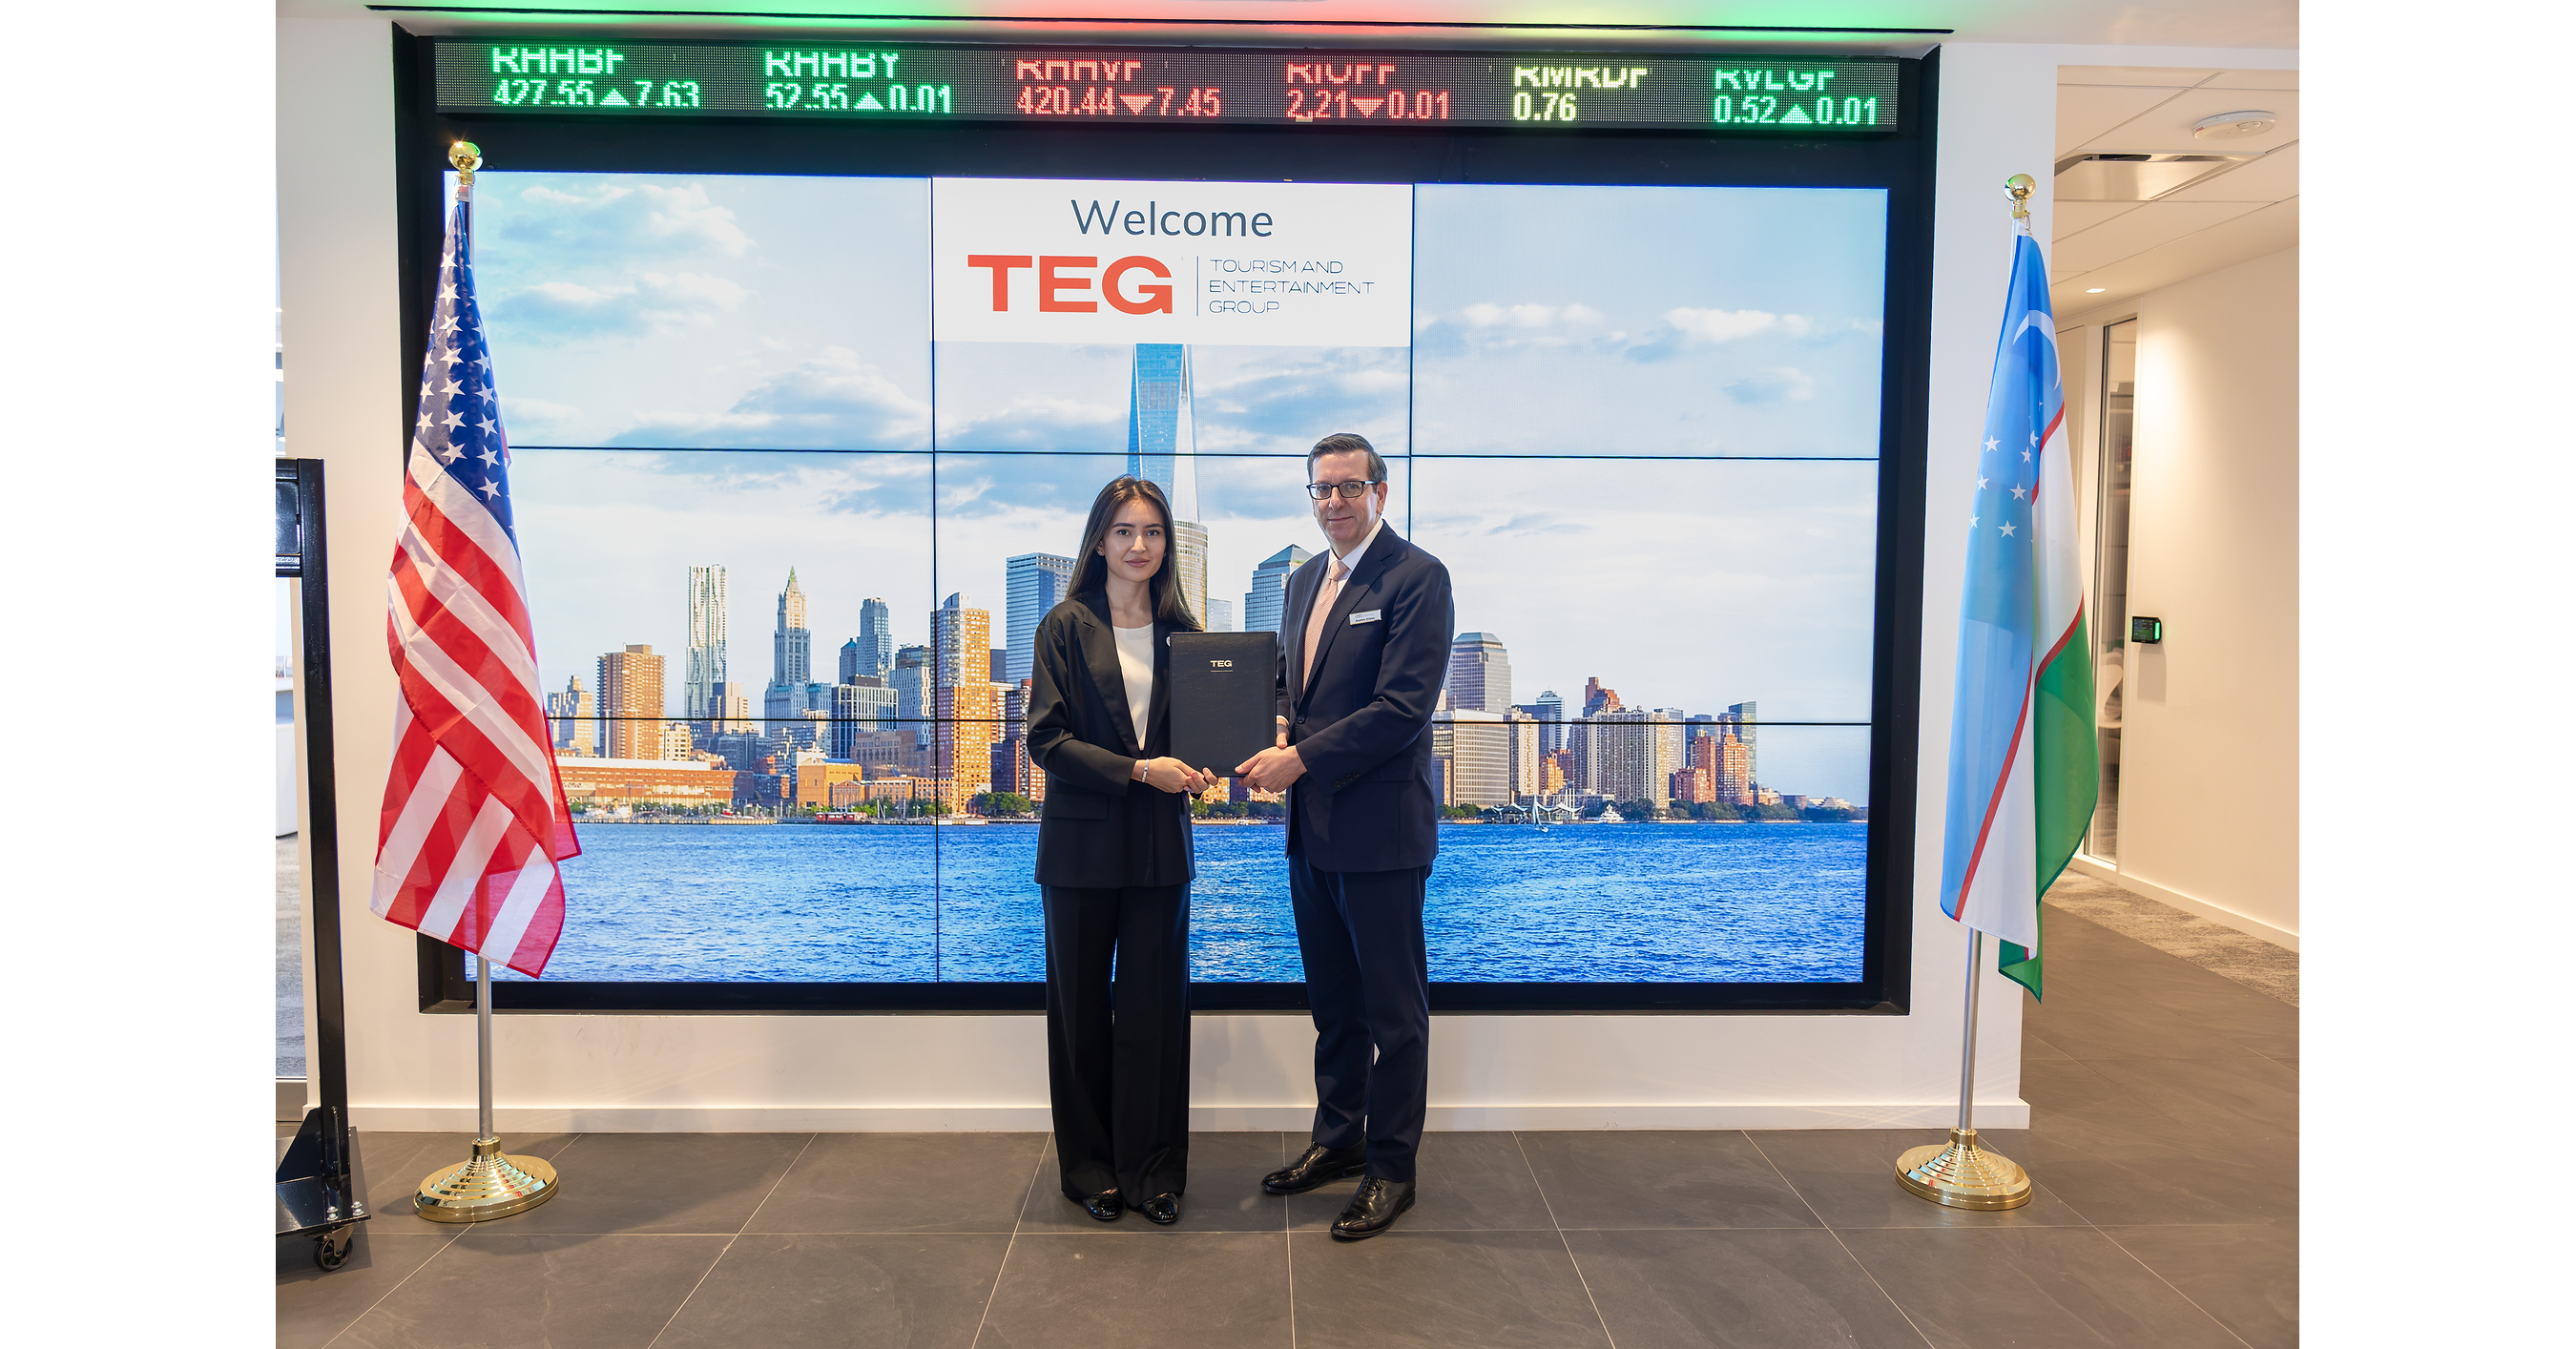
Uzbek hospitality group TEG completed its stock-exchange merger with StageWise Strategies, making TEG the operating business of TEG Overseas, Inc.; its common shares are to trade on OTC Markets. TEG’s portfolio generated $42.9 million in 2025 revenue and $14.4 million in net income, up 22% and 215%, respectively, from 2024. The company plans to use access to U.S. capital markets to fund acquisitions and expand its hotel and MICE portfolio, against a backdrop of 11.7 million foreign visitors to Uzbekistan in 2025, up nearly 47% year over year.
Analysis
The key underwriting gap is conversion: national tourist arrivals do not establish TEG’s occupancy, room rates, event utilization, or incremental cash flow. Its reported portfolio results are company-reported and do not show how much is attributable to each property, whether earnings convert to cash, or what capital is required for expansion. Validate audited filings, property-level operating data, debt and related-party arrangements before assigning value to the growth plan.
The OTC listing may provide a transaction currency, but it does not by itself demonstrate durable access to institutional capital. Thin liquidity, dilution, governance and execution risk could outweigh the benefit of a U.S. quotation—particularly if development ambitions require external funding. AKFA’s construction and procurement links could accelerate projects, but related-party pricing and capital allocation merit scrutiny. New hotel supply could also absorb demand growth and limit pricing power.
Hilton Worldwide Holdings and Wyndham Hotels & Resorts have, at most, indirect brand/fee exposure through the named properties; the release does not establish that either receives material incremental fees or owns the underlying operating economics. No meaningful near-term earnings read-through for HLT or WH is supported. Over 1–3 months, filings, share structure, financing terms and project-level disclosures are more actionable than the tourism narrative. Over 6–18 months, verify delivered capacity and property-level returns against expansion claims. The contrarian risk is that investors price a national tourism growth story into an illiquid security before proving the issuer can fund and monetize it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- Do not trade HLT or WH on this announcement: any brand-fee upside is unquantified and likely immaterial absent evidence of additional rooms or a material contract change.
- Treat TEG Overseas as a watch item, not a buy signal, until SEC filings confirm fully diluted share count, merger consideration, cash/debt, free float, related-party transactions, and audit quality.
- Reassess only after property-level occupancy, ADR, event utilization and operating cash flow are disclosed alongside committed financing and project costs; rising tourist arrivals alone do not validate earnings growth.
- Falsify the growth thesis if expansion is funded through substantial dilution or expensive debt, projects are delayed, or operating cash flow fails to support reported earnings; confirm any potential reversal with filings rather than OTC price action alone.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- Why is Samsung Electronics stock plunging today?
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- UBS considers leaving Switzerland over capital rule plans, WSJ reports
- US Stocks Tumble as Chip Rout Deepens
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Research Tools for Pension Funds and Allocators
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals