
The Coffee Bean & Tea Leaf® and Al-Ghunaim Celebrate 130-Café Milestone in Kuwait
Source: PR Newswire
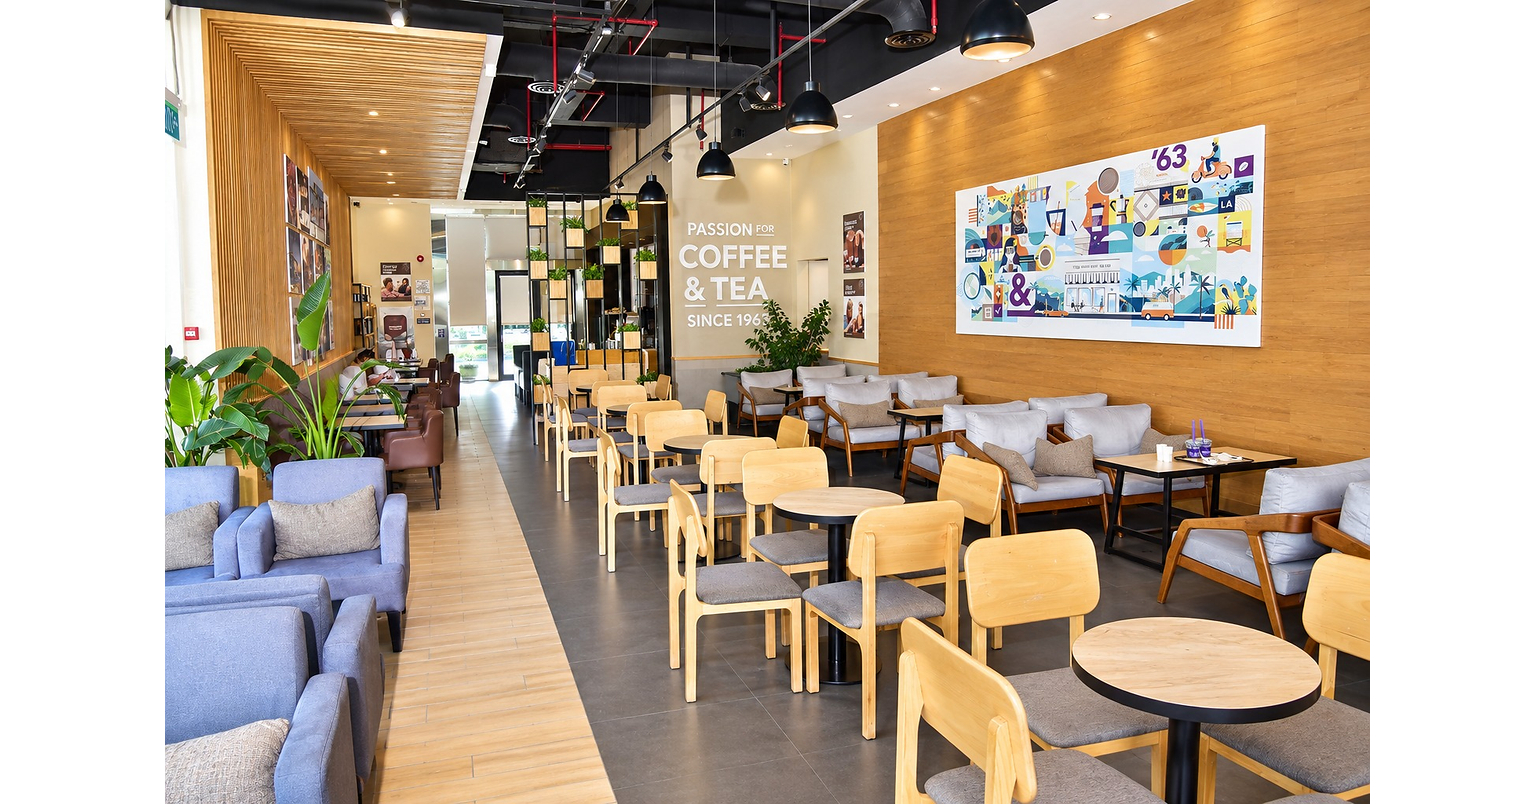
The Coffee Bean & Tea Leaf and franchise partner Al-Ghunaim Trading opened their 130th Kuwait café, expanding from a single Salmiya location in 2004 to a network supported by more than 1,135 employees. The partnership highlights sustained customer loyalty, including a third consecutive Top 10 Brands ranking in Kuwait, and plans continued investment in innovation, personnel and operational execution. Al-Ghunaim also contributed $1 million to Kuwait's Emergency Response Fund in 2026.
Analysis
This is not independently actionable for public markets: the operating entity in Kuwait is private and the parent exposure sits within unlisted Jollibee Foods Corp. The milestone does, however, reinforce that CBTL’s franchise model can compound unit density in affluent GCC markets without requiring parent-funded store capex, making royalty and supply-chain revenue more resilient than company-operated café economics. The relevant question is whether network maturity is lifting same-store sales and franchise profitability, or whether incremental units are increasingly cannibalistic.
At roughly one café per 38,000 residents, Kuwait appears highly penetrated for a premium beverage concept. That raises the probability that future growth must come from ticket expansion, delivery, loyalty and format optimization rather than unit rollout; promotions or delivery-platform commissions could pressure franchisee-level margins before any weakness becomes visible at the brand level. Starbucks’ regional operator Alshaya is the clearest competitive read-through, although its parent is private; listed regional consumer proxies such as Americana Restaurants (AMR.AE) may face similar labor, rental and discretionary-spend sensitivities rather than benefit directly.
The near-term signal is weak and should not drive a position. Over 6-18 months, sustained premium-café density could support a broader GCC franchising valuation narrative for Jollibee if disclosed through system sales, international same-store sales, and franchise-income growth; absent those disclosures, the announcement is principally brand marketing. A deterioration in Kuwait consumer spending, food-input inflation, wage costs, or evidence of declining sales per store would falsify the constructive interpretation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No standalone trade: do not infer material earnings impact from this private-market milestone without Jollibee Foods Corp. segment disclosures on CBTL system sales, royalty income, and GCC franchise mix.
- Place Jollibee Foods Corp. (JFC.PH) on watch for the next two reporting cycles: consider a long only if international same-store sales and franchise/commissary revenue accelerate while consolidated restaurant-level margins hold; this would validate an asset-light earnings contribution rather than unit-count optics.
- For GCC consumer exposure, monitor Americana Restaurants (AMR.AE) quarterly same-store sales and delivery-mix margins as a listed proxy for regional discretionary-food demand. A broad slowdown in traffic or margin compression would be a negative read-through for premium café saturation, not a direct short catalyst.
- Watch Kuwait CPI food-away-from-home, delivery-platform commission trends, and consumer-credit growth over the next 3-6 months; adverse movement would increase cannibalization and franchisee-margin risk at mature café density.
More News
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Tesla poised to scale production of heavy-duty Semi trucks with opening of Nevada factory
- Here’s the Tesla Semi… again
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly