
MINORITY-OWNED MILLENNIUM BANK OPENS REVITALIZED BRIDGEPORT BANKING CENTER, UNVEILS 120-FOOT COMMUNITY MURAL
Source: PR Newswire
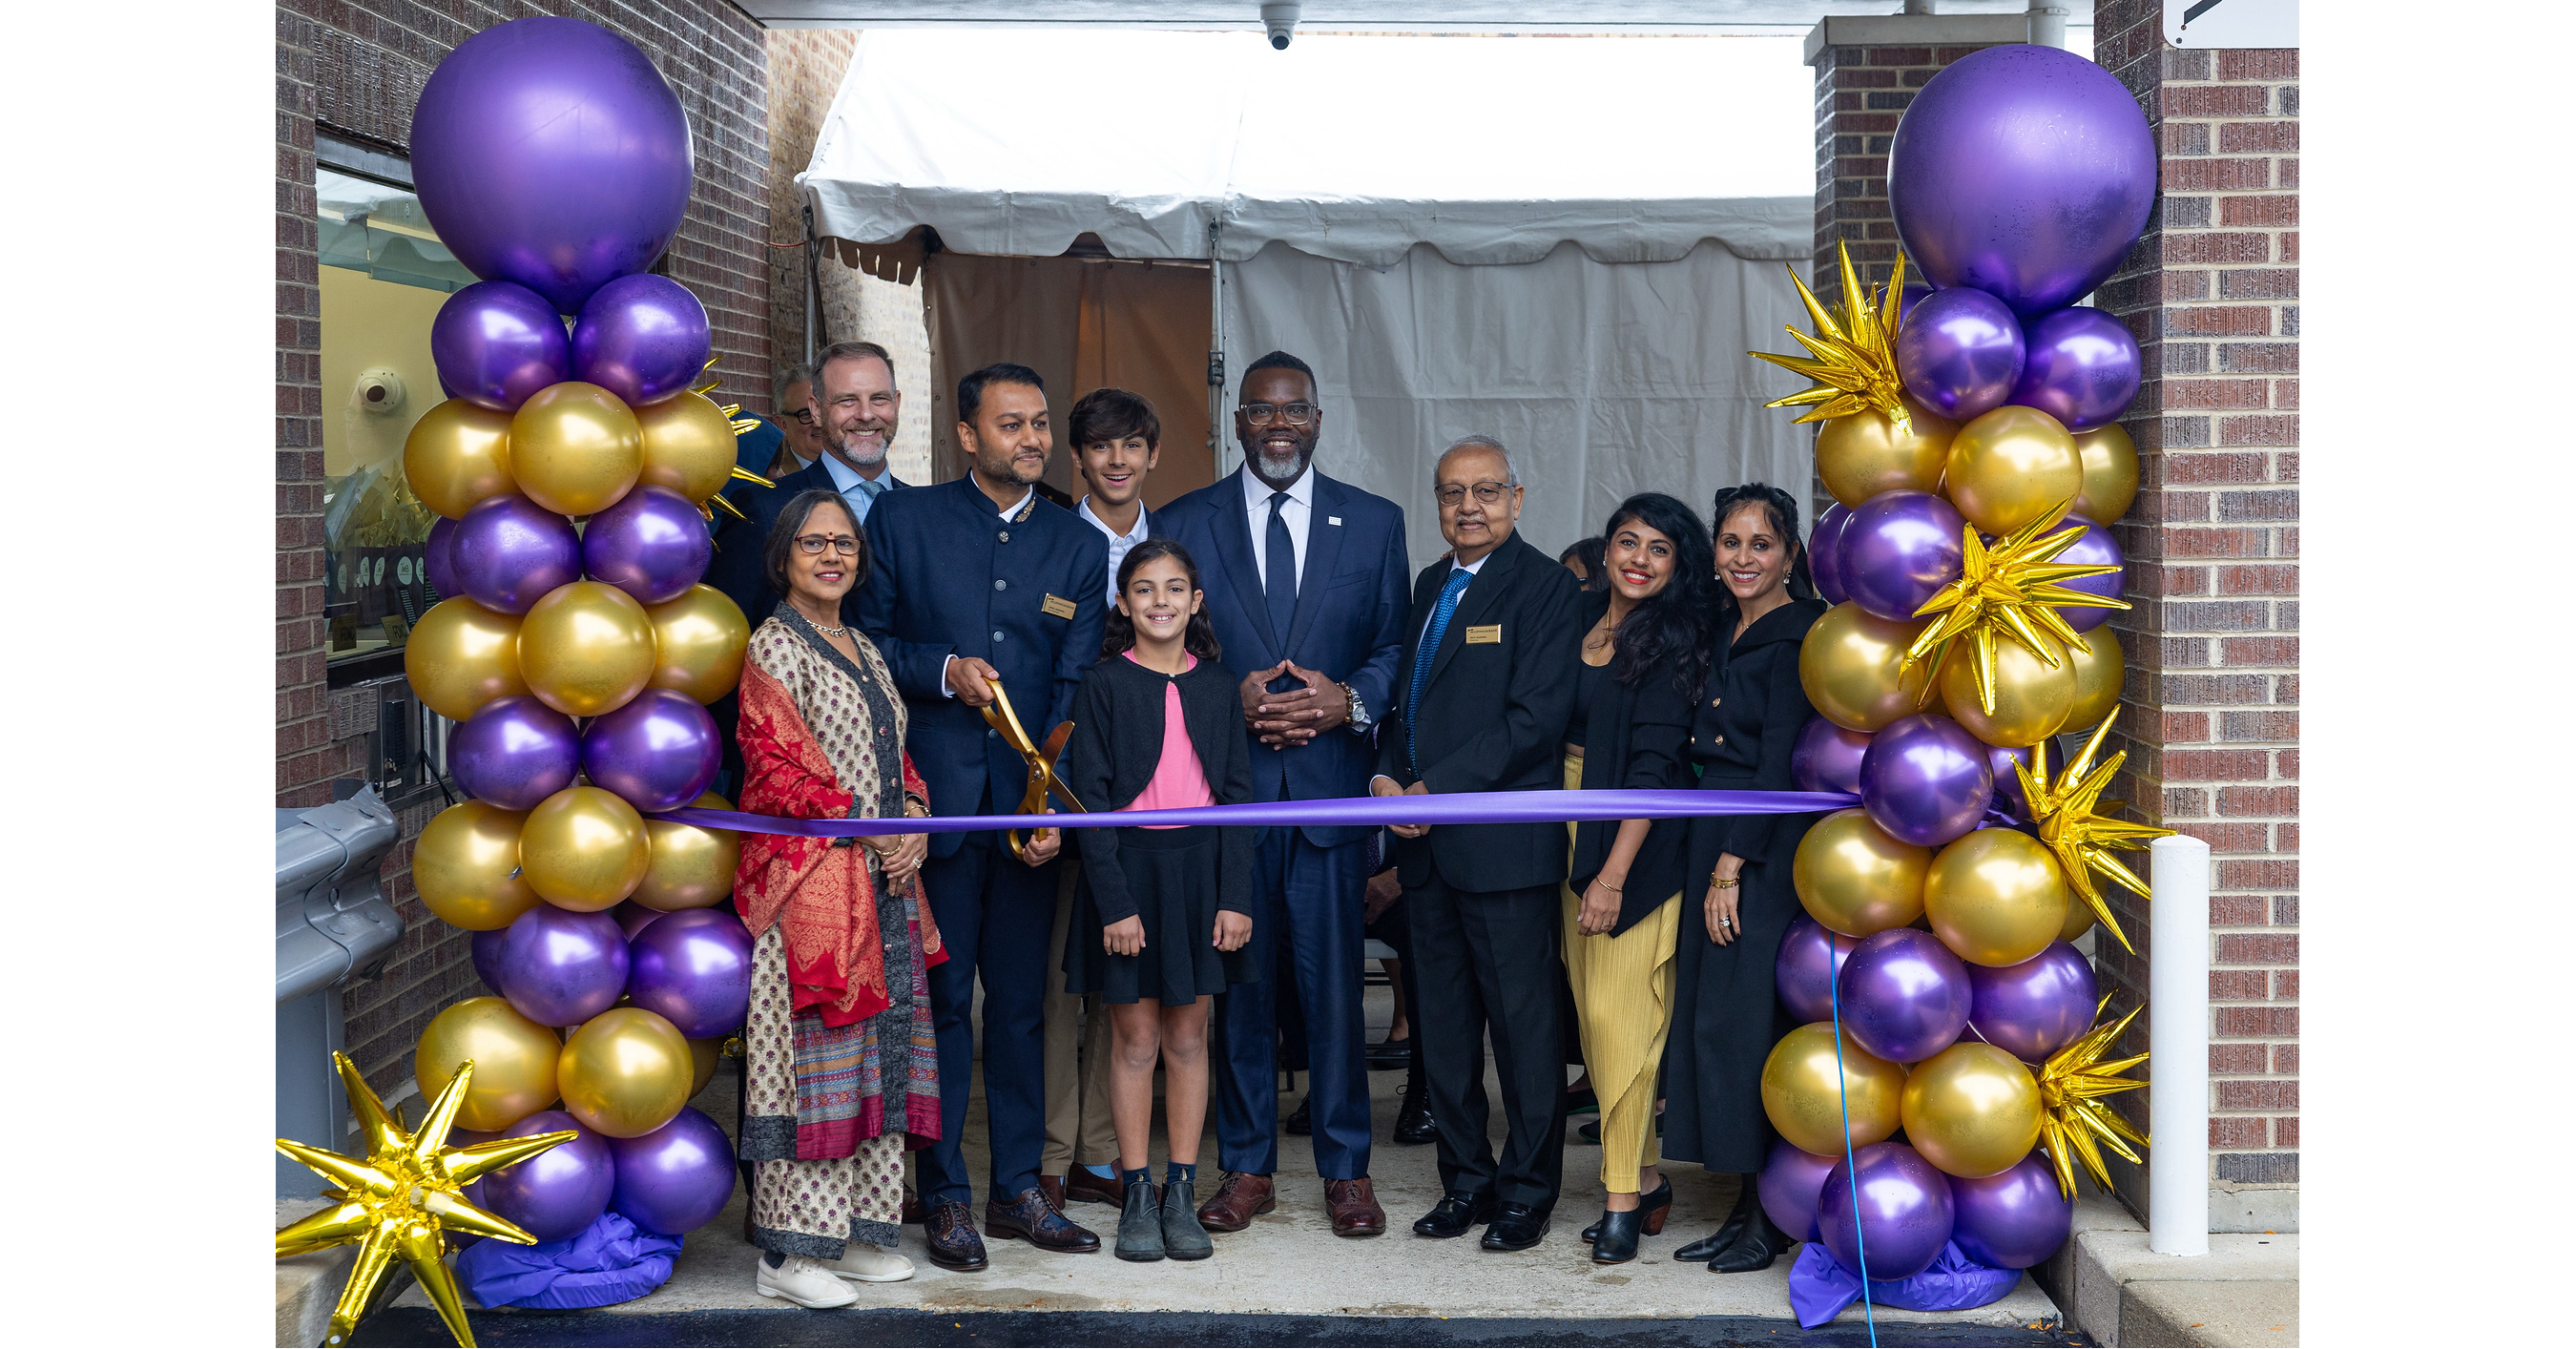
Millennium Bank reopened the former Pulaski Savings Bank branch in Chicago's Bridgeport neighborhood after acquiring the failed institution in January 2025, establishing a physical foothold serving roughly 1,000 local customers. The minority-owned bank has nearly $1 billion in assets and has funded approximately $350 million in SBA loans over the past decade, focused on minority-owned businesses, commercial real estate and multifamily housing. The expansion supports its Chicago growth strategy but is unlikely to have material public-market impact.
Analysis
This is not a public-markets catalyst by itself: Millennium Bank is privately held, and the branch reopening carries no independently disclosed loan-growth, deposit, purchase-accounting, or capital data. The investable read-through is narrowly regional: the failed-bank asset transfer removes a local credit provider while preserving lending capacity, but Millennium's sub-$1 billion balance sheet means even aggressive Chicago expansion is immaterial to large Illinois bank earnings.
The more relevant second-order issue is credit concentration. A push into hospitality, commercial real estate, and multifamily can produce above-system loan growth over the next 12-24 months, but those are precisely the Chicago categories most exposed to refinancing costs, office-adjacent demand weakness, and property-tax/insurance inflation. If Millennium competes on relationship terms to gain share, its future loss content could lag the apparent growth story; the press-release framing provides no evidence on underwriting standards, CRE concentration, nonperforming assets, or deposit pricing.
For listed banks, this is a modest signal that local relationship lenders remain willing to fill credit gaps left by failed or consolidating institutions. That marginally supports loan-volume resilience for Chicago-focused franchises, but it also implies continued pricing competition for deposits and quality middle-market borrowers. The near-term effect is negligible; the useful 6-18 month watch item is whether local CRE delinquency and criticized-loan trends rise faster than system averages as smaller banks expand into underserved segments.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No standalone trade recommended; Millennium Bank is private and the disclosed expansion lacks the balance-sheet data needed to estimate earnings or credit impact.
- For exposure to Illinois community-bank credit risk, monitor Wintrust Financial (WTFC) quarterly CRE concentration, criticized loans, deposit beta, and Chicago multifamily charge-offs over the next 2-4 earnings cycles; a material deterioration would support a regional-bank underweight rather than a Millennium-specific thesis.
- Use KRE as a watch vehicle, not an entry signal: reassess if regional-bank CRE delinquency trends accelerate or if deposit costs fail to decline alongside policy easing, which would pressure smaller-bank net interest margins despite loan growth.
- Falsification of the cautious credit view: disclosed evidence that local multifamily/hospitality refinancing remains orderly, criticized assets stay stable, and smaller-bank deposit costs reset down materially over the next 6-12 months.
More News
- See 'Skittishness' Around Credit: Annie Seelaus
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can Hedge Funds Use ChatGPT? A Control Framework
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash