
Beyond the Ballroom: The Reverie Saigon Unveils a New Approach to MICE Travel
Source: PR Newswire
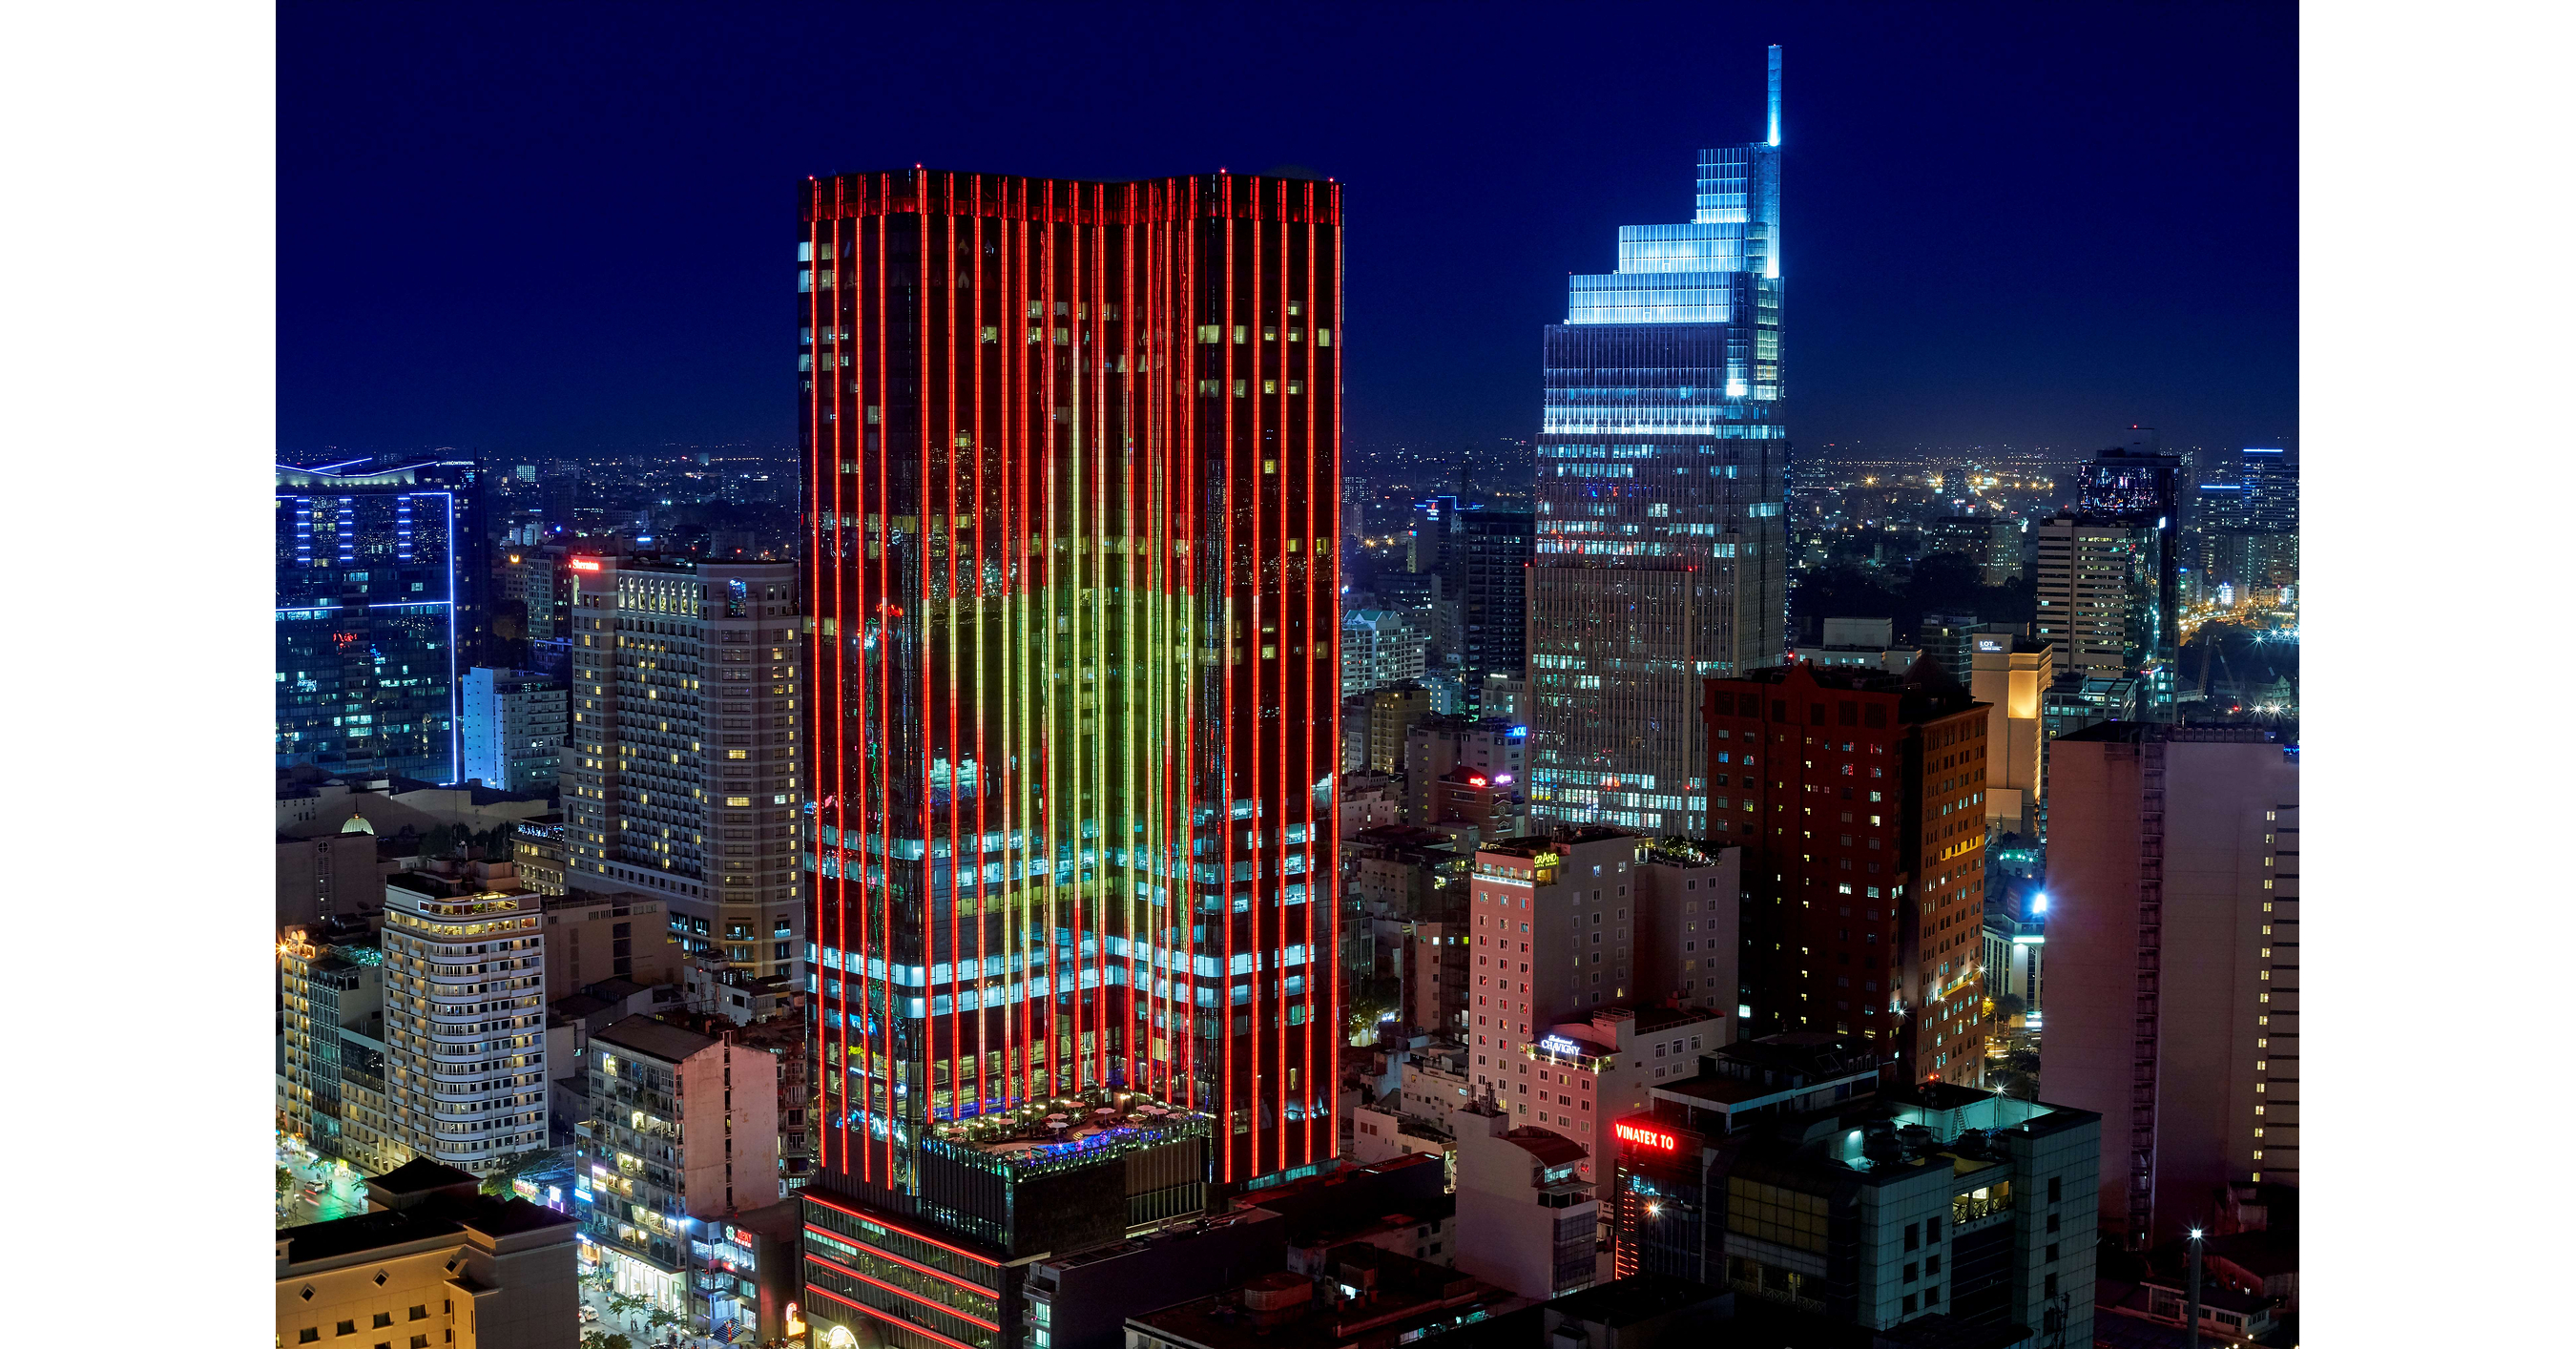
Ho Chi Minh City is positioning further as a leading MICE hub, supported by a dedicated MICE support policy through 2030 and expanded infrastructure (Tan Son Nhat Airport Terminal 3, Metro Line 1 operating, Metro Line 2 under construction). The Reverie Saigon is launching a “business + Michelin-starred dining + wellness + bespoke city experiences” MICE offering with 15 venues, including a 618-sqm pillar-free La Scala Ballroom, plus premium add-ons such as yacht cruises and Rolls-Royce tours. The news is promotional and tourism-focused, implying modest near-term impact rather than a direct financial catalyst for public markets.
Analysis
This is a pricing-power story, not a demand-shock story. The only real economic upside is if premium MICE demand lifts mix toward higher-ADR rooms, banquet F&B, and ancillary spend; that can expand EBITDA faster than occupancy because corporate groups buy bundled experiences and are less price-sensitive than leisure travelers. But that benefit is usually concentrated in a few asset-heavy operators with control over venue space and adjacent experiences, not broadly across the hospitality stack.
The second-order winners are the transport and access nodes that make group travel easier: airport throughput, premium ground transport, and city-center retail. If the city’s infrastructure improvements materially reduce friction, the incremental share gain should accrue first to inbound demand capture rather than to any one hotel brand. The key risk is substitution: planners can reroute to Singapore, Bangkok, or Kuala Lumpur quickly if visa policy, airlift, or corporate travel budgets tighten, so the thesis is very sensitive to 1-3 quarter booking data rather than press-release momentum.
RYCEY is basically a branding bystander here; a luxury tour mention does not translate into engine orders, aftermarket revenue, or backlog acceleration. Contrarian view: the market may be overestimating how much "destination experience" can offset cyclicality in group travel. What matters over 6-18 months is not the marketing angle but whether RevPAR, group pace, and banquet utilization sustain enough to justify higher multiples for the underlying asset owners.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No immediate trade in RYCEY: treat the Rolls-Royce mention as non-fundamental noise; fade any sympathy move unless backlog, engine deliveries, or aftermarket guidance changes over the next 1-3 quarters.
- Stay flat on any presumed ASGXF hospitality exposure until hard data confirm the thesis: watch next two quarterly prints for RevPAR, group occupancy, and banquet/F&B contribution; only consider a long if those metrics inflect, otherwise the release is just marketing.
- Watch-list the Vietnam inbound travel complex for 3-6 months rather than trading it now: the earliest beneficiaries should be airport/transport/concession operators, not the hotel itself, if passenger and MICE throughput data stay strong.
- If group-travel data weakens or airlift disappoints, be prepared to short any over-owned regional luxury-hospitality proxy on valuation compression; the reversal catalyst would be slower corporate travel budgets or a drop in international arrivals.
More News
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Why is US turning to Russia for diesel despite sanctions?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Independent Research Firms: A Publishing System
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More