
Micron: Even If Memory Prices Fall 15%, It May Still Be Undervalued
Source: seekingalpha.com
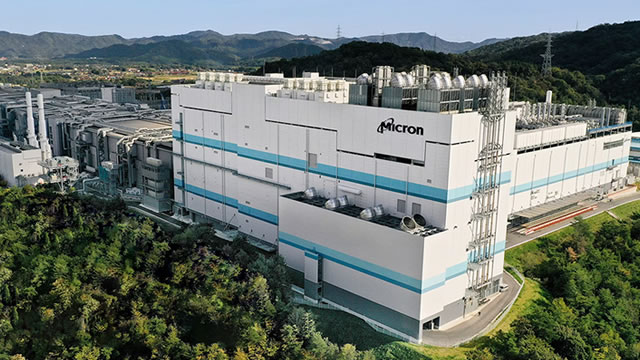
Micron received a Buy rating with a $1,307 base-case target, implying approximately 25% upside from current levels. The thesis cites AI infrastructure demand and industry supply constraints as drivers of revenue and margin expansion, while assuming shipment growth continues and memory pricing declines moderately as supply expands.
Analysis
The key issue is whether Micron can convert AI-related demand into durable pricing power before the memory cycle responds. High-bandwidth memory can support richer product mix, but capacity and investment are not isolated: as suppliers add output and qualify products, additional supply can pressure memory pricing more broadly. That creates a potential lagged reversal—shipment growth may continue while incremental revenue and margin benefit fades. Conversely, allocating capacity to AI memory could tighten conventional DRAM supply and extend pricing strength if production cannot ramp quickly.
Near term, an analyst upgrade alone is a weak catalyst absent evidence of estimate revisions, customer commitments, or improving shipment economics. Over 1–3 months, verify HBM shipment growth, customer qualification and management’s pricing/margin commentary. Over 6–18 months, track industry capacity additions and whether supply growth outruns demand. Competitors’ investment and execution matter as much as Micron’s own demand pipeline.
The contrarian risk is treating AI demand as proof that memory cyclicality has disappeared; the opposite risk is underestimating how capacity constraints and product mix could sustain earnings longer than a typical cycle. The supplied information does not establish valuation, consensus expectations, or the durability of customer demand, so the stated upside case is not independently testable here.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Do not chase solely on the rating or target. Consider a staged MU long only if upcoming results corroborate HBM shipment growth and pricing/margin resilience; the article provides no entry price or valuation data to set a defensible level.
- Set a 1–3 month alert for estimate revisions and management commentary on HBM shipments, customer qualification, and memory pricing. If shipment growth is accompanied by weakening pricing or margin guidance, do not add and reassess exposure.
- Track 6–18 month supply indicators, including announced capacity additions and competitor ramp progress. Faster-than-expected supply growth relative to demand would falsify the durable-pricing thesis and raise the risk of earnings and multiple compression.
- Keep position sizing sensitive to the memory cycle: AI demand is supportive, but it does not remove downside from a supply response or delayed customer spending.
More News
- OpenAI projected to bring in $20bn less in revenue than expected
- Memory stocks have hit a malaise. Jay Woods believes it's a buying opportunity
- AI-related companies to drive most third-quarter US earnings gains
- Nvidia and Micron shares bounce as investors get clarity on a key OpenAI matter
- Nasdaq, SPX Look to End Record-Filled Week With Gains
- Micron Has Evolved Into a Next Gen Player So I Keep Adding