
SANY Renewable Energy Reports Over 300% Overseas Revenue Growth at WindEnergy Hamburg 2026
Source: PR Newswire
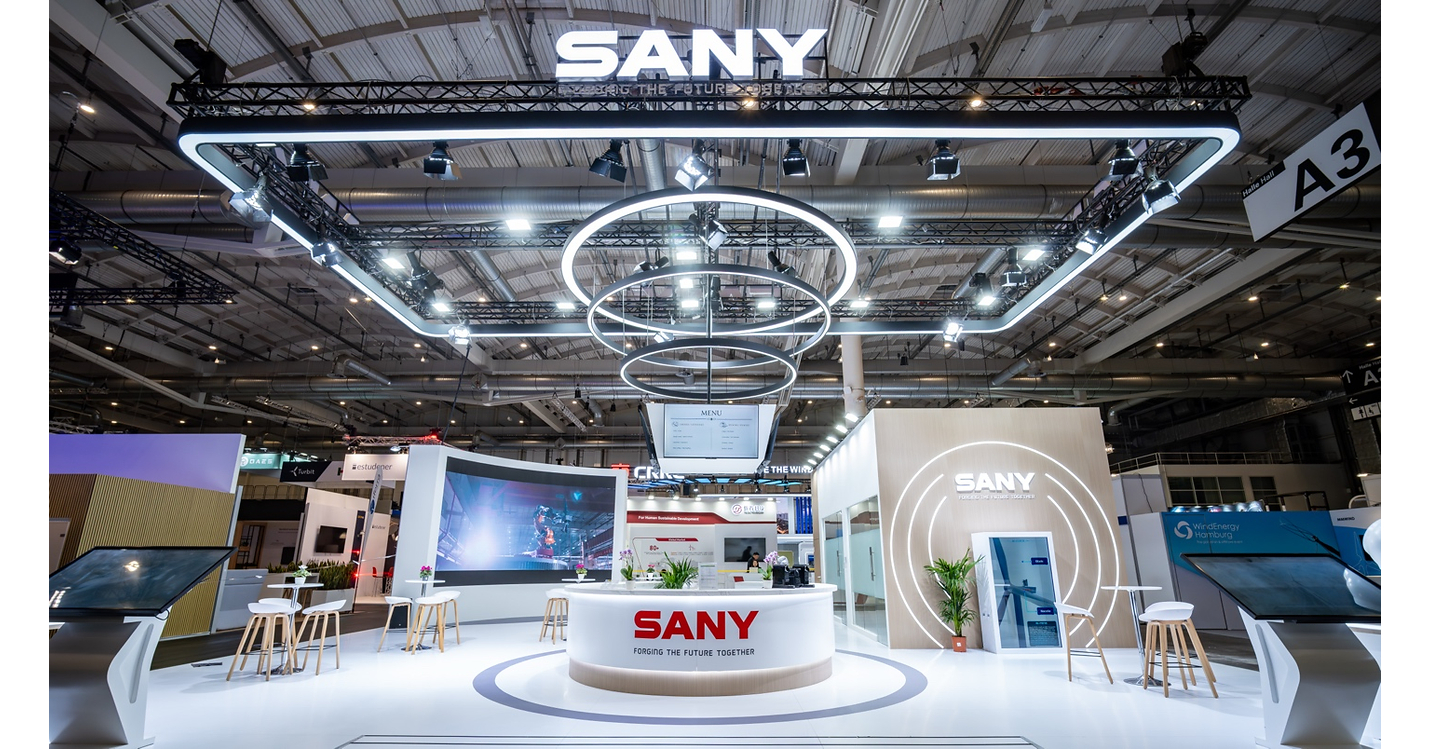
SANY Renewable Energy reported overseas revenue growth of more than 300% in H1 2026, with signed international orders nearing 5 GW and overseas installed capacity reaching 1,462.35 MW. DNV certified its SI-17578EU wind turbine for structural integrity, personnel safety and operational design, supporting European expansion. The company also showcased 10 MW turbine technology and a 35 MW test bench, while highlighting recent project commissioning milestones in Kazakhstan, Central Asia and Spain.
Analysis
The relevant market signal is not S&P Global’s inclusion itself, but whether third-party certification converts Chinese turbine cost advantages into financeable European projects. If lenders and insurers accept the certification in diligence, SANY Renewable Energy (688349 CH) can bid more aggressively in markets where Vestas (VWS DC), Nordex (NDX1 GR) and Siemens Energy (ENR GR) have historically benefited from bankability barriers rather than superior hardware economics. The first-order pressure would be on European OEM order pricing; the larger 6-18 month risk is lower service-margin durability if Chinese OEMs establish an installed base that creates recurring parts and maintenance relationships.
The company’s international growth claims remain low-quality as an investable signal until order backlog conversion, project-level financing, warranty provisions and European gross margin are disclosed. European permitting, local-content preferences, cybersecurity scrutiny and lender reluctance to underwrite an unseasoned operating history could materially slow conversion despite technical certification. This is therefore more negative for pure-play turbine OEM valuation multiples than for SPGI: certification activity is immaterial to SPGI earnings unless it signals a broader acceleration in renewable-project financing and ratings demand.
Consensus may overstate the near-term disruption. A single certified platform does not solve local service coverage, spare-parts inventory, grid-code compliance across countries, or the multi-year availability guarantees required by European asset owners. The investable inflection is a financed EU utility-scale award with disclosed pricing and warranty terms, not exhibition orders or installed-capacity milestones.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- No directional SPGI trade: the read-through to its ratings and sustainability-data revenue is too small relative to diversified earnings. Reassess only if renewable-project debt issuance or energy-transition ratings volumes show a sustained acceleration over the next 2-3 quarters.
- Place a 1-3 month watch on VWS DC and NDX1 GR for European tender awards involving Chinese OEMs. A disclosed SANY-financed EU project above 100 MW would justify reducing exposure to higher-multiple OEMs, particularly if the award implies pricing below incumbent benchmarks.
- Potential 6-12 month relative-value trade, contingent on verified EU order conversion: short VWS DC versus long ENR GR. Vestas has greater direct turbine-pricing and service-margin exposure, while Siemens Energy has materially more diversified grid-equipment exposure that can benefit from renewable grid-connection spending. Falsify if Vestas sustains service EBIT margin and order pricing despite Chinese participation.
- Avoid extrapolating the announcement into a broad clean-energy long. Monitor EU trade-defense actions, local-content rules and project-finance lender requirements; any formal restriction on Chinese wind equipment would reverse the competitive-risk thesis quickly and support European OEM multiples.
More News
- SpaceX Can't Join the S&P 500 Before June 2027 -- and Its Losses Could Keep It Out Longer
- Nvidia's Demand Is Outpacing Its 70% Growth Forecast, and That Is Just the Beginning
- Markets are rapidly coming around to the reality that the Fed has a lot more work to do
- Market sees next Fed hike in October, following Barr comments and hot inflation reading
- Business Activity in the Euro Area Reaches Three-Year High
- The Economy Is Booming, So the Market Indexes Fell. Go Figure.