
As AI Data Center Investment Heads Toward $31.6 Trillion, Mindstream Energy Builds Where the Power Already Exists
Source: PR Newswire
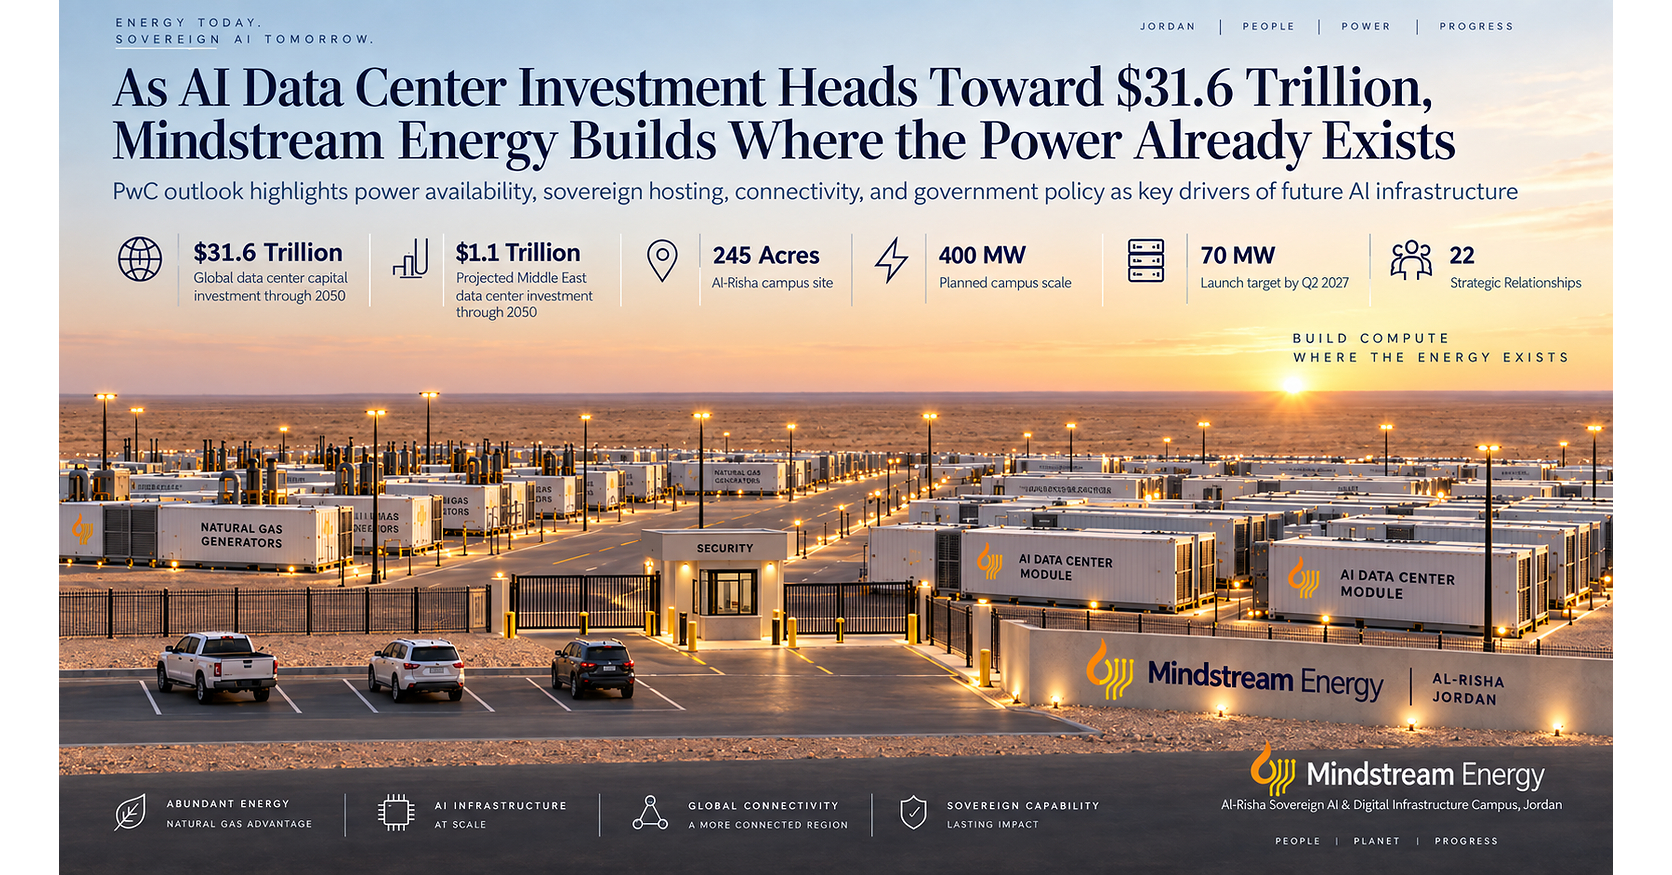
Mindstream Energy plans a 245-acre AI and digital-infrastructure campus at Jordan's Al-Risha Gas Field, targeting 400MW of capacity with an initial 70MW launch in Q2 2027. The company cites PwC projections for $31.6T of cumulative global data-center investment through 2050 and $1.1T of potential Middle East investment, emphasizing power availability and sovereign-hosting demand. The project remains developmental, supported by a long-term gas supply agreement, on-site generation, connectivity plans and discussions with 22 potential ecosystem partners.
Analysis
This is directionally supportive for the “power-constrained AI” complex, but not yet investable as a direct catalyst because the project sponsor is private and has disclosed neither contracted tenants, financing, delivered power cost, nor equipment procurement. The relevant public-market read-through is that remote, generation-adjacent campuses expand the addressable market for gas turbines, electrical equipment, cooling and fiber; GE Vernova (GEV), Vertiv (VRT), Eaton (ETN), Schneider Electric (SU.PA) and nVent (NVT) are better positioned than conventional colocation REITs if hyperscale demand migrates away from constrained Tier-1 grids.
The second-order constraint is not simply gas supply: a sovereign facility needs export-control-compliant accelerators, redundant international connectivity, convertibility of long-dated customer contracts and bankable political-risk insurance. Any failure on these items converts nominal low-cost power into stranded generation capacity. This favors equipment suppliers with paid backlog and global service exposure over developers whose economics depend on securing both GPU allocation and investment-grade offtake.
Over the next 1-3 months, the news flow is unlikely to alter estimates for listed infrastructure names. Over 6-18 months, a broader shift toward behind-the-meter and gas-backed compute would incrementally favor GEV and ETN, while pressuring the scarcity premium embedded in Digital Realty (DLR) and Equinix (EQIX) only if remote campuses demonstrate reliable latency, network quality and contracted utilization. The contrarian view is that sovereign-compute demand is frequently overestimated: national requirements may require local hosting, but do not necessarily create hyperscaler-scale utilization or returns sufficient to support dedicated 400MW-class buildouts.
The thesis is falsified if major cloud customers continue concentrating incremental capacity in established U.S./European hubs despite power delays, or if accelerator export restrictions limit deployment into non-core jurisdictions. Watch for independently disclosed take-or-pay contracts, project-finance terms, turbine orders and delivered PUE/power-cost metrics rather than partnership announcements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No direct position in Mindstream: treat as a private-market validation datapoint, not a tradable event, until customer commitments, funding and procurement are independently disclosed.
- Maintain a 6-18 month overweight in GEV and ETN versus DLR/EQIX as a basket: long GEV/ETN, short an equal-dollar DLR/EQIX basket. The payoff is strongest if grid interconnection delays force more self-powered deployments; exit if data-center power backlog commentary eases materially or GEV service/backlog conversion weakens.
- Add VRT only on a 10-15% pullback or following evidence that its AI backlog is converting to revenue rather than extending lead times. Upside comes from modular cooling demand across distributed campuses; key risk is hyperscaler capex digestion and gross-margin pressure from faster competitive supply.
- Set an alert for announced turbine, switchgear or cooling awards tied to Middle Eastern sovereign-compute projects. A disclosed order with customer financing and a named equipment vendor would be a more actionable catalyst for GEV, ETN, VRT or NVT than developer publicity.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Asian markets make nervous start ahead of Fed decision
- Iran war increasing inflation, straining US munitions: congressional report
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Advanced Search Filters, Redesigned Ticker Dashboard, and Improved Search Experience
- How to Build an Automated Research Process for a Fund