
Ballard closes acquisition of GeoPura, becoming an integrated hydrogen energy solutions provider
Source: PR Newswire
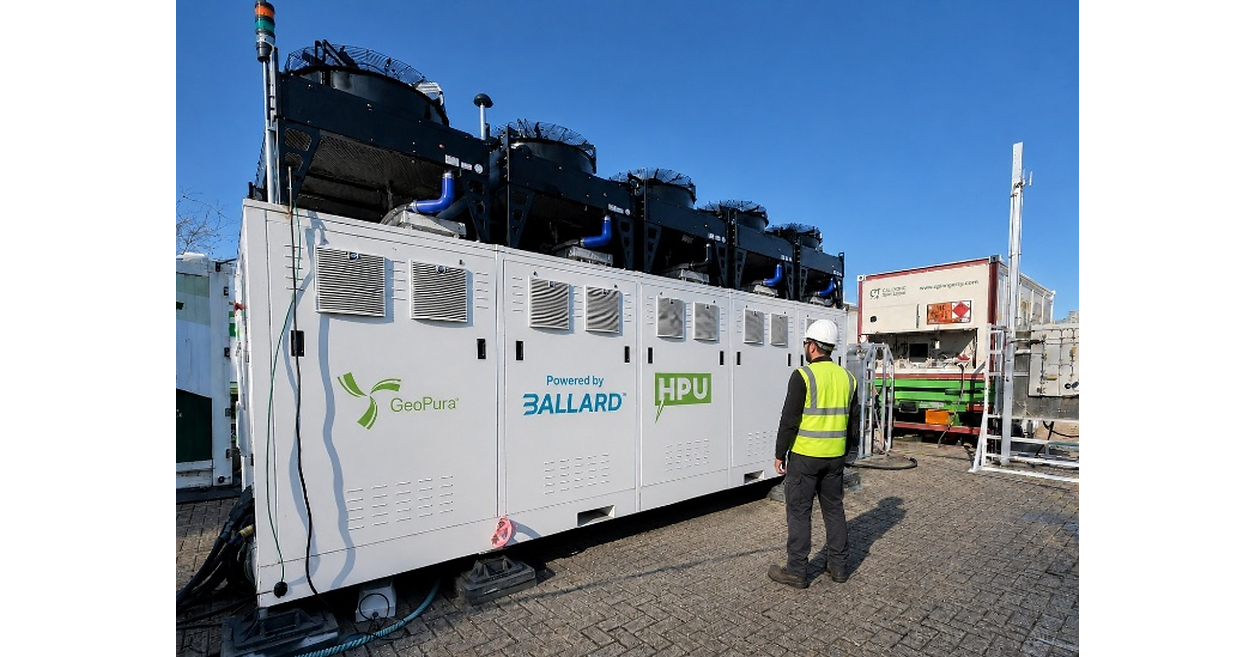
Ballard Power Systems closed the acquisition of UK hydrogen power provider GeoPura, positioning itself as an integrated hydrogen Energy-as-a-Service platform. The deal consideration totals £275.0 million (£82.5 million cash plus 49.6M newly issued Ballard shares/RSSUs, with additional shares to be settled in 12 months) and includes up to £27.5 million in contingent consideration tied to post-closing milestones. GeoPura shareholders will hold ~14.1% of Ballard on a pro-forma basis, and Ballard expects the integrated hydrogen production/logistics + fuel cell technology to unlock new commercial opportunities across Europe and North America.
Analysis
This is less a classic technology win than a business-model pivot: BLDP is moving from selling hardware into owning a more capital-intensive, service-heavy revenue stream. That can improve visibility and attach rates, but it usually comes with lower ROIC, more working-capital drag, and valuation compression versus a pure-play components story. The market may initially reward the “integrated platform” narrative, yet over 1-3 quarters the key question is whether recurring EaaS dollars translate into real free cash flow or just slower-burning dilution.
The second-order winner is any customer segment where grid access is the binding constraint — temporary power, events, construction, defense — because BLDP can now bid as a turnkey provider rather than a parts supplier. But that also puts it into direct competition with incumbent diesel and gas gensets, where uptime, fuel logistics, and total cost of ownership matter more than ESG branding; PSIX and similar distributed-power names should be more resilient if buyers revert to proven economics. Hydrogen EaaS is especially vulnerable if natural gas and diesel stay cheap or if grid interconnection timelines shorten, because the willingness to pay for zero-emission off-grid power is highly cyclical.
The contrarian miss is that vertical integration does not automatically create a moat if the bottleneck is hydrogen cost and utilization, not stack performance. The near-term catalyst is not the closing itself but the next disclosure on backlog quality, segment margin, and cash burn; absent hard numbers, this risks being treated as financial engineering plus narrative expansion. Falsifiers are straightforward: sustained disclosure of positive EaaS contribution margin and rising fleet utilization would force a reassessment, while any continued burn/dilution would validate the bear case over the next 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Short BLDP into post-deal strength over the next 1-3 weeks; thesis is that the market is overpaying for vertical-integration optionality before proving segment-level cash generation. Cover if management can show EaaS gross margin inflecting positive and utilization rising materially in the next quarterly print.
- Pair trade: long PSIX / short BLDP for 1-3 months as a relative-value bet that incumbent distributed-power economics remain superior to hydrogen EaaS in non-mandated off-grid applications. The pair should work best if energy prices soften or if BLDP fails to quantify near-term backlog conversion.
- Set an alert for BLDP’s next earnings release: specifically track cash burn, share count, and any disclosure on recurring revenue mix. If the acquisition raises revenue without improving FCF or adjusted EBITDA, the stock likely de-rates further.
- If BLDP rallies sharply on hype, consider buying short-dated puts rather than chasing the equity; the risk/reward is better for a mean-reversion trade because the fundamental proof point is months away, not days.
- Watch for a competitive read-through to generator names and fuel-cell peers: a weak BLDP reaction would be a constructive signal for PSIX and a caution flag for other hydrogen-adjacent equities, while a strong post-close hold would imply the market is willing to finance longer-duration hydrogen adoption.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Saudi Arabia says 1 dead, 11 injured in latest attack on Riyadh airport
- Why is LG Innotek stock plunging today?
- RBI Tightens Rupee Defense as Pricey Crude, Foreign Outflows Bite: USD/INR
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?