
Intel Takes Major Step Back (Rating Downgrade)
Source: seekingalpha.com
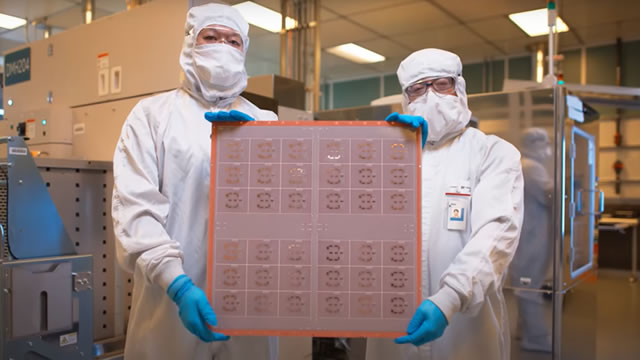
Intel reported Q3 revenue of $16.5 billion, up 20% year over year and in line with estimates, while non-GAAP gross margin reached 44.1% and adjusted net income rose 169% to $2.8 billion, driving a strong non-GAAP EPS beat. Management warned of accelerating PC market weakness and guided Q4 revenue to $15–$16 billion, well below consensus, with further softness expected into 2027.
Analysis
The issue is whether margin recovery can survive weaker unit volumes. If PC demand contracts while Intel’s manufacturing base carries high fixed costs, lower utilization and adverse mix could reverse recent margin gains; improved margins alone do not establish durable earnings power. The market may therefore shift from rewarding execution progress to discounting a weaker forward earnings base. Near term, guidance risk can pressure the stock; over the next 1–3 months, channel inventory, PC shipment trends and the next outlook are the key checks. Over 6–18 months, persistent weakness would raise the bar for product execution and make capacity economics more consequential. PC OEMs and component suppliers may face inventory and pricing pressure. AMD and Qualcomm could gain share if buyers substitute platforms, but both remain exposed to a shrinking PC market, so share gains need not translate into absolute growth. The contrarian case is that the margin improvement provides a cushion and expectations may already be resetting; that case strengthens only if utilization and margins hold as demand softens. Verify the source of margin improvement, segment mix, inventory and cash conversion before treating it as structural.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Ticker Sentiment
Key Decisions for Investors
- Favor a modest underweight in INTC or a market-neutral short INTC / long SOXX position over the next 1–3 months, preferably on strength rather than chasing an immediate decline. The thesis is company-specific earnings risk; size for the possibility that a broad semiconductor rally lifts INTC too.
- Do not use AMD or Qualcomm as unhedged proxies for the trade: potential share gains are offset by their own PC-market exposure. Reassess after channel-inventory data and Intel’s next guidance update.
- Falsify the bearish thesis if PC inventories and shipments stabilize and Intel sustains margins without relying on favorable mix or temporary cost actions. Escalate the risk if guidance deteriorates again or utilization and cash conversion weaken.
More News
- Asia shares bend under AI stress; Apple earnings loom
- Here are 3 big things we're watching in the stock market in the week ahead
- Asia stocks rise as tech gains ahead of Apple results
- Morning Bid: Markets hope for relief in Apple margins
- Intel: PC Demand Destruction Meets AI Supply Headwinds-Profit Taking Continues
- Intel: The Panic Buying Opportunity Is Finally Here