
Nobu Hotel Palo Alto Reintroduces Its Exclusive Ryokan Suites, Debuts New Ryokan Reset Package in Partnership With HigherDose
Source: PRWeb
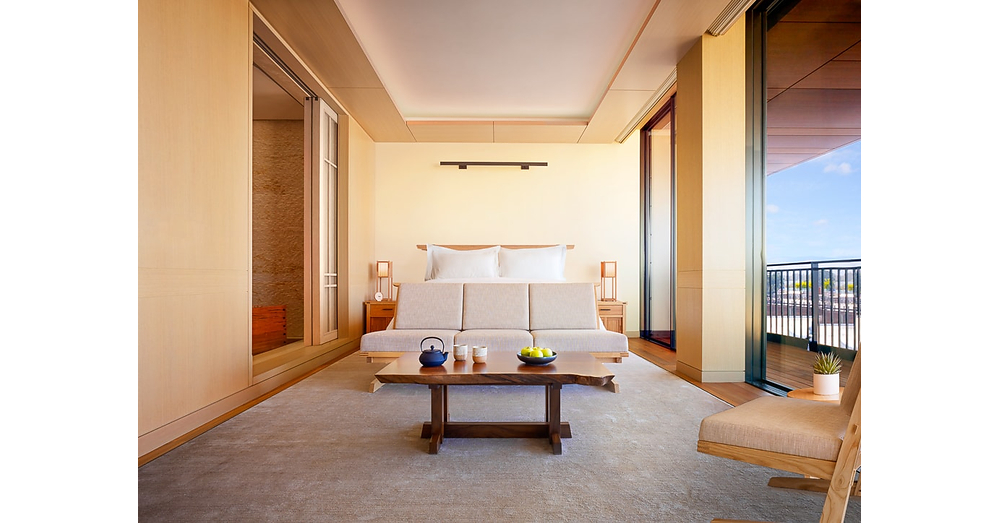
Nobu Hotel Palo Alto relaunched its five Ryokan Suites and introduced the $2,000-per-night Ryokan Reset wellness package in partnership with HigherDOSE. The offering combines luxury accommodations with in-suite red-light therapy, PEMF technology, wellness products and Japanese tea rituals, targeting Silicon Valley travelers seeking privacy and recovery. The announcement is a product and positioning enhancement for the 73-room boutique hotel, with limited broader market relevance.
Analysis
This is not a material demand signal for PTON: the property-level partnership is too small and the wellness equipment is not Peloton-branded. The relevant read-through is qualitative—premium hospitality is increasingly packaging recovery and wellness as an ADR-supporting amenity rather than relying solely on room upgrades, which marginally validates the broader connected-wellness category but does not create measurable hardware or subscription revenue for PTON.
The more investable second-order implication is that luxury hotels may become a customer-acquisition channel for wellness brands, but HigherDOSE’s modality is adjacent rather than complementary to PTON’s core cardio/strength offering. If hotel operators allocate wellness capex toward compact, in-room devices instead of shared fitness spaces, that could reinforce PTON’s challenge in penetrating hospitality: its bikes require floor space, servicing, user-account integration and a clearer ROI. Near-term PTON price action should remain governed by subscriber retention, gross margin, free-cash-flow conversion and any evidence that marketing efficiency can support renewed hardware growth.
Contrarian view: wellness-hospitality partnerships are promotional proof points, not evidence of scalable B2B unit economics. A broader hotel rollout could eventually make hospitality a viable distribution vertical for PTON, but only if management discloses contracted locations, equipment economics, recurring content attach rates and service costs. Absent those data, this release warrants no earnings-estimate change and no directional trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No action on PTON from this item; treat any sympathy move as noise unless accompanied by disclosed hotel contracts or a measurable change in paid-subscriber guidance.
- Set a 1-3 month watch item for PTON’s next earnings: a credible hospitality thesis requires sequential growth in paid subscriptions alongside stable or improving hardware gross margin; failure on either metric would falsify a premium-channel expansion narrative.
- For travel-and-leisure exposure, monitor luxury lodging operators with meaningful Palo Alto/Silicon Valley or wellness-resort exposure rather than extrapolating to PTON; a single 73-room property cannot move sector ADR or RevPAR estimates.
- Do not underwrite HigherDOSE-related wellness claims into public-equity forecasts without independently verifiable rollout, utilization, or revenue data.
More News
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests
- French police use tear gas and water cannons after some protests turn violent as shopkeepers board up storefronts across Paris
- IMDELLTRA® IN COMBINATION WITH IMFINZI® REDUCED RISK OF DEATH BY AN UNPRECEDENTED 58% IN FIRST-LINE EXTENSIVE STAGE SMALL CELL LUNG CANCER