
Starlight Investments annonce la clôture réussie du fonds britannique BTR II
Source: PR Newswire
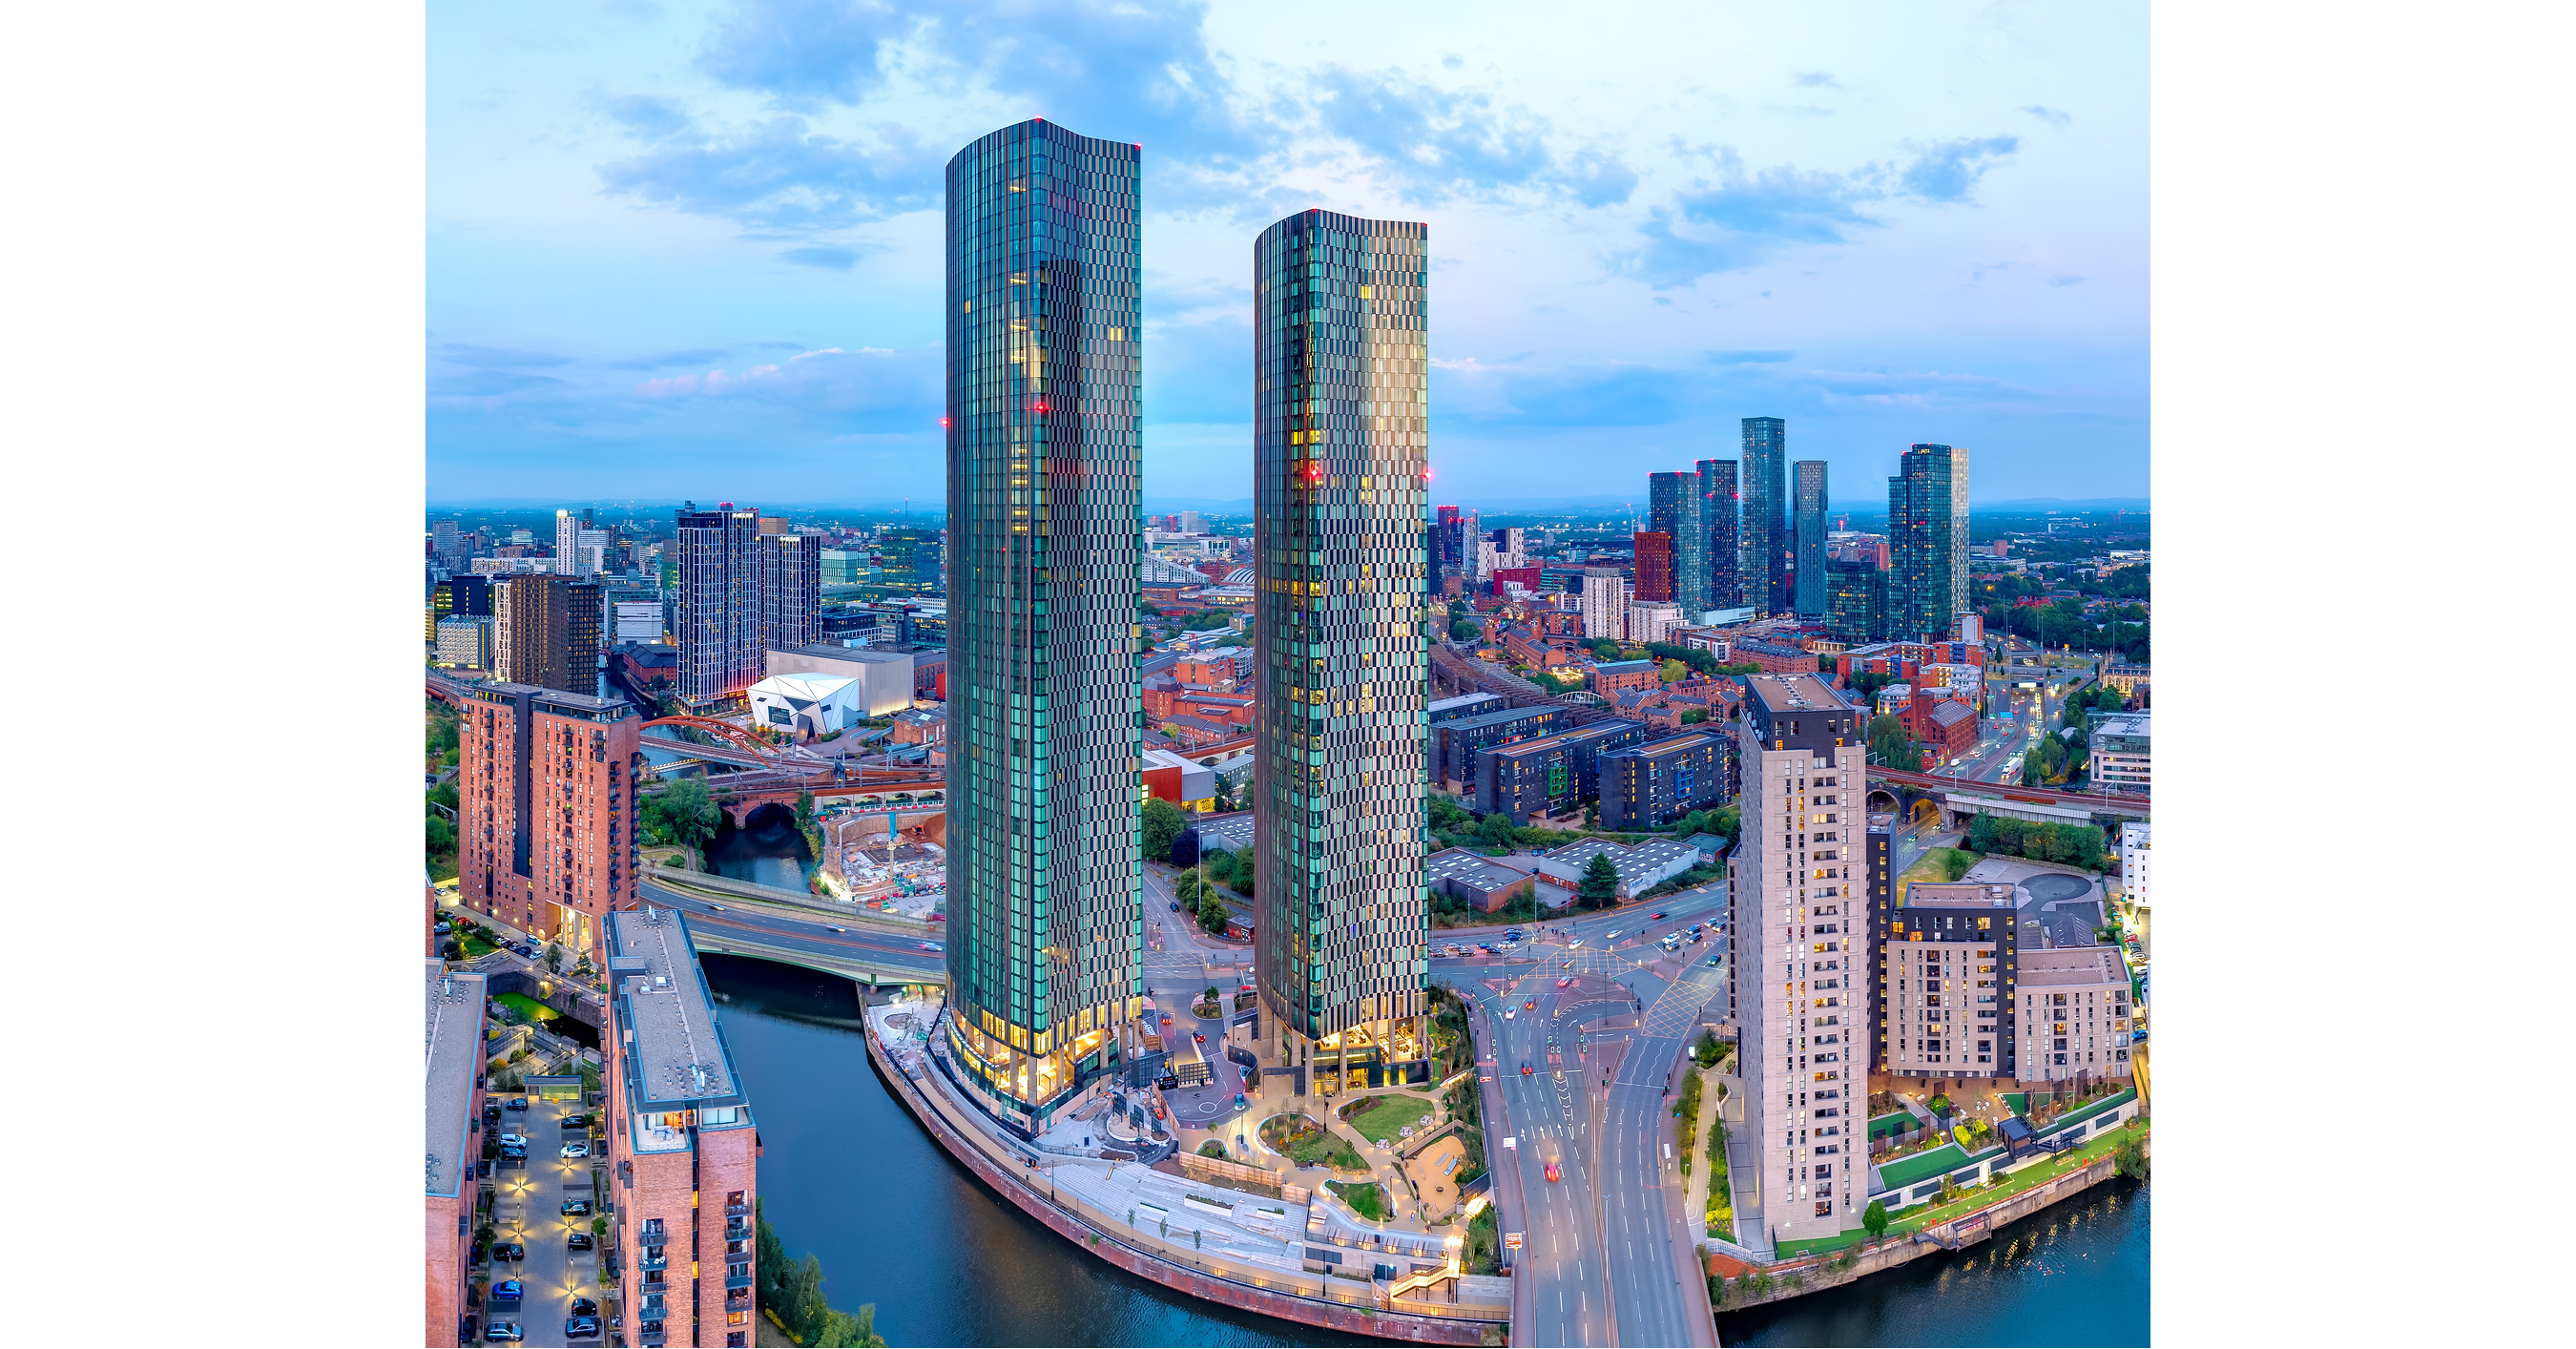
Starlight Investments closed its UK BTR Fund II and related investment vehicles with £680 million of capital commitments to acquire and deliver more than 6,000 rental homes across the UK. The partially deployed fund includes three development sites—two in Manchester and one in Basildon—and received backing from a diversified institutional investor base, including a significant commitment from Homes England's National Housing Bank. Starlight's 12-project UK platform is expected to position it among the four largest UK build-to-rent operators as developments are completed and leased.
Analysis
This is more useful as a private-market clearing-price signal than a public-equity catalyst. Institutional capital remains available for UK rental housing with development exposure, which should support transaction liquidity and cap-rate discovery for listed UK residential landlords and REITs over the next 1-3 months. The strongest read-through is to operators with stabilized regional rental portfolios and lower near-term refinancing needs, notably Grainger (GRI.L); it is less favorable for highly leveraged developers whose construction-cost overruns or debt costs can absorb rental growth.
A second-order effect is tighter competition for buildable sites and contractor capacity in Manchester and London commuter markets. That can raise replacement costs and ultimately support net asset values for incumbent owners, but it pressures development margins for peers still underwriting projects at older cost assumptions. Private fund equity is not evidence that development yields are attractive after financing costs; the relevant verification point is whether completed assets lease at rents sufficient to clear current UK gilt-linked debt costs.
Near term, no broad trade is warranted from a single fund close. Over 6-18 months, a sustained institutional bid for BTR could narrow the public/private valuation discount in GRI.L and selected UK REITs, provided UK rates decline or remain stable and rental regulation does not cap reversionary income. The contrarian risk is that fresh capital prolongs an oversupply pocket in Manchester: concessions, slower absorption, or falling achieved rents would expose the difference between headline housing scarcity and local submarket economics.
The key falsifiers are a renewed rise in UK 10-year gilt yields, evidence of rising lease-up incentives in Manchester, or policy action limiting rent increases. Conversely, evidence of asset sales at or above book value, improving development yields, and declining net-debt/EBITDA would turn this from a sentiment signal into a valuation catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- Watch-list Grainger (GRI.L) for a 1-3 month long entry following confirmation of stable rental growth and no deterioration in financing guidance; target a partial closing of any discount to private-market residential valuations, with exit discipline if UK 10-year gilt yields rise materially or management cuts development-return targets.
- Prefer a relative-value expression: long GRI.L / short UK Residential REIT ETF exposure or a higher-leverage UK property proxy, sized only after comparing debt maturities and regional Manchester exposure. The thesis is that operational scale and balance-sheet flexibility outperform where site and construction competition intensifies.
- Avoid extrapolating this into a blanket long on UK developers. Set an alert for Manchester BTR leasing data: occupancy below underwriting pace or rising incentives would favor shorts in regional development-heavy names rather than stabilized landlords.
- Monitor listed UK REIT asset-disposal announcements over the next two reporting cycles. A transaction at a tight discount to NAV is the actionable confirmation for adding residential-property exposure; absent that evidence, treat the announcement as private-market fundraising rather than a repricing event.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- Trump set to announce plan by Audi to build a U.S. factory in Georgia, source says
- Why popular airplanes are getting scrapped years early
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market