
Private Capital Keeps Faith in Crisis-Hit France
Source: Bloomberg
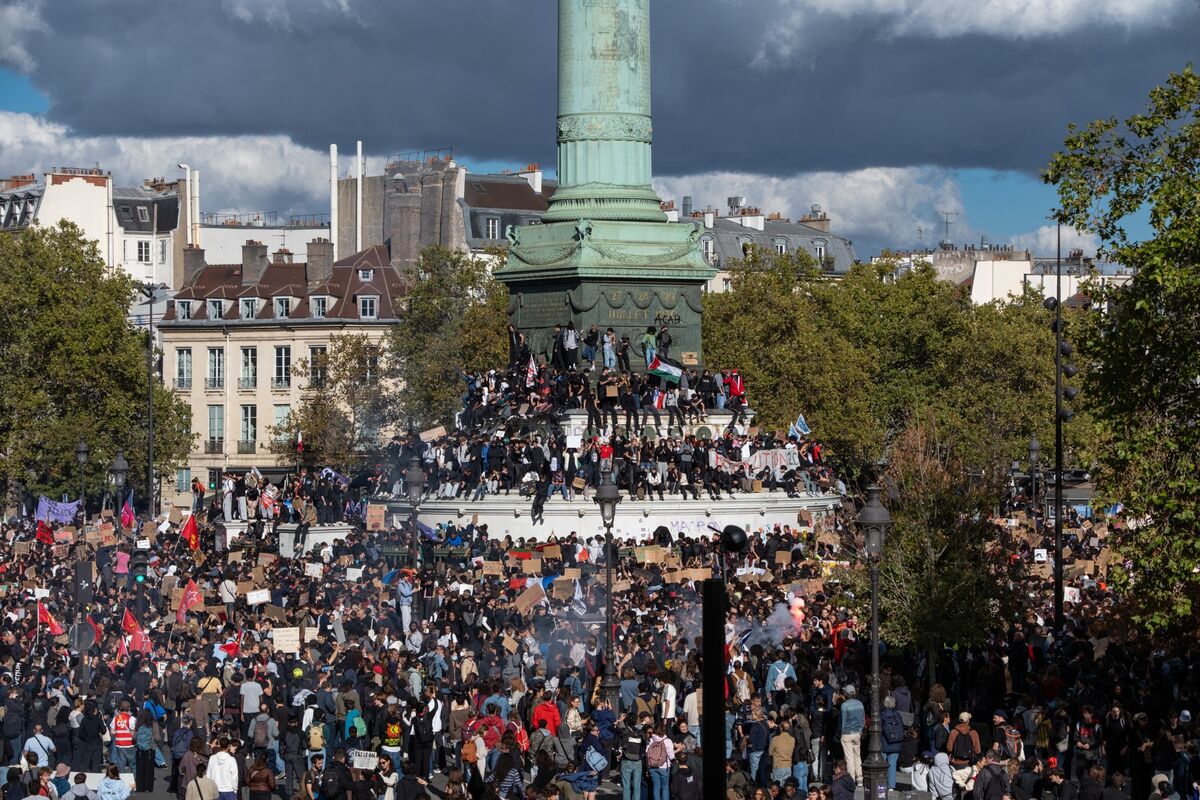
France’s €3 trillion economy faces months of likely political and social unrest, while sovereign bonds are roiling. The article says private capital markets are holding their breath but striving to remain open for business; it gives no specific market moves or deal figures.
Analysis
The investable risk is a widening gap between private-market marks and the cost of financing them. If French sovereign volatility persists, higher local funding costs and weaker lender risk appetite could delay leveraged buyouts, refinancing and exits before they show up in reported private-asset valuations. That creates a lagged risk to European buyout fundraising and realizations, while lenders with concentrated French exposure may face tighter underwriting and lower deployment. Conversely, non-French European assets could gain relative appeal if capital is redirected rather than withdrawn from the region.
The near-term catalyst is political and sovereign-spread volatility; over 1–3 months, watch whether it changes deal financing terms, transaction timelines or fundraising. A 6–18 month downside scenario is persistent uncertainty translating into lower deal volumes and delayed distributions, pressuring private-equity managers’ fee-related growth and investor liquidity. The countercase is that private capital is less exposed to daily market repricing and can wait for dislocation, potentially buying assets at better entry valuations.
The article provides no spread levels, fundraising data, deal pipeline or firm-level exposure, so a directional private-equity trade is not yet supported. The key falsifiers are stabilization in French sovereign spreads alongside continued French deal activity and unchanged financing terms; sustained spread widening plus stalled transactions would strengthen the downside thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Key Decisions for Investors
- Avoid adding concentrated French private-market exposure until sovereign volatility is reflected in financing terms and deal activity; treat reported private-asset marks as lagging, not proof of resilience.
- Monitor the OAT–Bund spread and French deal-financing conditions as hedging triggers. Consider reducing France-sensitive European financial or private-equity exposure only if widening spreads coincide with weaker deal flow; the article alone does not establish an entry point.
- Prefer relative diligence over a broad Europe short: test whether fundraising and transactions are shifting toward non-French European markets or simply being deferred. A confirmed diversion would support relative exposure; broad delays would argue for lower sector risk.
- Track political developments, lender underwriting, refinancing activity and exit/distribution data over the next 1–3 months. Reassess the cautious stance if spreads stabilize and transactions continue without material changes to terms.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- U.S. budget deficit swells to almost $2 trillion for fiscal 2026, up 12% in a single year
- Wall Street Anxiety Spreads as AI Rout Meets $110 Oil Shock
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- Why is VanEck Semiconductor ETF sliding today?