
AlphaESS uvádí AlphaQ na trh v Beneluxu
Source: PR Newswire
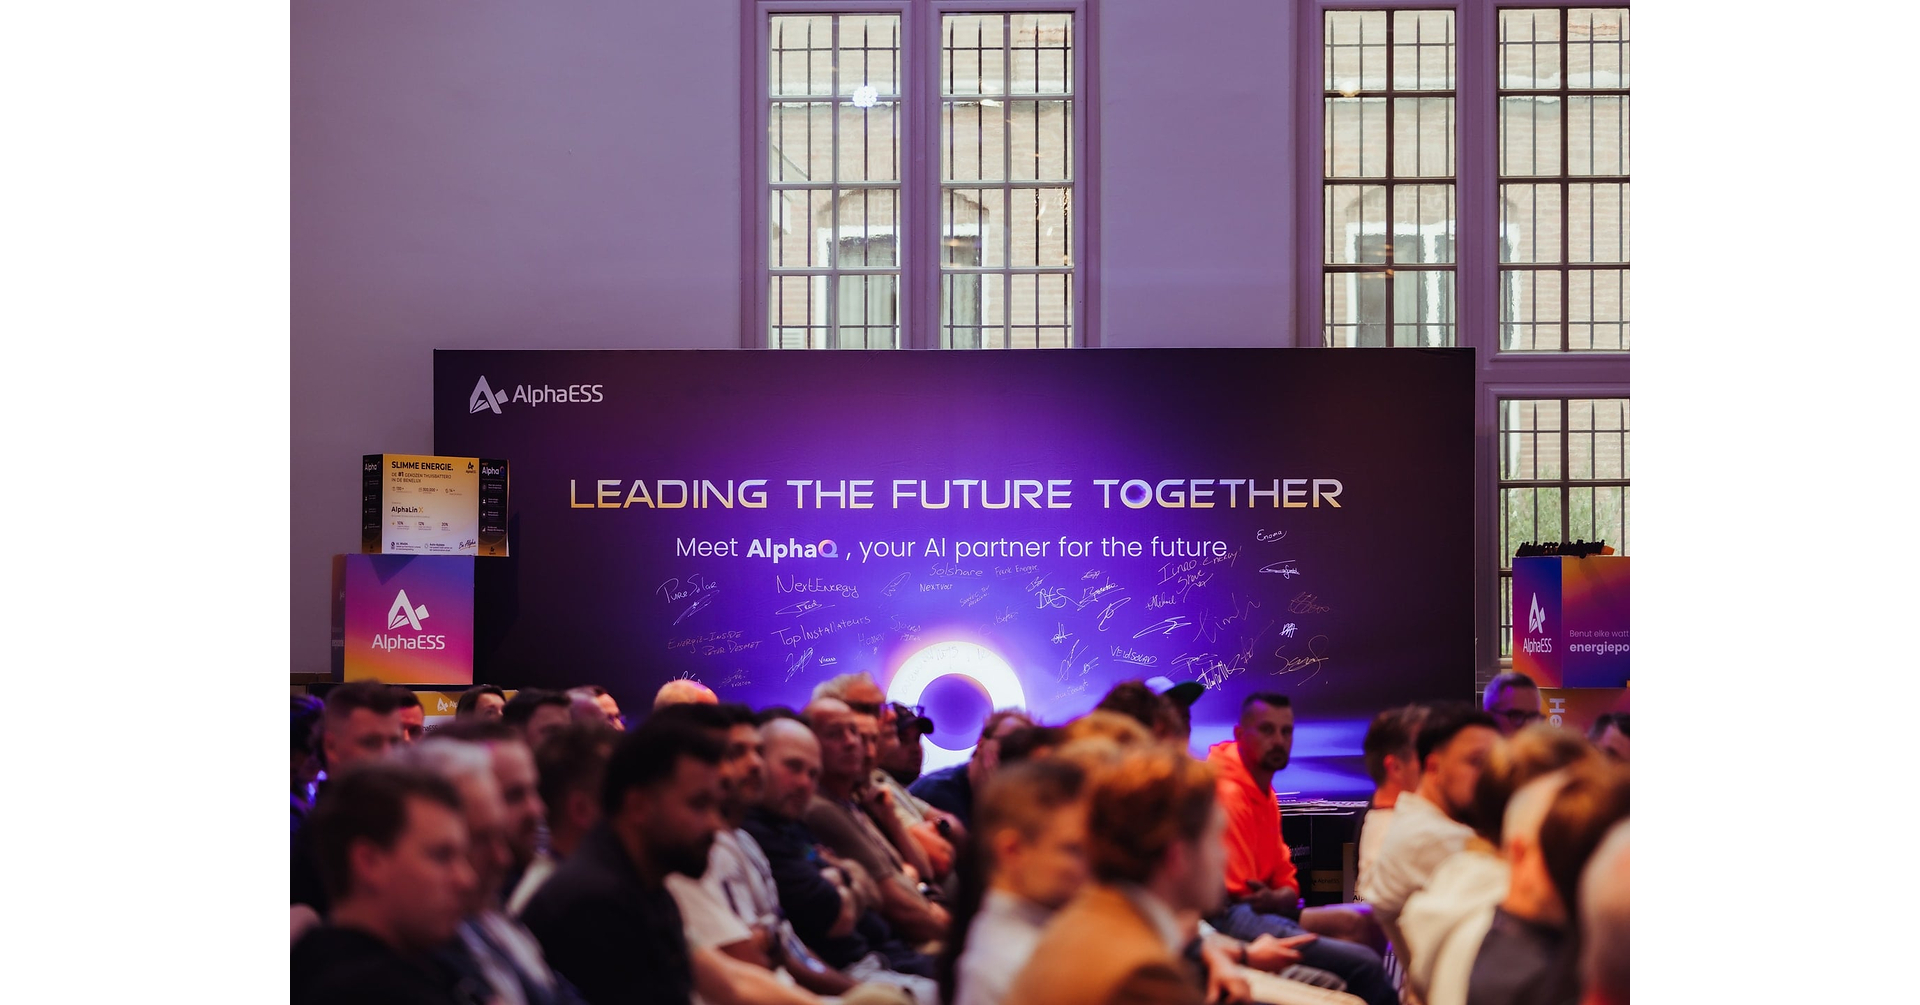
AlphaESS launched its AI-based AlphaQ home-energy agent in Belgium and the Netherlands, combining energy insights, tariff-aware battery management and service diagnostics. The company also opened Dutch preorders for the VitaPower 3600 AC, a modular 4–16 kWh home battery with 3.68 kW bidirectional AC output, expandable from an 800 W plug-and-play installation. AlphaESS cited first-half 2026 residential BESS market shares of 29.7% in the Netherlands and 19.5% in Belgium, supporting its Benelux expansion.
Analysis
This is not independently investable news because AlphaESS is private and the disclosed penetration figures are company-cited rather than independently audited. The relevant public-market read-through is that software-led battery dispatch is becoming table stakes in European residential storage: hardware vendors that cannot monetize tariff optimization, remote diagnostics, and installer support risk higher churn, warranty costs, and channel discounting rather than an immediate volume shock.
Near term (days to 1 month), there is no reason to alter positions in ENPH or SEDG on this release alone. Over 1-3 months, Dutch and Belgian dynamic-power-price adoption is the key validation point: higher customer savings from automated dispatch would support attach rates for batteries relative to standalone solar and favor integrated ecosystems over inverter-only offerings. The second-order beneficiary is the installer channel, since better remote fault resolution can lower truck rolls and improve installation throughput; conversely, this erodes a traditional service differentiation for incumbent inverter brands.
The contrarian view is that consumer economics—not AI functionality—will determine adoption. If wholesale-price volatility compresses, retail tariff structures limit pass-through, or grid/export rules become less punitive, the incremental value of a home battery can fall sharply despite better optimization software. Over 6-18 months, the more material risk is commoditization: software features may increase demand but also make battery hardware less differentiated, shifting surplus toward low-cost cell suppliers and distribution partners rather than branded system vendors.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate directional trade from the launch; keep ENPH and SEDG on watch rather than treating this as a catalyst, given the private-company source and absence of disclosed orders, pricing, or channel commitments.
- Monitor ENPH European battery attach-rate commentary and gross-margin guidance over the next two earnings cycles. A sequential European storage attach-rate improvement without margin deterioration would support a 3-6 month long ENPH thesis; falsifier: weaker European revenue guidance or further gross-margin compression from channel incentives.
- Use SEDG as the higher-risk competitive-disruption monitor: if management identifies rising European residential-storage pricing pressure or elevated service costs, a 1-3 month short or ENPH-long/SEDG-short relative trade becomes more attractive. Avoid entry absent earnings confirmation because both names remain highly sensitive to broader residential-solar demand and interest rates.
- Track Dutch day-ahead power-price dispersion, retail dynamic-tariff enrollment, and changes to export-compensation rules over the next 6-12 months. Sustained narrowing in price dispersion would weaken the residential-storage optimization thesis and argue against adding exposure to solar-plus-storage equities.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Arming Taiwan an important US interest, Taipei official says after Trump-Xi summit
- Facebook found liable as TikTok settles for $100m over user safety
- Bond market alarms are ringing on Wall Street. Here's what's ahead