
IQST - IQSTEL Reports Preliminary Q3 2026 Revenue of $106.0 Million; Nine-Month Revenue Up 35% Organically to $314.0 Million
Source: PR Newswire
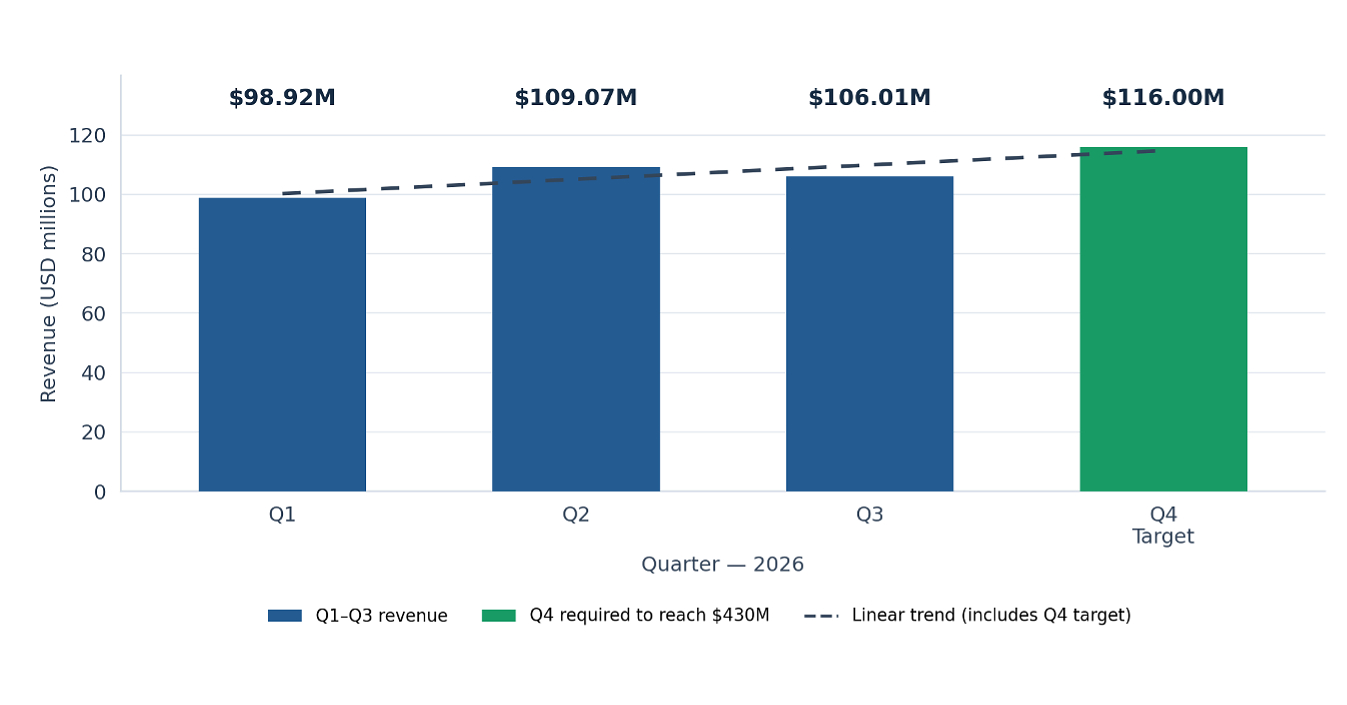
IQSTEL reported preliminary, unaudited nine-month 2026 revenue of approximately $314.0 million, up 35% year over year through organic growth; Q3 revenue was $106.0 million, down 2.8% from Q2's record $109.1 million. The nine-month total represents 73% of the company's $430 million 2026 objective, which requires about $116.0 million in Q4, 9.4% above Q3. IQSTEL has a binding MOU to acquire a 51% stake in Ultranet, which reported audited 2025 revenue of $130.9 million and net income of $4.6 million; closing is targeted for Q1 2027, subject to conditions, and the company says the acquisition is expected to make it cash-flow positive.
Analysis
The key distinction is revenue scale versus economic value. Telecom traffic can add substantial top-line volume without comparable gross profit or cash generation; the release gives no gross margin, EBITDA, operating cash flow, or working-capital data to validate that the growth is accretive. Treat the $430 million objective as a volume milestone, not an earnings anchor, until those metrics are disclosed.
The Q4 hurdle is also a near-term execution test: management’s seasonality rationale is not evidence that the required sequential rebound is in hand. Final Q3 results and Q4 revenue quality matter more than headline attainment. Over the next 1–3 months, monitor the 10-Q for margins, receivables/payables, cash conversion, and any revision to the full-year objective.
Ultranet adds a separate transaction risk. If control leads to consolidation, reported revenue may include more than IQST’s 51% economic ownership; minority interest, integration, currency, and working-capital needs can therefore make headline combined revenue a poor proxy for value. The stated cash-flow benefit remains unverified until definitive terms, closing, and post-close cash generation are visible. The secured notes and warrants warrant close review of covenants and potential dilution.
Contrarian view: the large growth rate and market-size claims can distract from the missing profitability evidence. Conversely, a modest Q3 sequential decline alone does not disprove growth if seasonal strength recurs. No valuation or consensus data are supplied, so a directional price call is not justified.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not chase IQST on the revenue update alone. Reassess after the Form 10-Q: require evidence of stable or improving gross profit, operating cash flow, and working-capital conversion; a revenue beat without those would not confirm fundamental quality.
- Treat the $430 million objective as a near-term catalyst, not a base case. If Q4 guidance or reported revenue falls short of the required rebound, expect the growth narrative to weaken; if met, check whether margin and cash conversion also improve.
- Keep Ultranet as a watch item rather than underwriting the pro forma scale. Before assigning acquisition value, verify definitive purchase terms, regulatory progress, financing covenants, treatment of minority interest, and post-close cash generation.
- Falsifiers: final Q3 figures materially below preliminary results, a reduced FY objective, deteriorating gross profit or cash conversion, or delayed/changed Ultranet terms. No standalone trade is warranted without valuation, liquidity, and profitability data.
More News
- Magnificent 7 loses $1 trillion. The most eye-popping stats from Thursday's tech stock plunge
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Wall Street’s best post-midterm rally in 44 years lasted just one day—then $3 trillion vanished as chip stocks plunged over AI fears
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- AI stocks plunge after election, driving down US markets
- Qualcomm slides 9% after earnings, leading post-election chip stock sell-off