
Princess Cruises Unveils Expansive 2028-2029 Americas Season with Return to the Amazon
Source: PR Newswire
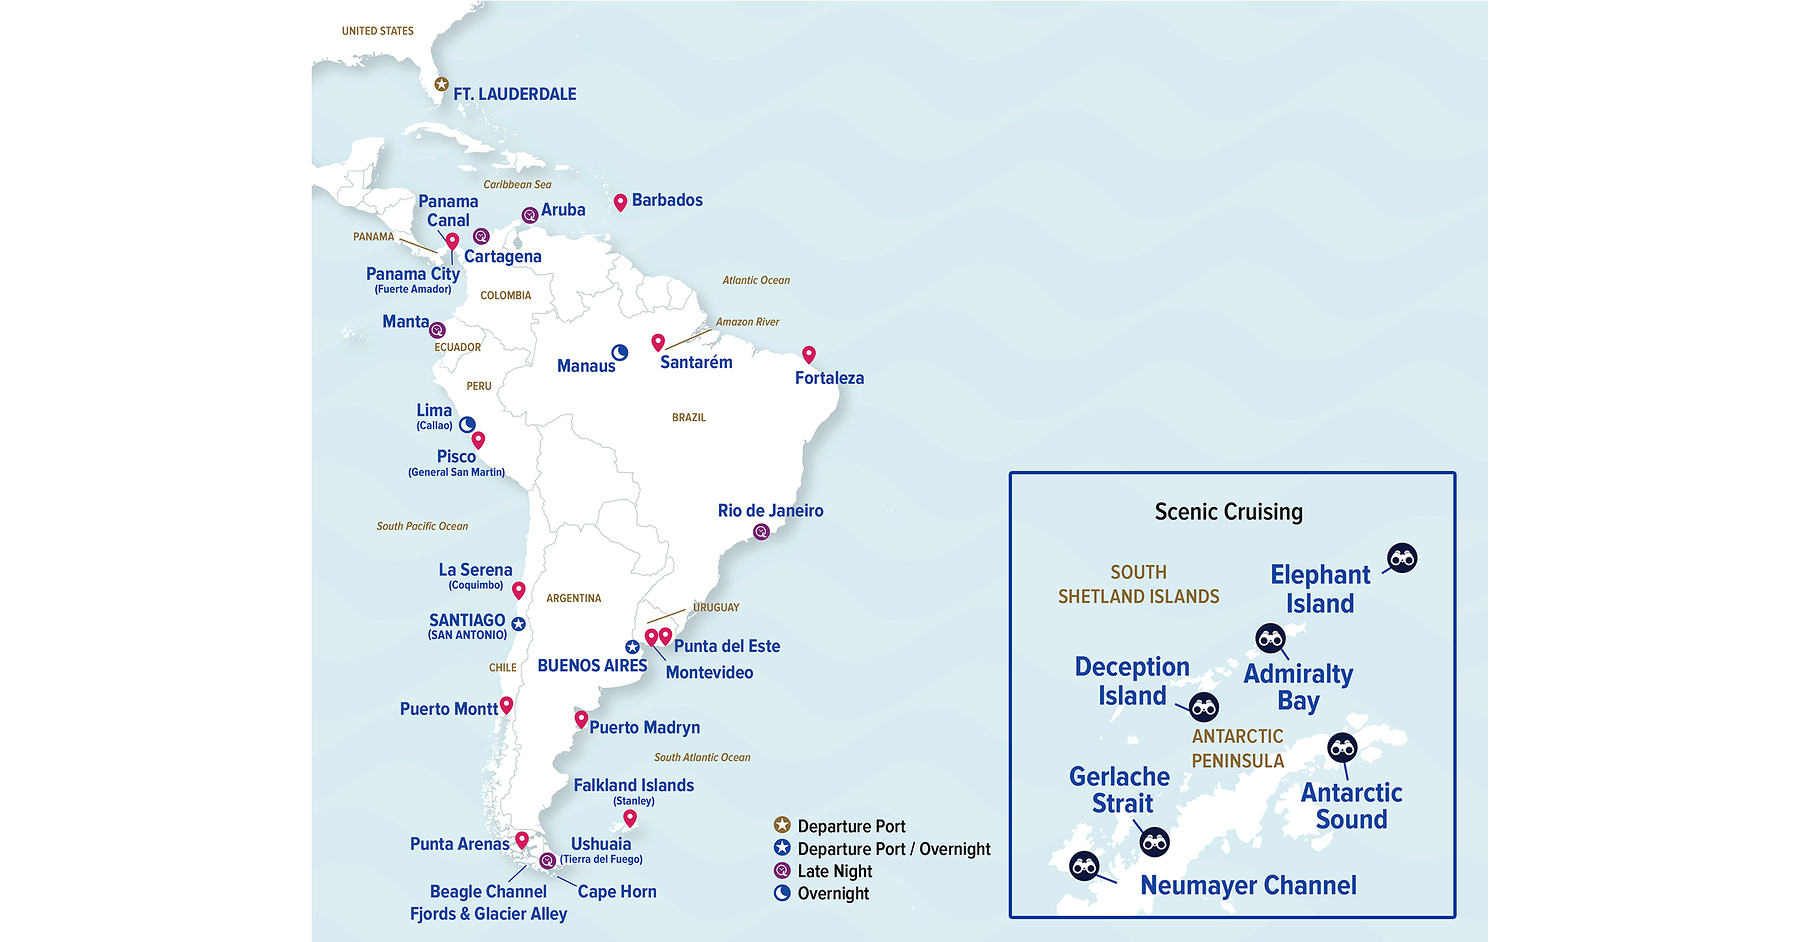
Princess Cruises announced its 2028–2029 Americas program, with more than 250 departures spanning destinations from Canada to Antarctica, including a new 64-day South America circumnavigation and the return of Amazon River cruising for the first time since 2014. The season includes 141 Caribbean departures and offers early-booking benefits of up to $300 in savings and up to $300 onboard credit through February 16, 2027.
Analysis
This is a product-marketing announcement, not evidence of incremental demand or improved economics for Carnival (CCL). The key read-through is the booking funnel: selling 2028–29 voyages this early, alongside discounts, onboard credit and low deposits, may help secure reservations and customer cash well before sailings. But those incentives can also pull bookings forward or dilute realized fares; deposits are not a proxy for yield, and the release provides no booking-curve, capacity or pricing data.
The strategic upside is modest differentiation through longer port stays and unusual itineraries, which could support onboard spending and customer choice if guests value the added time ashore. The counterweight is execution complexity—remote itineraries and more port calls can increase fuel, port and operating exposure—and the announcement does not establish that these voyages are large enough to move consolidated results. Private-island stops also reinforce a broader cruise-industry competition for control of the guest experience, rather than creating a clear moat for Princess versus Royal Caribbean or Norwegian Cruise Line.
Near term, likely little fundamental price impact. Over 1–3 months, monitor whether early bookings translate into stronger net ticket pricing rather than incentive-led volume. Over 6–18 months, the thesis matters only if itinerary mix and onboard revenue improve returns without cost or discounting pressure. The contrarian point: itinerary breadth sounds like growth, but the commercially relevant signal is net yield per available berth day, not the number of departures. No trade is justified from this release alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No event-driven CCL position: the announcement offers no quantified capacity, booking, pricing or earnings change.
- Watch CCL quarterly net ticket revenue per available berth day, advance-booking curves and onboard revenue. Consider a long only if these improve without heavier promotional incentives; reassess if net yields weaken or guidance is cut.
- Treat the early-booking offer as a potential demand-acquisition cost, not proof of pricing power. A rise in bookings accompanied by weaker net pricing would falsify the bullish read-through.
- Monitor fuel and port-cost exposure as the long-duration itineraries approach deployment; sustained cost increases or cancellations would undercut any benefit from itinerary differentiation.
More News
- South Korean carmaker Hyundai plans 'strategic' investment of $15.5 billion in India by 2032
- Applied Materials’ $5 billion AI lab aims to cut chip development time in half—and restore Silicon Valley’s edge
- Wells Fargo CFO on Earnings, Deals, Consumer Strength
- Bank of America hit with more than $1.2 billion in penalties over money-laundering violations
- Airport attacks put aviation in crosshairs of geopolitical conflicts
- Meta’s Muse models reach the AI frontier—and kill any hopes to ‘pace’ it